


EN
What AddLife Stock Results Means For Shareholders
- AddLife reported third quarter 2026 sales of SEK 2,599 million and net income of SEK 127 million, with basic earnings per share from continuing operations at SEK 1.05.
- Across the first nine months of 2026, AddLife kept sales and profit moving in tandem. Revenue of SEK 7,965 million translated into SEK 384 million of net income and higher earnings per share than a year earlier.
- We will now look at how AddLife's investment narrative is shaped by the stronger earnings per share trend reported for 2026.
Scan how AddLife's earnings momentum compares with peers by running the hand picked list of solid balance sheet and fundamentals (199 results).
AddLife Investment Narrative Recap
For an investor in AddLife, the core belief is that a focused Nordic life sciences supplier can keep improving profitability by pruning weaker products and leaning on higher margin areas like orthopedic surgery and advanced lab tools. The latest quarter showed earnings per share from continuing operations at SEK 1.05, which supports that margin focused story in the near term.
The next key catalyst is execution on organic growth and tenders, particularly in Labtech and Medtech, without letting working capital and inventory expansion strain cash flow. The main operational risk is that higher debt and any hit to academic or healthcare demand could squeeze flexibility just as the group is investing in new products and acquisitions.
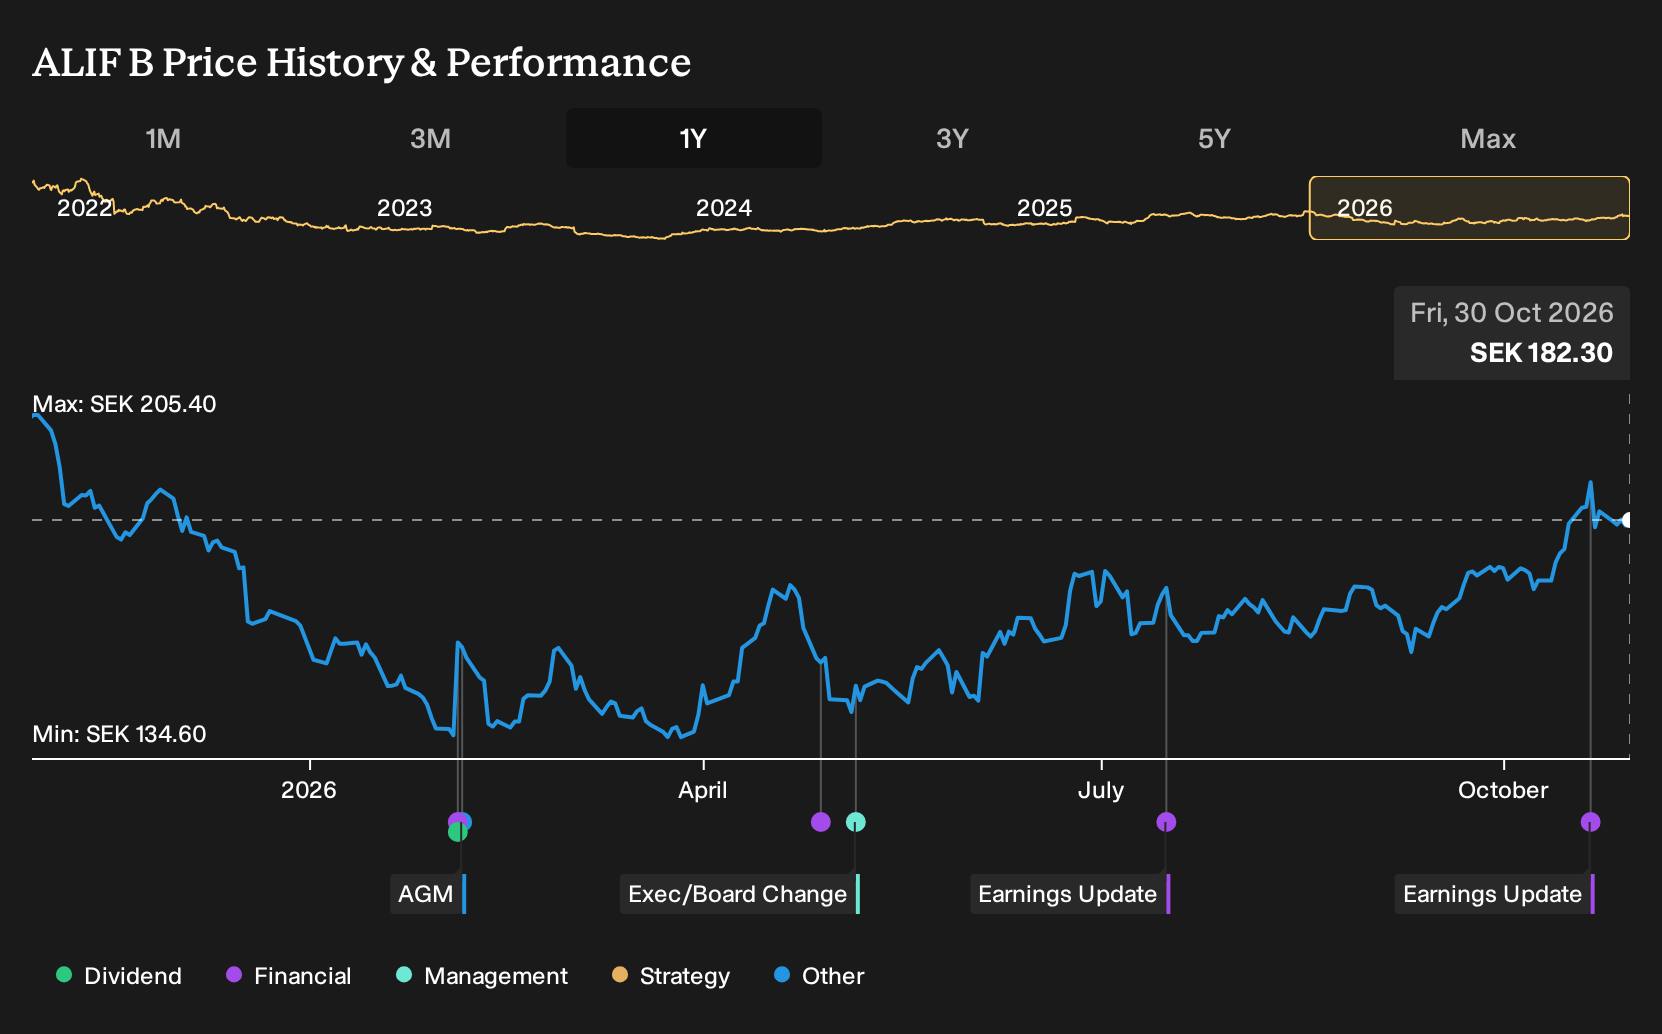
The third quarter and nine month 2026 earnings announcement is the clearest reference point right now. Sales reached SEK 2,599 million for the quarter and SEK 7,965 million for the nine month period, with net income at SEK 127 million and SEK 384 million respectively. Earnings per share from continuing operations also tracked higher than a year earlier.
For you, that result matters because it touches both sides of the thesis. It supports the idea that AddLife can grow while improving profit quality, yet it also comes with the reminder that working capital, integration of past deals and a relatively high debt load all need close watching if the acquisition pipeline and product refreshes are to remain a positive catalyst rather than a drag.
AddLife's narrative projects SEK 13.6b revenue and SEK 825.4 million earnings by 2029. This reflects a projection of 8.3% yearly revenue growth and an earnings increase of about SEK 181 million from SEK 644.0 million today.
Discover how AddLife's fair value indicates a 12% potential upside to its current price that may not remain available for long.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 204.75 and about SEK 227.95 per share, yet they still span a meaningful spread for AddLife. Those retail viewpoints sit beside clear execution risks around tenders, cash conversion and research demand, so you really benefit from weighing several contrasting angles before acting.
Explore 2 other AddLife fair value estimates, including one that suggests it could be worth just SEK204.75.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your AddLife research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AddLife. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AddLife's overall financial health at a glance.
Looking for more investment ideas beyond AddLife?
If you want to stress test your AddLife thesis against other opportunities, the Simply Wall St Screener can help you scan the wider market in a structured way.
- For investors who care about balance sheet strength and durable fundamentals, start with this curated list of solid balance sheet and fundamentals (199 results) to see which businesses pair financial resilience with quality metrics.
- If value is your priority, compare AddLife with a hand picked 200 high quality undervalued stocks that filters for companies combining strong fundamentals with prices that may not fully reflect them.
- Income focused readers can widen their watchlist by checking out a 224 dividend fortresses that screens for higher yielding stocks with the potential for more dependable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com