


EN
What Flagstar Bank's Return To Profit Means For Shareholders
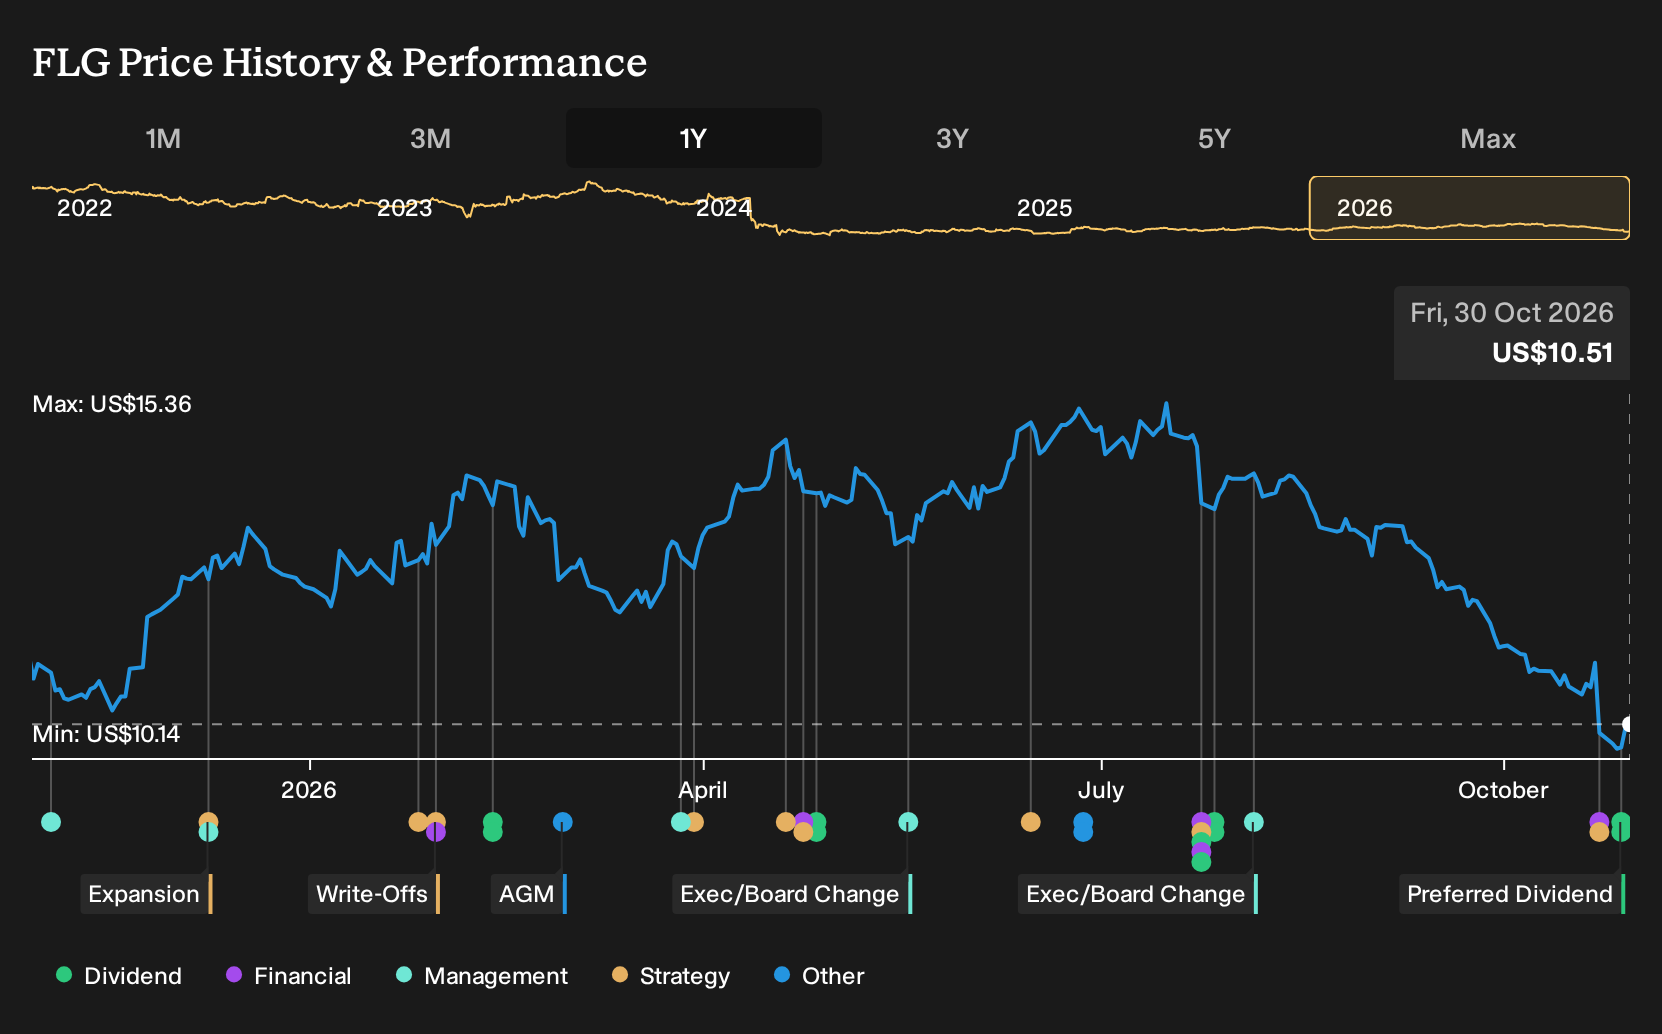
- Flagstar Bank National Association reported third quarter 2026 net income of US$12 million with net interest income of US$460 million, declared a US$0.01 common dividend, and approved quarterly payments across three preferred series, all scheduled for December 17, 2026 for holders of record on December 7, 2026.
- The bank also completed a US$250 million buyback covering 19,392,591 shares, which reduces the share count and makes each remaining share represent a larger claim on earnings and dividends.
- Investors are now watching how Flagstar Bank's profitability and the completed US$250 million repurchase program could influence its broader investment narrative.
Scan how Flagstar Bank National Association's latest dividend and buyback news compares with other hand picked banks and financials in list of solid balance sheet and fundamentals (24 results)
Flagstar Bank National Association Investment Narrative Recap
To own Flagstar Bank National Association, you need to be comfortable with a turnaround that is already showing profit but still carries credit and execution risk. The story hinges on management turning higher net interest income, tight cost control and balance sheet reshaping into steadier earnings. The latest quarter’s US$12 million profit helps that narrative, although the headline number is still modest.
The short term catalyst is continued proof that earnings from continuing operations can stay positive while credit metrics remain contained. Net charge offs of US$74 million and a low 31% allowance for bad loans keep asset quality as the biggest watchpoint. If recent results do not hold, the risk case quickly comes back into focus.
The US$250 million share repurchase, which retired 19,392,591 shares or 4.65% of the float, is the announcement that most directly ties into this earnings update. With that program completed in early October 2026, each remaining share now represents a larger claim on Flagstar Bank National Association’s current US$67 million year to date net income.
For you as a shareholder, the buyback only really matters if profitability, credit outcomes and net interest income trends stay on track. The combination of modest common dividends, ongoing preferred dividends and a reduced share count can support per share metrics. However, the key catalyst is still whether loan mix shifts and funding changes translate into durable returns while high bad loan levels are worked through.
Flagstar Bank National Association's current assumptions point to revenue of US$3.4b and earnings of US$1.1b by 2029, based on forecasts that use an 18.3% yearly revenue growth rate and an earnings increase of roughly US$1.1b from US$15.0m today.
Uncover how Flagstar Bank National Association's fair value indicates a 43% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value views on Flagstar Bank National Association from three Simply Wall St Community members span a wide range, from US$1.78 to US$15.06 per share, which shows how far apart retail estimates can be. Set that against ongoing credit costs, net charge offs of US$74 million, and the recent buyback and dividend decisions, and you are looking at a bank where opinions genuinely diverge. It can be useful to compare several of these viewpoints before forming your own stance.
Explore 2 other Flagstar Bank National Association fair value estimates, including one that suggests as much as 83% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Flagstar Bank National Association research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flagstar Bank National Association. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flagstar Bank National Association's overall financial health at a glance.
Looking For More Investment Ideas Beyond Flagstar Bank National Association?
If this Flagstar Bank National Association update has sharpened your thinking, use that momentum to size up a wider set of opportunities across different balance sheets, income profiles and payout approaches.
- If capital preservation is top of mind and you want businesses with sturdier finances, start with a curated 29 resilient stocks with low risk scores that aim to keep risk in check while you assess potential returns.
- When income is a key goal and you care about cash flow support for payouts, scan through 5 dividend fortresses that focus on higher yielding distributions backed by fundamentals.
- For readers hunting for under-the-radar potential, review a hand picked 19 high quality undiscovered gems that combine solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com