


EN
Japan Consumer Stocks for a Higher Rate Era
Japan’s inflation story is finally starting to look more settled, with the Bank of Japan talking more openly about 2% price stability and higher rates on the horizon. That mix of firmer wages, steadier prices and a less generous money tap could reshape which domestically focused stocks thrive. This article walks through three Japan Domestic Consumption stocks exposed to that shift, and why they deserve a closer look now.
The three stocks below are just a starting sample, since the full screen surfaced 17 more Japanese domestic consumption companies with equally compelling stories that are not covered here.
If you want to go straight to the data and identify which tickers best fit your own thesis, analyze the Japan Domestic Consumption Stocks screener.
Takashimaya Company (TSE:8233)
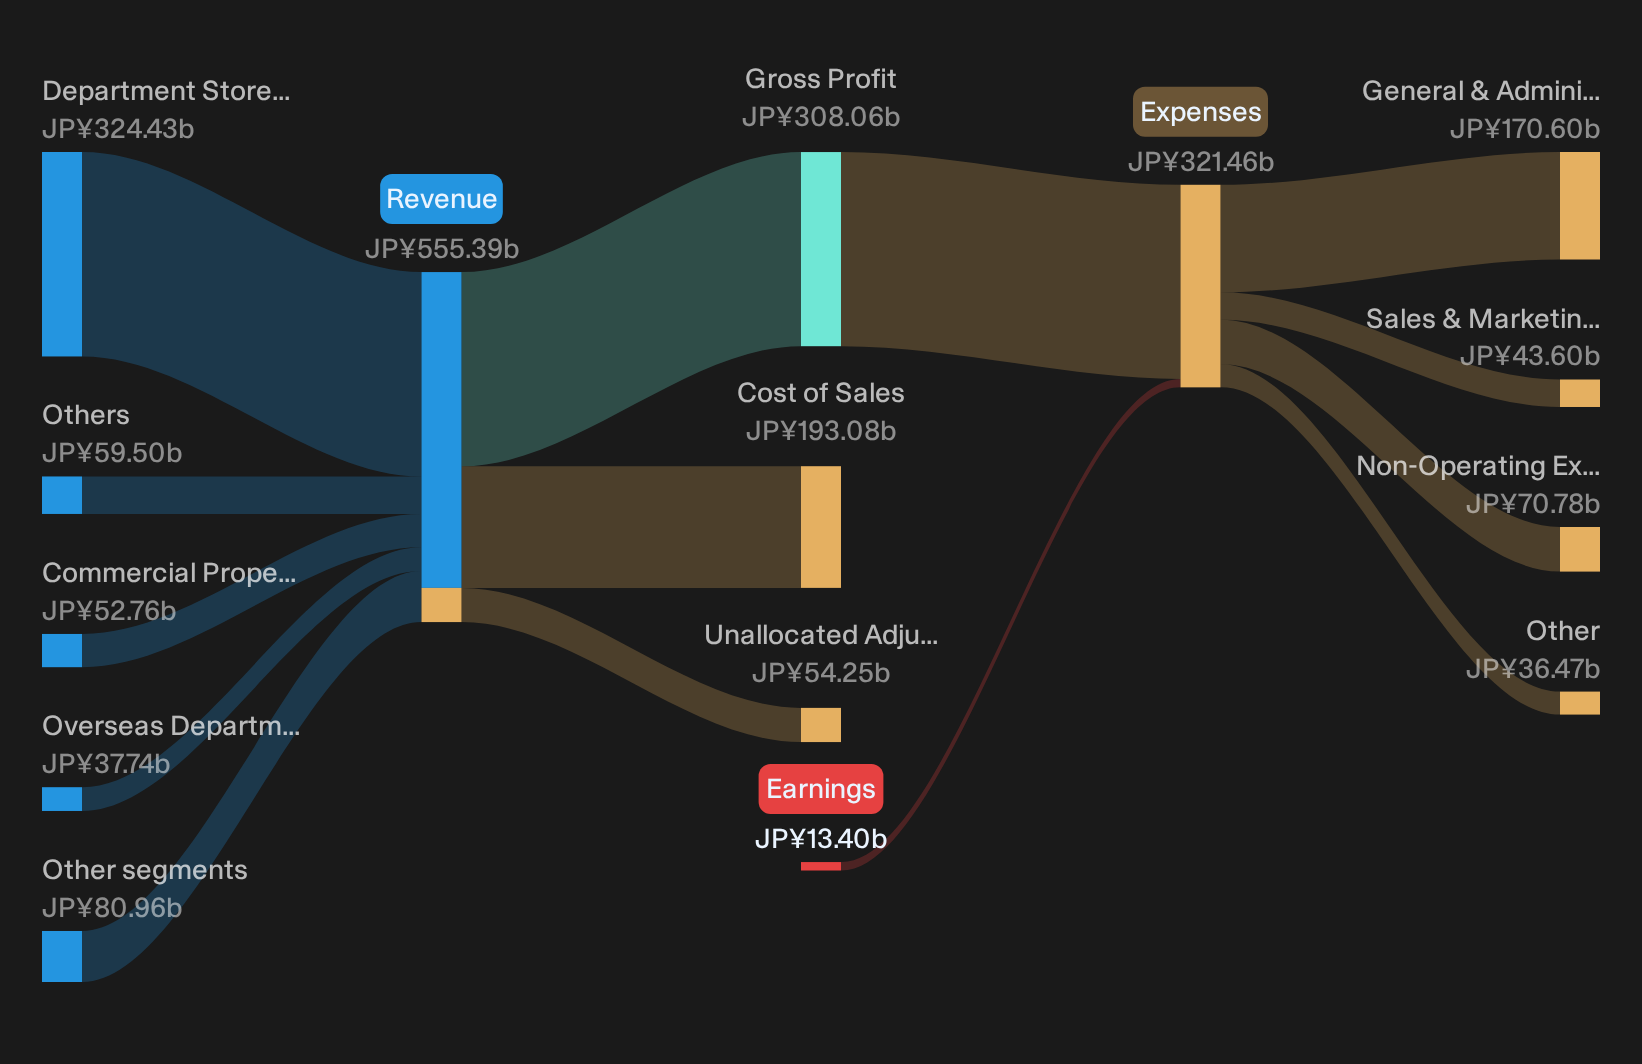
Takashimaya Company is a long established Japanese department store and commercial development group tied closely to domestic in store retail and services, with Japanese department stores generating about ¥324.4b of revenue and overseas stores and property projects adding roughly ¥55.3b. Other segments, including construction, finance and commercial property in Japan, contribute tens of billions of yen. The stock’s market value is about ¥632.2b.
Takashimaya Company gives you direct exposure to Japan’s consumer wallet through department stores, restaurants and property projects that depend on local spending, at a time when the Bank of Japan is talking about firmer wages and steadier inflation. The appeal of that link to everyday domestic demand hinges on what happens when a single pressure point on profitability and funding costs shifts.
When that kind of turning point is in play, run through the 1 key reward and 1 important warning sign to see what may quietly tilt Takashimaya Company’s risk reward balance next.
ZOZO (TSE:3092)
ZOZO runs a Japan focused online fashion mall that sits squarely in domestic consumer spending, giving investors direct exposure to how local shoppers shift more of their apparel and lifestyle budgets online as wages, prices and household confidence move.
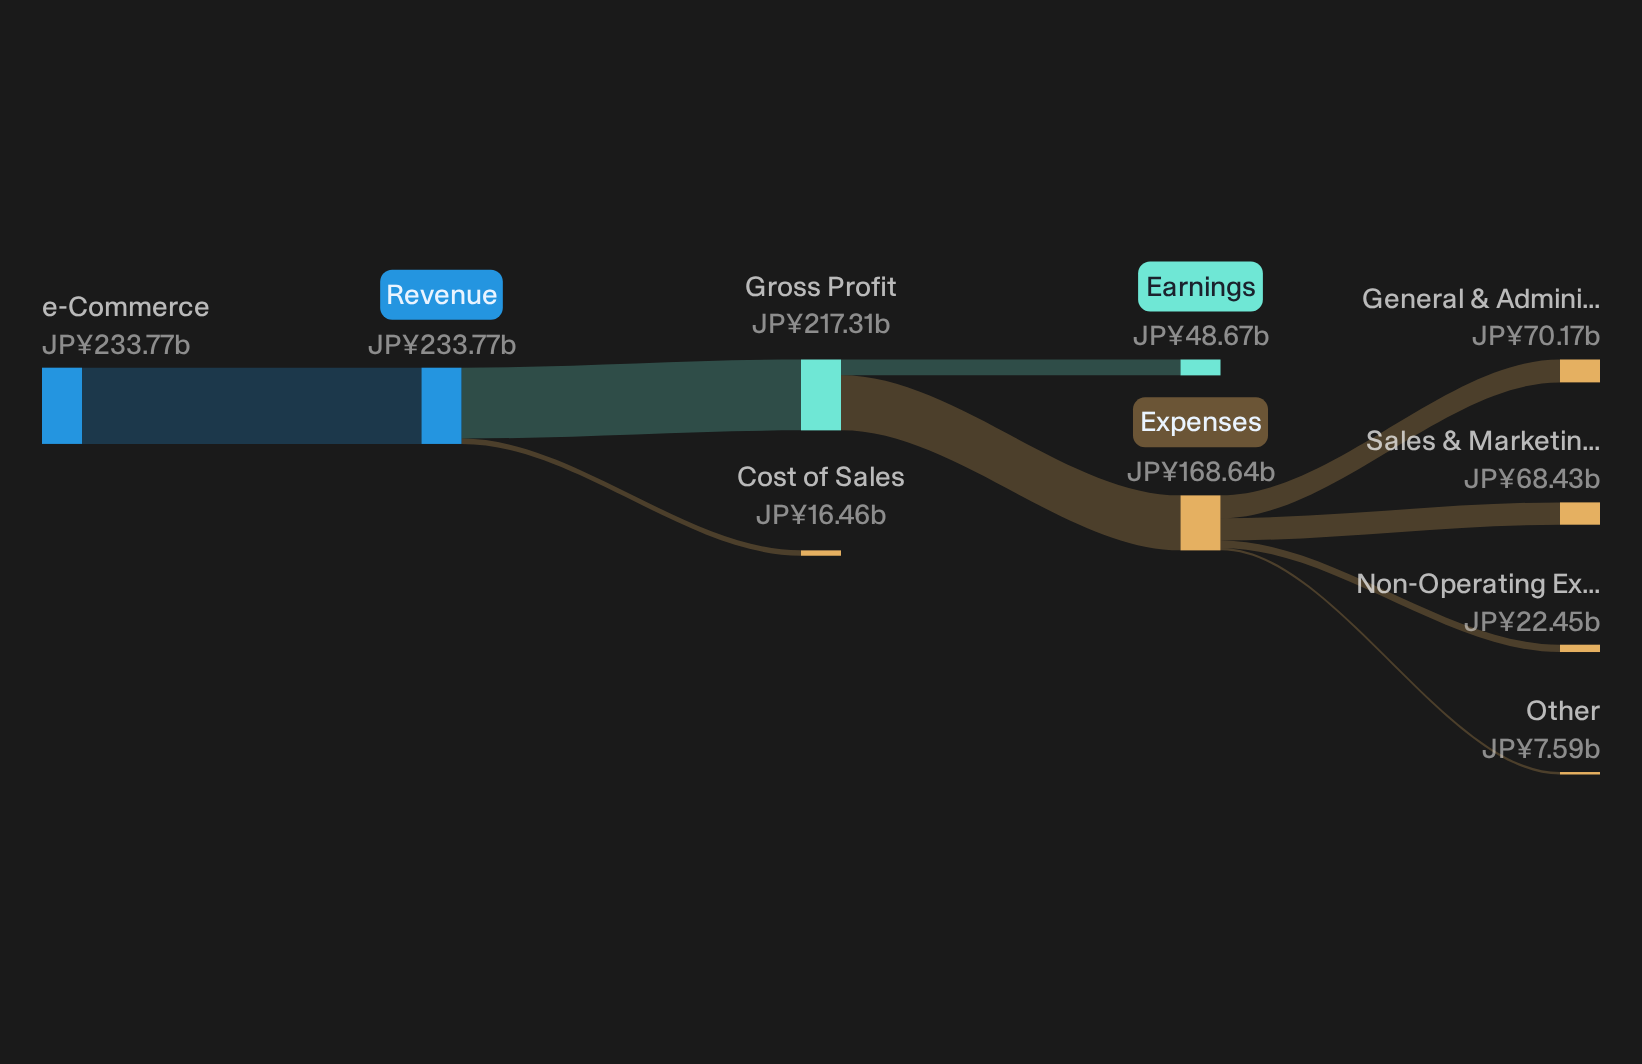
ZOZO generates all of its ¥233.8b in revenue from e commerce in Japan, through platforms like ZOZOTOWN and related services, and the stock carries a market value of about ¥1,007.9b.
That mix of scale in Japanese online fashion and heavy ties to local discretionary spending is the reason this stock features in the Japan Domestic Consumption screen, particularly as e commerce habits become more established and the macro backdrop for household budgets changes.
"Further logistics automation and the planned new logistics center from FY2028 build on recent reductions in packing, shipping and personnel costs, which can support SG&A efficiency and help protect operating margins."
Any change in a single pressure point on consumer pricing and promotional intensity is likely to have a significant impact on where those margins eventually settle.
That margin question is only the start, because the full narrative for ZOZO shows how ZOZO’s logistics shift, pricing power and platform effects could accelerate or stall from this point.
Asahi (TSE:3333)
Asahi Co., Ltd. runs Cycle Base Asahi stores and online shops across Japan, selling bicycles, parts, accessories and maintenance services that tie directly to domestic leisure and mobility spending. The stock’s market value is about ¥32.8b.
Asahi offers exposure to Japan’s everyday consumer spending, since bicycles and related services are discretionary purchases that tend to reflect real income, leisure time and commuting patterns. Forecast earnings growth is set against thin 2.2% margins and higher borrowing, so any change in pressures on profitability can have a meaningful impact on this retailer.
With those thin margins and higher borrowing in mind, review the Asahi financial health report to see where Asahi’s balance sheet pressure could start to ease or accelerate.

Seeking Fresh Alternatives Beyond These Picks?
The best breakout ideas rarely stay quiet for long. Momentum can be caught early or missed completely once prices start flying. Scan these fresh lists before the crowd and consider your options.
- Identify strong cash generators before they gain wider attention by running the 15 high quality undervalued stocks while valuations and expectations still appear under the radar.
- Monitor companies involved in the infrastructure backbone of AI and data centers through the 42 power grid technology and infrastructure stocks so you are not reacting only after significant capital has moved.
- Review opportunities tied to demand for electrification and construction materials by scanning the 16 top copper producer stocks before changes in sentiment affect quality operators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com