


EN
Surgery Partners (SGRY) Is Getting Attention, What Is The Market Weighing?
Deal terms and immediate takeaways for Surgery Partners investors
HealthSpan Partners has agreed to acquire 61.24% of Surgery Partners (SGRY) in an all cash deal that values the business at about US$5.7b, with minority shareholders offered US$23.50 per share.
The agreement keeps Bain Capital invested through rolled equity, while setting up Surgery Partners to leave public markets and continue operating under its existing brand, headquarters and secular governance framework.
Surgery Partners has swung sharply higher in recent weeks, with a 74.25% 1 month share price return and a 52.10% year to date gain. However, the 5 year total shareholder return is down 53.67%, which shows momentum has only recently turned after a long stretch of weaker performance.
Scan how this buyout premium compares with other potential take-private stories by reviewing our hand picked 19 high quality undiscovered gems in similar corners of the market.
The jump in Surgery Partners shares now sits between two stories. Either investors are finally re-rating the underlying surgery network, or the take private offer and changing sentiment are doing the heavy lifting. How rich does that US$23.50 look on the fundamentals?
Most Popular Narrative: 9% Overvalued
Surgery Partners last closed at $23.21, which sits above the most followed fair value estimate of $21.20 that applies an 8.63% discount rate. That gap puts more weight on how realistic the long term earnings and margin assumptions really look under the new buyout backdrop.
The accelerated migration of high-acuity surgical procedures (particularly orthopedics and joint replacements) from hospitals to outpatient settings is strengthening, with Surgery Partners demonstrating outperformance through investments in robotics and facility capabilities, positioning the company to capitalize on expanding case volumes and higher-revenue procedures. This directly supports the narrative for long-term revenue and EBITDA growth.
See why 5 investors see Surgery Partners as 9% overvalued.
Result: Fair Value of $21.20 (OVERVALUED)
Still, rising interest costs and slower acquisition deployment could pressure Surgery Partners, especially if divestitures or minority stakes dilute revenue and unsettle the current earnings path.
Find out about the key risks to this Surgery Partners narrative.
Another view on Surgery Partners valuation
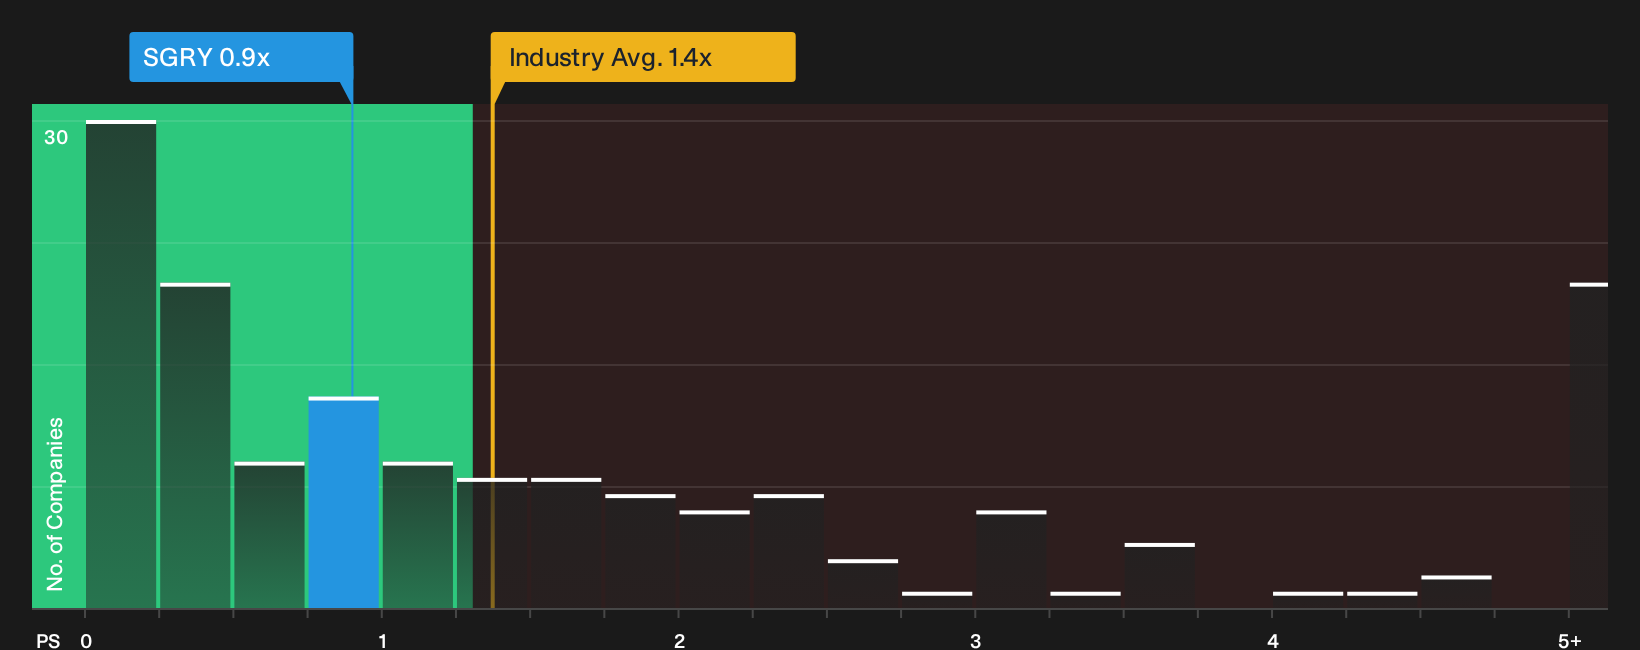
While the analyst narrative tags Surgery Partners as about 9% overvalued on a fair value of $21.20, the market is telling a more mixed story. The stock trades on a P/S ratio of 0.9x, compared with 1.4x for the wider US Healthcare group and 1.5x for peers. However, the fair ratio sits at just 0.4x. That gap points to a price that screens cheap against the sector but still rich versus where the fair ratio suggests the multiple could drift over time. The question is which reference point should be treated as the anchor.
For a deeper breakdown of how this pricing stacks up against fundamentals, run through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Surgery Partners has clearly shifted, and that mix of concerns and optimism makes this a moment to act before the story moves again. Start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Surgery Partners?
Do not stop at Surgery Partners. Fresh ideas often come from scanning outside the obvious tickers, and missing that next candidate can cost real upside.
- Target higher potential upside by scanning concentrated opportunities through the 8 elite penny stocks with strong financials that already pass strict financial filters.
- Prioritise value by reviewing the 33 high quality undervalued stocks that pair strong fundamentals with prices that still look restrained.
- Protect your downside by focusing on balance sheet strength using our list of solid balance sheet and fundamentals (24 results) that filters for resilient businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com