


EN
What Interroll Investors Missed Before The Fall
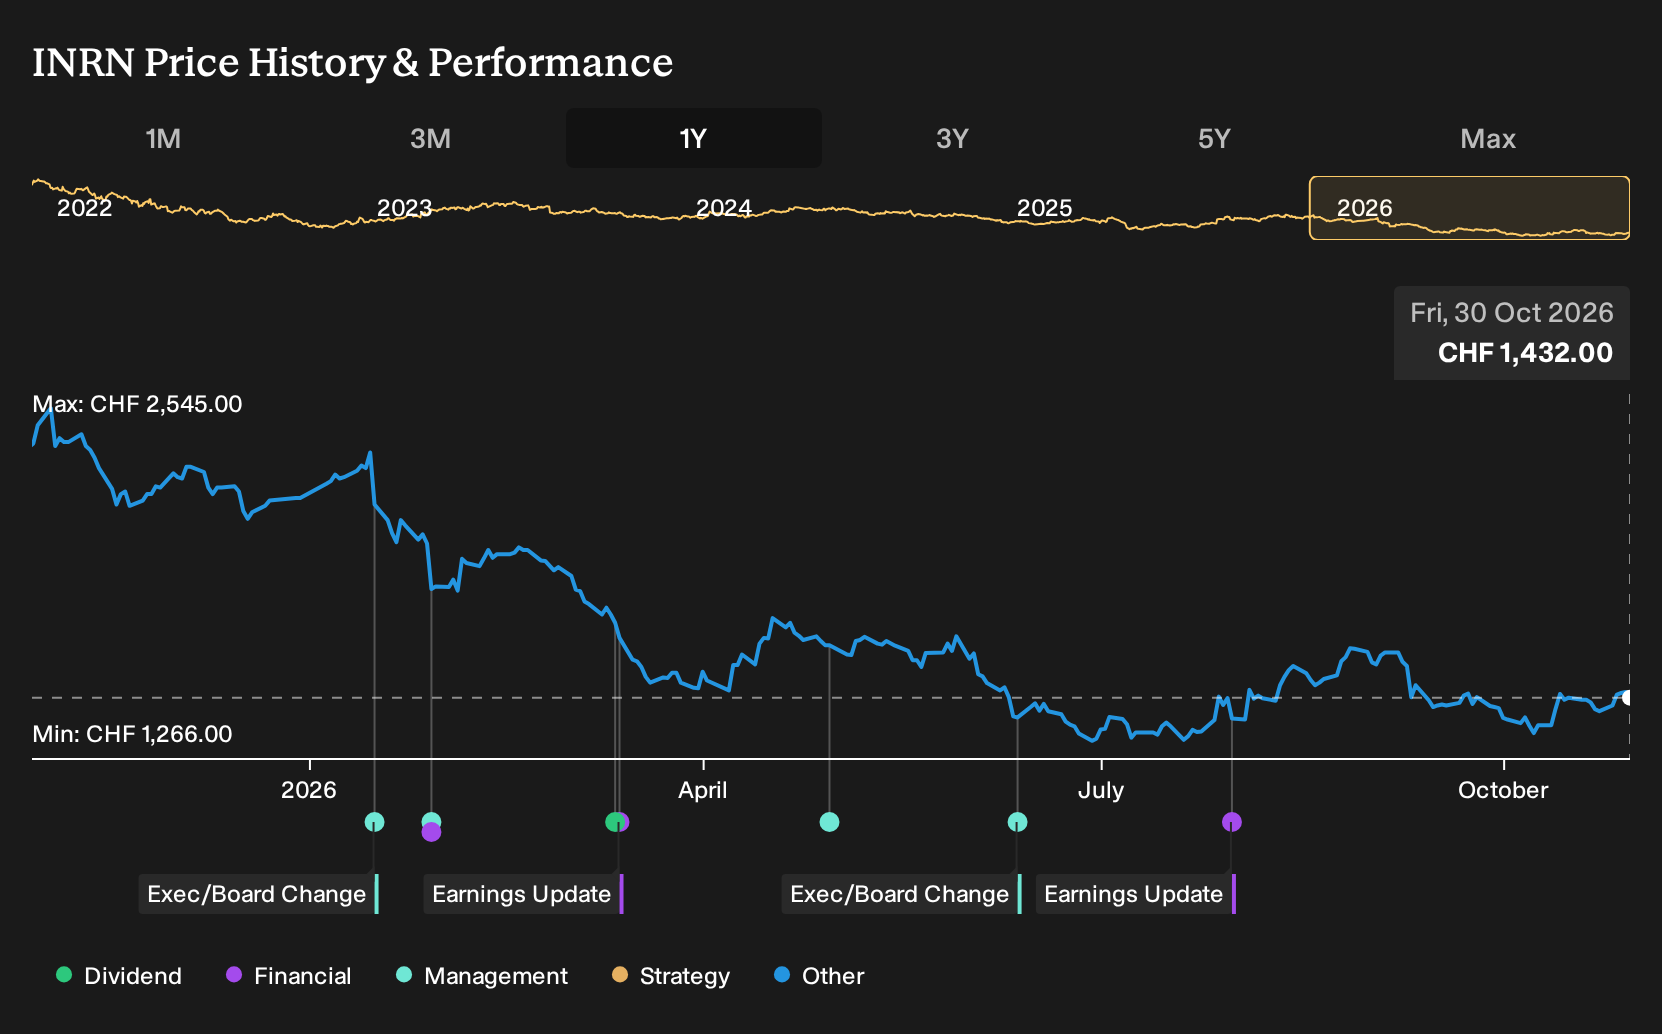
Interroll has been busy, buying Royal Apollo Group to add spiral conveyor technology and then taking over its Nordic distributor to tighten control of the region. Investors who held Interroll over the past year are down 42.4%, including dividends. If you had bought on 30 October 2025, those deals and the later report showing higher revenue but a thinner net margin frame a sharper question: What result were you really signing up for?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Interroll is not the only name tied to this theme. Zero in on 94 robotics and automation stocks and compare how each one is priced.
The Two Interroll Stories Investors Had To Weigh
The shares cost CHF2,410 at the start of the period, and anyone looking at Interroll then had to choose which story felt more realistic.
On the optimistic side, the bullish Narrative set Fair Value at CHF2,695 and assumed that organizational restructuring and aggressive localization would lift customer relevance and margins faster than consensus expected.
The bearish view put Fair Value at CHF2,042 and focused on the risk that rising protectionism and Chinese competitors would pressure Interroll's revenue and profitability over time.
What The Results Changed For Interroll
Interroll’s acquisitions of Royal Apollo and its Nordic distributor supported the optimistic view of filling product gaps and tightening regional control. The results told a cooler story. Total revenue rose from CHF247.654m in H1 2025 to CHF269.928m in H1 2026, while net income slipped and net margin moved from 8.6% to 7.3%. The evidence pointed in both directions.
The central assumption was that higher relevance and scale would support stronger profitability. For a different stock with a similar pitch, track whether net income and margin move in the same direction as any expansion push, not just whether sales grow.
What Interroll’s Drop Leaves You To Judge Today
Interroll trades at CHF1,432 after falling 42.4% over the past year. The selected bullish Narrative sees Fair Value above that price and ties the gap to how well the group uses its larger footprint, higher R&D and sales spend, and added product scope.
A buyer today would be assuming that recent acquisitions and existing plant capacity translate into sustained order growth that supports healthier EBIT margins.
"The main factor that has to go right is that Interroll Holding converts its available plant capacity, recent acquisitions and higher spending on innovation and market development into profitable volume growth that supports EBIT margin quality after acquisition-related and one-off tax effects."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 37% below our estimate - uses labour reform tailwinds and tech-enabled contracts to lift security and facility service earnings.
- Company 2 - 23% below our estimate - leans on a swelling hyperscale data center backlog to drive installation and infrastructure work.
- Company 3 - 34% below our estimate - converts a large residential land bank into higher margin projects despite tighter buyer credit.
Three companies from the same screener. Open the full list of 196 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com