


EN
UK Stock Market Today: FTSE 100 Futures Edge Higher On Firmer Eurozone Growth Data
The Morning Bull - UK Market Morning Update Monday, 2 Nov 2026
UK stocks are set for a slightly firmer open, with FTSE 100 futures edging up in early trade. The single big driver is Eurozone growth coming in a touch better than expected, which is supporting risk appetite after a weak global equity session.
Euro area GDP rose 0.4% quarter on quarter in Q3 2026, with annual growth at 1.3%. Germany posted 0.2% quarterly growth while France slipped 0.1%. That mix points to a regional economy that is sluggish but still generating demand relevant for UK exporters and funding markets.
Stronger Eurozone activity can keep euro area inflation pressures from easing quickly, which matters for expectations around European and UK rates. If investors see firmer growth alongside oil above US$100 a barrel, they tend to price a higher-for-longer path for borrowing costs that affects valuations and discount rates for UK earnings.
The open question is whether this growth resilience forces the Bank of England to lean more hawkish around the 4% consensus for Thursday’s decision. Incoming Eurozone inflation on Wednesday now looks like the key test of whether today’s slightly positive tone holds.
Stocks to Watch Before the Opening Bell
AstraZeneca (AZN)
AstraZeneca is in focus after Europe accepted its Marketing Authorisation Application for ORPATHYS plus TAGRISSO in MET driven, EGFR mutated non small cell lung cancer. Japan has also taken the combination filing, supported by Phase III SAFFRON data showing improved progression free and overall survival.
Regulators in the US already received a new drug application in September 2026. Attention now sits on review timelines across the three regions and the potential pace of any expansion of this therapy within AstraZeneca’s oncology franchise if approvals follow.
Anglo American (AAL)
A new report on a global resource squeeze highlights tighter conditions for energy, metals and agriculture, with Chilean copper production under pressure and central banks buying more gold. That backdrop directly affects diversified miners such as Anglo American that are exposed to copper and precious metals.
Former chief executive Mark Cutifani also warned that slow progress on technology and permitting could leave large producers more exposed to takeover interest. Investors will be watching how Anglo American positions its projects and capital spending in light of these long lead time risks.
Ninety One Group (N91)
Ninety One Group is in the spotlight after publishing a report arguing that commodity markets are shifting from a China led boom to a phase driven by constrained supply and geopolitical fragmentation. The study flags rising electricity demand from AI and data centres as a fresh source of pressure for power and metals.
For readers tracking asset managers, this kind of thematic work can shape how Ninety One Group allocates client capital across resources, energy and related equities. The next factor to monitor is whether future product launches or fund positioning reflect these supply focused views.
Top Movers
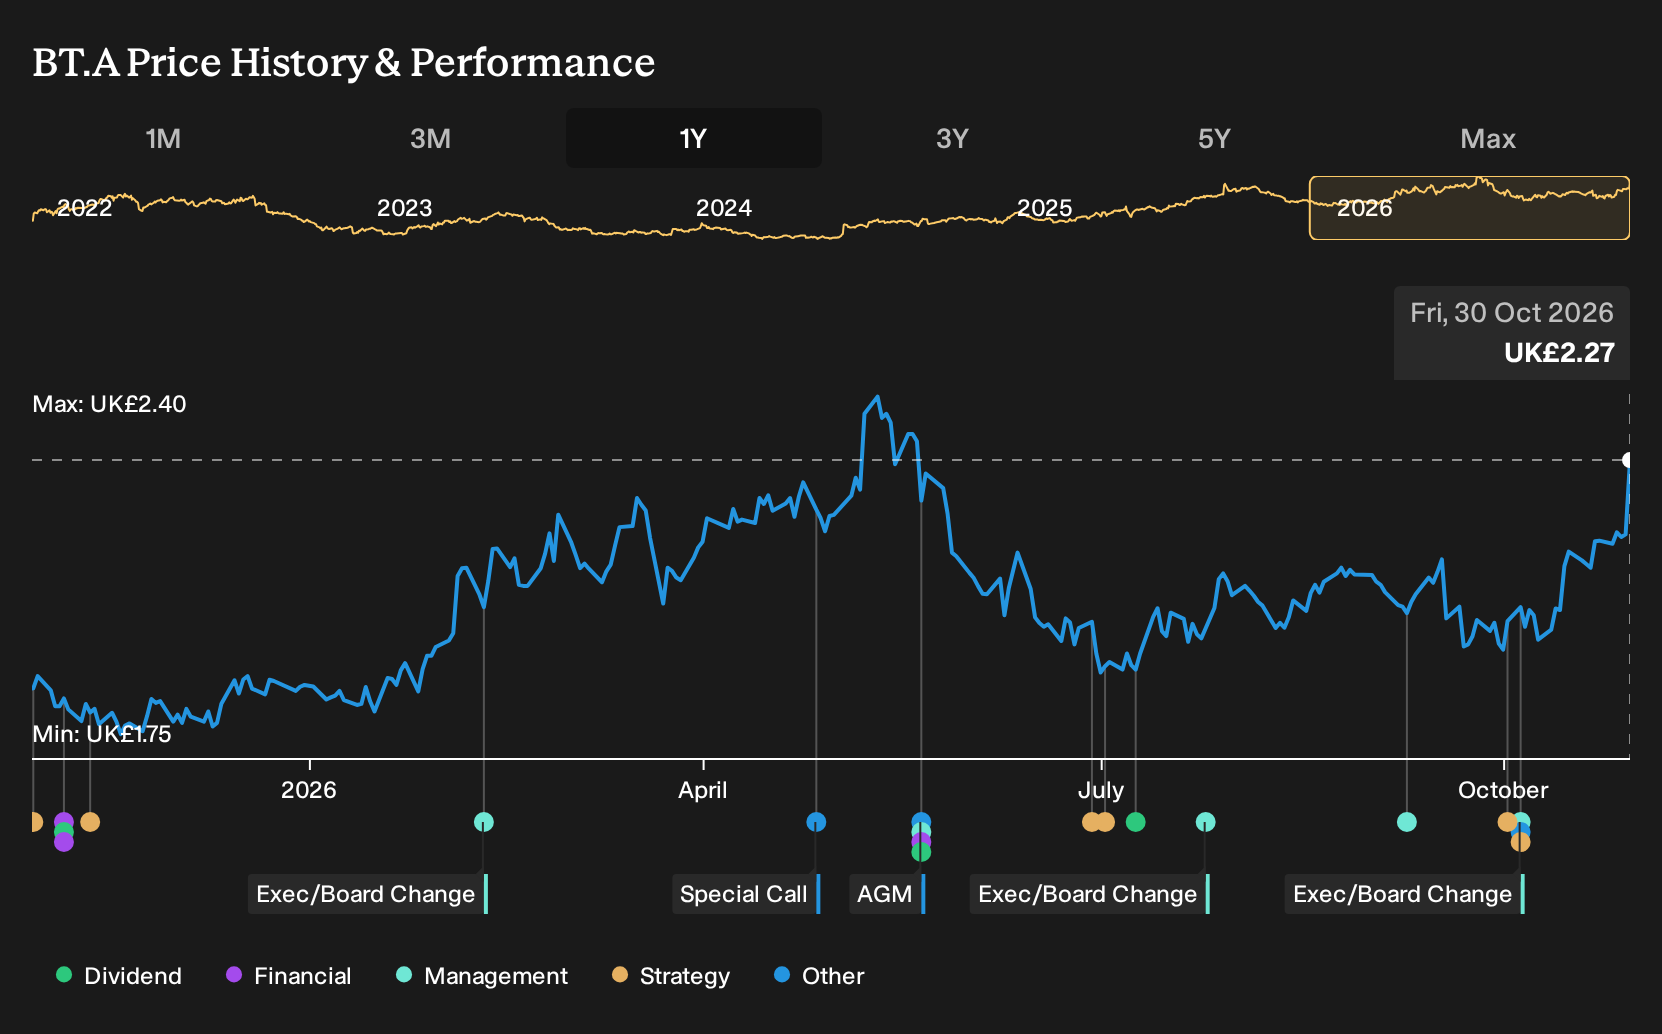
- BT Group (LSE:BT.A) jumped 6.71% after reports that Virgin Media O2 may use its fibre network and following solid quarterly results.
- Seplat Energy (LSE:SEPL) gained 4.84% after reporting Q3 and nine-month earnings and after Citi raised its price target.
- Diageo (LSE:DGE) added 3.26% in line with resilient FTSE 100 trading and recent branded product launches.
Top Losers
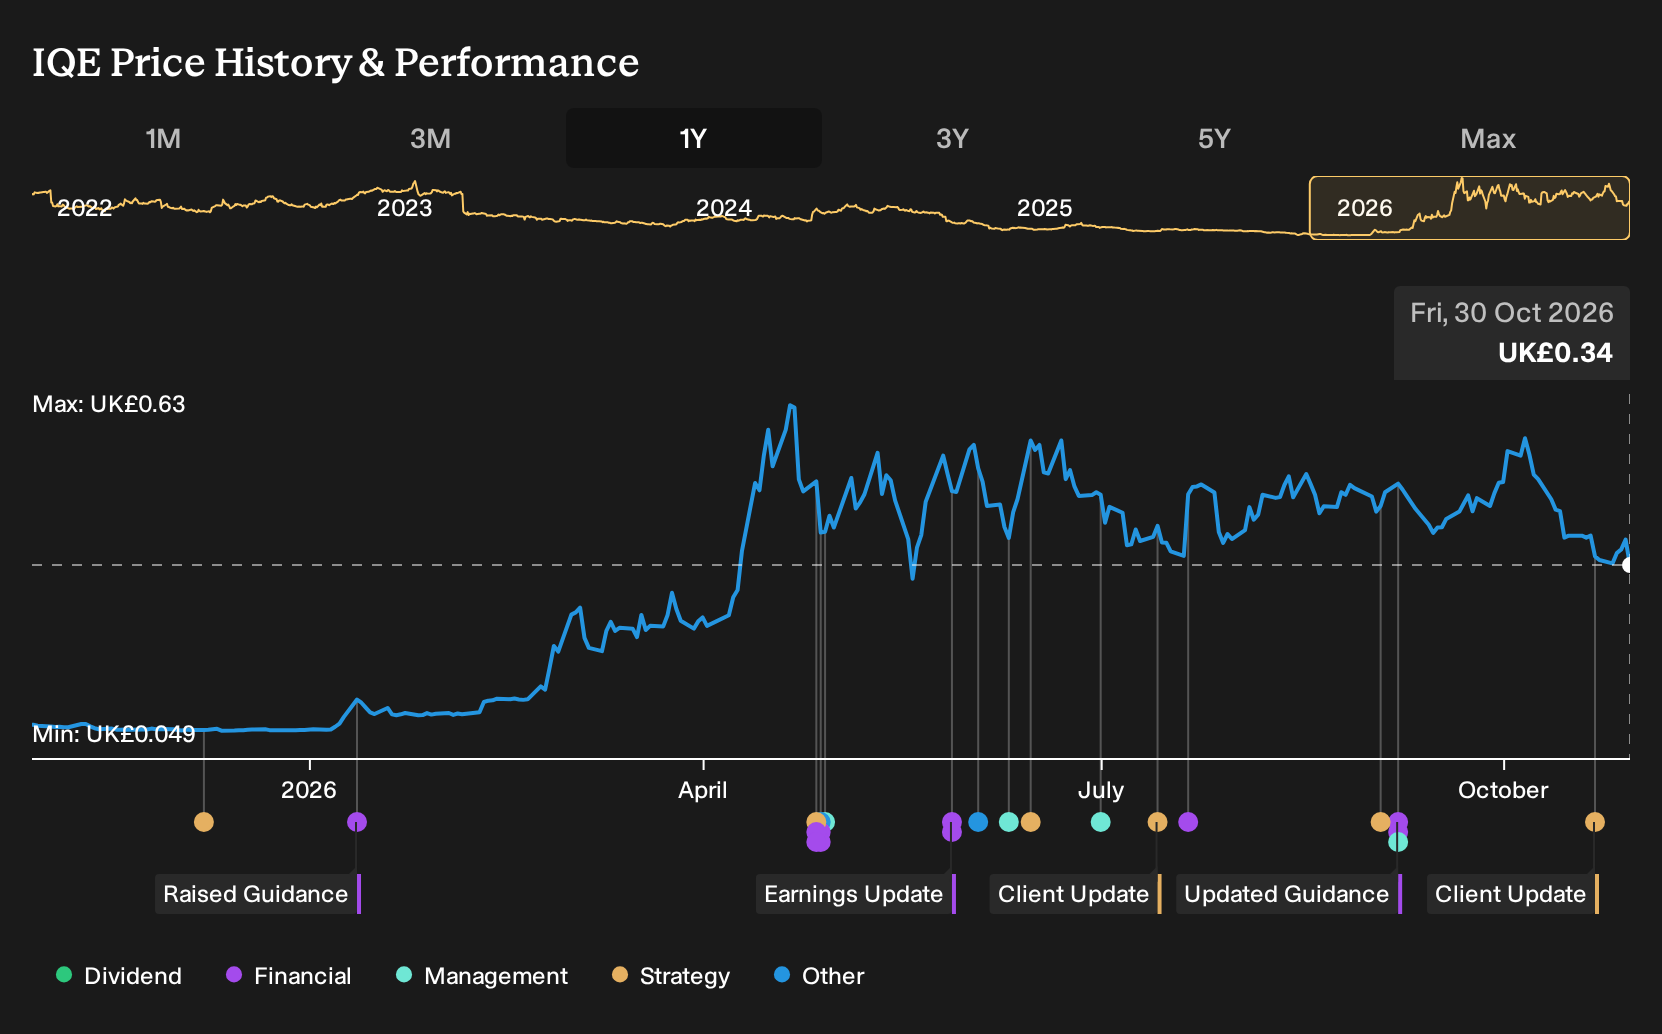
- IQE (AIM:IQE) declined 11.67%.
- Ecora Royalties (LSE:ECOR) declined 9.91%.
- NatWest Group (LSE:NWG) fell 8.75% after Q3 results and guidance raised questions over future net interest income trends.
On The Radar
UK trading over the next few sessions revolves around the Bank of England rate call and a dense run of FTSE 100 earnings that hit everything from telecoms to consumer brands and infrastructure.
- Bank of England Interest Rate Decision, Thu 5 Nov. The move from 3.75% to the 4% consensus, or any surprise around it, feeds directly into UK borrowing costs, gilt yields and the pressure on house prices and domestically focused shares.
- BT Group, Thu 5 Nov. Q2 2027 figures at 7:00 AM focus attention on Openreach fibre rollout economics and group cash flow, which matter for how comfortably BT can handle its debt load in a higher rate setting.
- Marks and Spencer Group, Wed 4 Nov. First half 2027 results put the spotlight on clothing and food margins as UK consumers juggle energy and mortgage bills, a key signal for discretionary spending resilience on the high street.
- National Grid, Thu 5 Nov. First half 2027 numbers will highlight regulated asset returns and capex on UK networks, shaping how investors think about inflation linked revenues versus higher funding costs for this core infrastructure utility.
- Associated British Foods, Tue 3 Nov. Full year 2026 results at 7:00 AM bring Primark trading and food division profitability into focus, which helps gauge how UK retailers and consumer staples are coping with wage pressures and input costs.
Sector & Industry Watch
Financials: Banks under pressure before BoE
Financials have slipped over the past week, with Banks weaker than the wider group as investors weigh loan demand, funding costs and future bad debts. The sector still shows a gain over the last year, although recent earnings growth has been modest and valuations for many lenders cluster around their usual P/E range.
If you hold UK bank heavy funds, the single pivot is Thursday’s Bank of England interest rate decision and vote split, because that steers expectations for mortgage margins and what lenders may feel comfortable returning through dividends.
Energy: Oil and Gas linked to £ at pump
Energy and Oil and Gas have moved broadly sideways over the last seven days after a strong 12 month advance of around 40%. Higher crude prices above US$100 a barrel and talk of a tighter global resource backdrop keep attention on how much spare cash UK listed producers can generate for balance sheets and payouts.
If you own Energy stocks, the key trigger to watch this week is US crude and gasoline inventory data, since any abrupt move in oil prices tends to show up both in your fuel bill and in earnings for London listed producers.
Metals and Mining: Resource squeeze meets softer shares
Metals and Mining have eased back over the past week and month even though the industry still shows gains of a little over 20% over 12 months. Reports around Anglo American and Chilean output highlight how securing copper and gold supply is getting harder while investor appetite for the sector has cooled recently.
If mining companies feature in your portfolio, focus on Wednesday’s euro area inflation flash reading, because any change in price pressures can shift expectations for regional demand that affects metals prices and the revenue outlook for UK listed miners.
Real Estate: Property rebound faces rate reality check
Real Estate has climbed over the last week and month, with a roughly 1.5% gain over seven days adding to a 4.7% rise over the year. The move comes after a weaker longer run for sector earnings, so the current bounce leaves a question mark over how higher borrowing costs might cap further progress.
If you hold property companies or REITs, the combination to watch is Thursday’s UK Construction PMI alongside the Bank of England decision, because construction activity and the cost of debt together feed into values for offices, warehouses and housing linked assets.
Healthcare: AstraZeneca news keeps pharma in focus
Healthcare has pushed higher over the past week, with Pharmaceuticals & Biotech outpacing the wider sector as AstraZeneca’s lung cancer filing news supports sentiment. Both groups show one year gains in the mid single digits and trade on P/E multiples around the low 20s, slightly below their three year averages, which reflects steady historic earnings growth.
If healthcare holdings sit in your ISA or pension, the most relevant driver to track is company pipeline news such as AstraZeneca’s regulatory progress, since trial results and approval milestones often move share prices more than broad economic data.
Don't Wait For The Winners, Find Them
With UK financials under pressure ahead of the Bank of England decision, it may be useful to stress test your holdings against higher borrowing costs using this list of 217 resilient stocks with low risk scores
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com