


EN
Did Weaker Quarterly Earnings Just Shift Ares Management (ARES) Stock Narrative?
- Ares Management reported Q3 2026 revenue of US$1,433.4 million and net income of US$85.33 million, both lower than a year earlier, while maintaining quarterly common and preferred dividends payable at year end 2026 and early 2027.
- The new European logistics partnership with Norges Bank Investment Management, backed by a €1.5b equity commitment, relies on Ares Management’s Marq Logistics platform, which oversees more than 2,250 properties and 655 million square feet globally.
- This article examines how Ares Management’s investment narrative is influenced by weaker quarterly earnings alongside ongoing dividend commitments.
Scan how other asset managers with strong balance sheets and consistent cash generation are positioned right now by reviewing the curated list of solid balance sheet and fundamentals (24 results) alongside Ares Management’s latest results.
Ares Management Investment Narrative Recap
A shareholder in Ares Management needs to be comfortable with an earnings profile that can swing with investment performance, while fee related revenue and fundraising remain central. The Q3 2026 report showed softer revenue and net income alongside steady fee margins in the low 40% range and higher general and administrative costs, which keeps cost discipline in focus.
The key near term catalyst is Ares Management’s ability to convert its large pool of committed capital into fee paying assets without further squeezing margins. The biggest current risk is that weaker profitability and wealth channel pressures coincide with elevated dividends and debt that are not well covered by operating cash flows.
The new European logistics partnership with Norges Bank Investment Management looks most relevant here. It builds on Ares Management’s Marq Logistics platform across more than 2,250 properties and 655 million square feet. This gives the firm another avenue to scale real assets fees if deployment keeps pace with commitments.
For readers, this alliance sits alongside record recent fundraising as a practical test of Ares Management’s execution. Successful deal sourcing and rent collection in European warehouses could support fee related earnings, while any slowdown in logistics demand or operational issues would feed directly into the same margin and dividend coverage concerns highlighted by the Q3 2026 results.
Ares Management Analyst Expectations Through 2029
Ares Management's forecasts hinge on a relatively brisk expansion path. Analysts are assuming revenue will grow by 10.2% per year over the next few years, with profit margins moving from 9.3% today to 28.5% by 2029. On the bottom line, consensus points to earnings of US$2.0b in 2029, compared with earnings today of US$487.4m. That implies an earnings increase of about US$1.5b across the period, which would need to be supported by both higher fee income and wider margins. Based on these projections, analysts also pencil in share count growth of 3.22% a year as the business continues to raise capital and issue equity linked awards.
Ares Management's narrative projects US$7.0b revenue and US$2.0b earnings by 2029. This setup requires 10.2% yearly revenue growth and an earnings increase of about US$1.5b from US$487.4m.
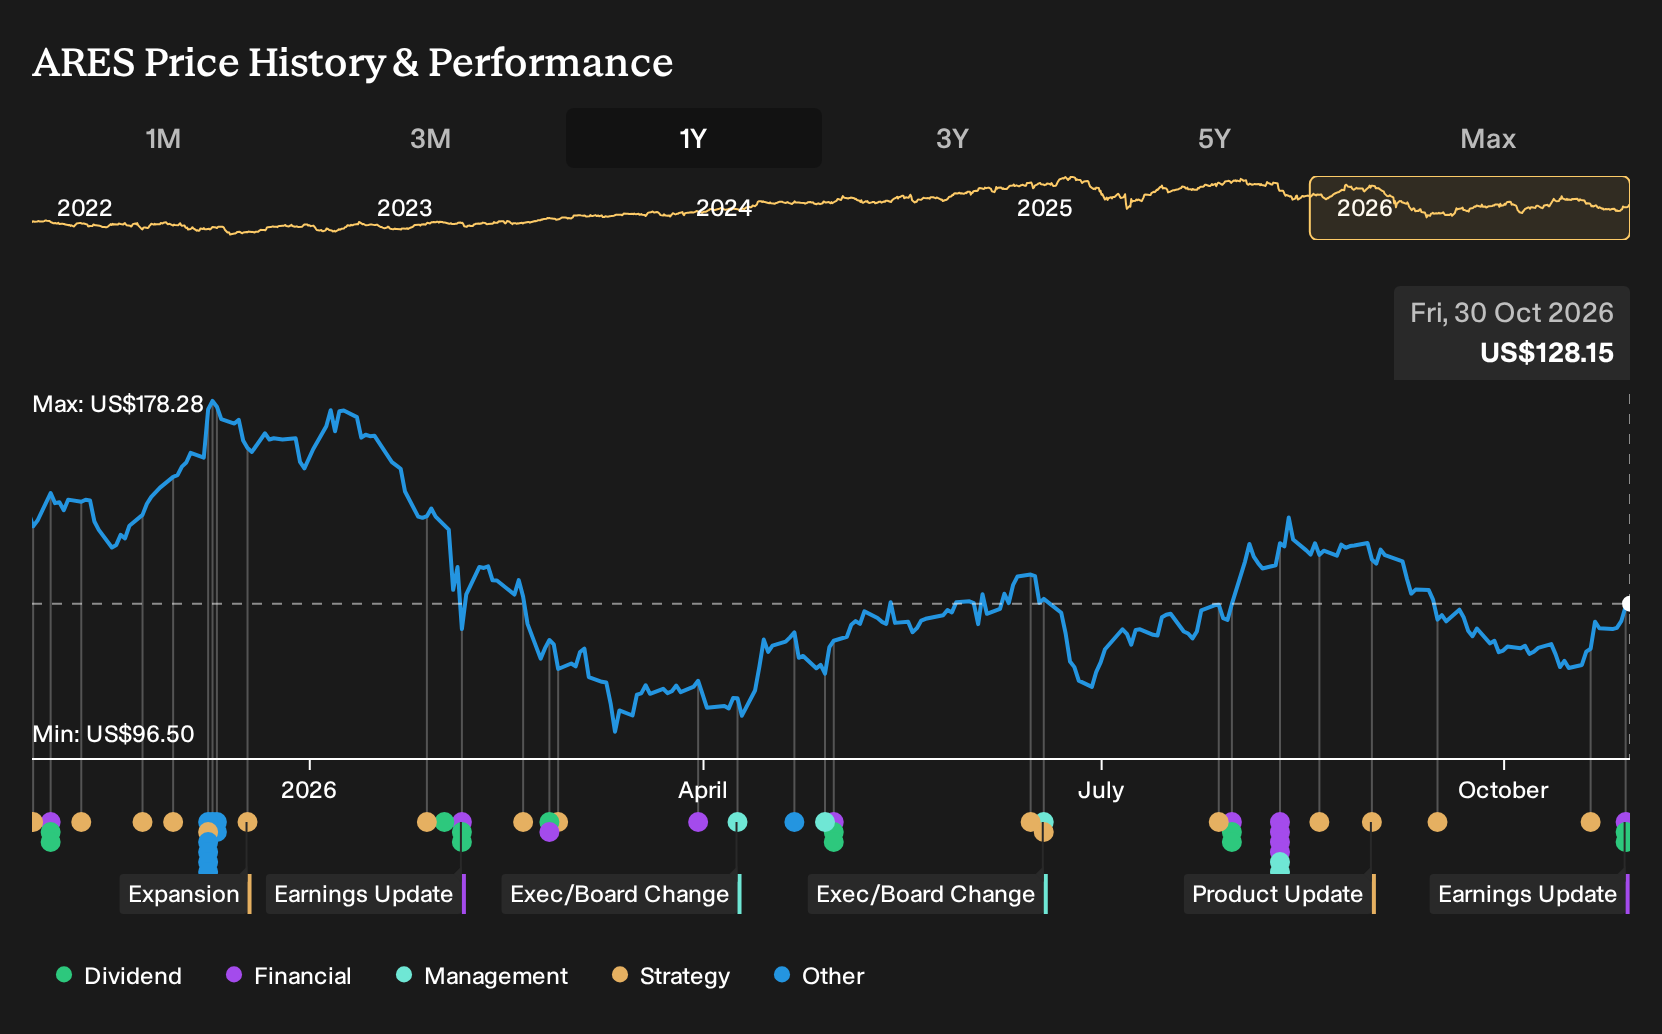
These assumptions feed directly into how the stock is being framed today. The analyst group cites a consensus price target of US$144.8, compared with a current share price of US$113.0 as of the latest report, with individual targets spread between US$119.0 and US$168.0. Underpinning that view is an implied 2029 P/E of 23.3x on the US$2.0b earnings estimate, compared with 52.7x today and a current US capital markets industry multiple of 38.1x. For readers, the key question is not whether those exact figures are right, but whether the path to US$7.0b of revenue and much higher profitability feels realistic given Ares Management's fund pipeline, logistics and data center projects, and the Q3 2026 pressure points around wealth channel flows and costs.
Uncover why Ares Management's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the new Ares Management and Norges partnership as the key catalyst, since their pre news models already assumed revenue of about US$7.2b and earnings near US$2.7b by 2029. That is far more upbeat than consensus, so you should expect opinions and forecasts to shift as this news beds in.
Explore 2 other Ares Management fair value estimates, including one that suggests as much as 31% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ares Management research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ares Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ares Management's overall financial health at a glance.
Looking for more Ares Management style investment ideas?
Once you have a view on Ares Management, it can help to line it up against other opportunities using the Simply Wall St Screener so you can see where the risk, income and valuation profiles differ in a structured way.
- If you want potential mispricing with quality fundamentals, scan a focused set of 33 high quality undervalued stocks that may warrant a closer look beside Ares Management.
- For readers who care most about stability, compare Ares Management with 29 resilient stocks with low risk scores that show stronger risk profiles on key metrics such as earnings volatility and balance sheet strength.
- If income is your priority, line up Ares Management against 5 dividend fortresses that combine higher yields with an emphasis on payment consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com