


EN
Is XPEL (XPEL) Undervalued After Its Brazil Expansion?
XPEL (XPEL) just opened a new headquarters, warehouse and training center in São Paulo, giving Brazilian dealers direct access to its full suite of paint protection and window film products.
The new Brazil hub lands at a time when XPEL’s short term momentum is picking up again, with a 7 day share price return of 5.82% and a 1 year total shareholder return of 33.87%, even though the year to date share price return is still down 9.14%.
Scan for other auto-focused stocks building out global footprints with resilient fundamentals using our list of solid balance sheet and fundamentals (24 results) as a starting universe, alongside XPEL.
The Brazil move puts fresh price action and the underlying business story on a collision course. Is XPEL’s recent rebound mostly sentiment, or does the valuation now better mirror what the company is building?
Most Popular Narrative: 26% Undervalued
XPEL closed at $45.65, compared with a widely followed fair value estimate of $61.67 that is built on detailed revenue, margin and capital allocation assumptions. That gap puts the new São Paulo site in a bigger story about how manufacturing investment, product mix and channel depth might reshape the company’s earnings power over time.
The main execution priority is XPEL delivering on its planned US$110 million manufacturing and supply chain build out while sustaining growth in higher margin window film, installation services, and OEM and dealership channels across regions such as China, APAC ex China, Europe, and Latin America.
The current valuation, viewed alongside cash generation, manufacturing investment, and a niche leadership position in a paint protection film market that is forecast to reach US$1.54 billion by 2030, suggests that XPEL’s share price reflects expectations that may differ from this narrative’s assessment of a reasonable outcome for the stock.
See why 18 investors see XPEL as 26% undervalued.
Result: Fair Value of $61.67 (UNDERVALUED)
Still, the XPEL story depends on that US$110 million manufacturing build out delivering, and on competition from lower cost Asian producers not eroding pricing power.
Find out about the key risks to this XPEL narrative.
Another View: XPEL On Earnings-Based Pricing
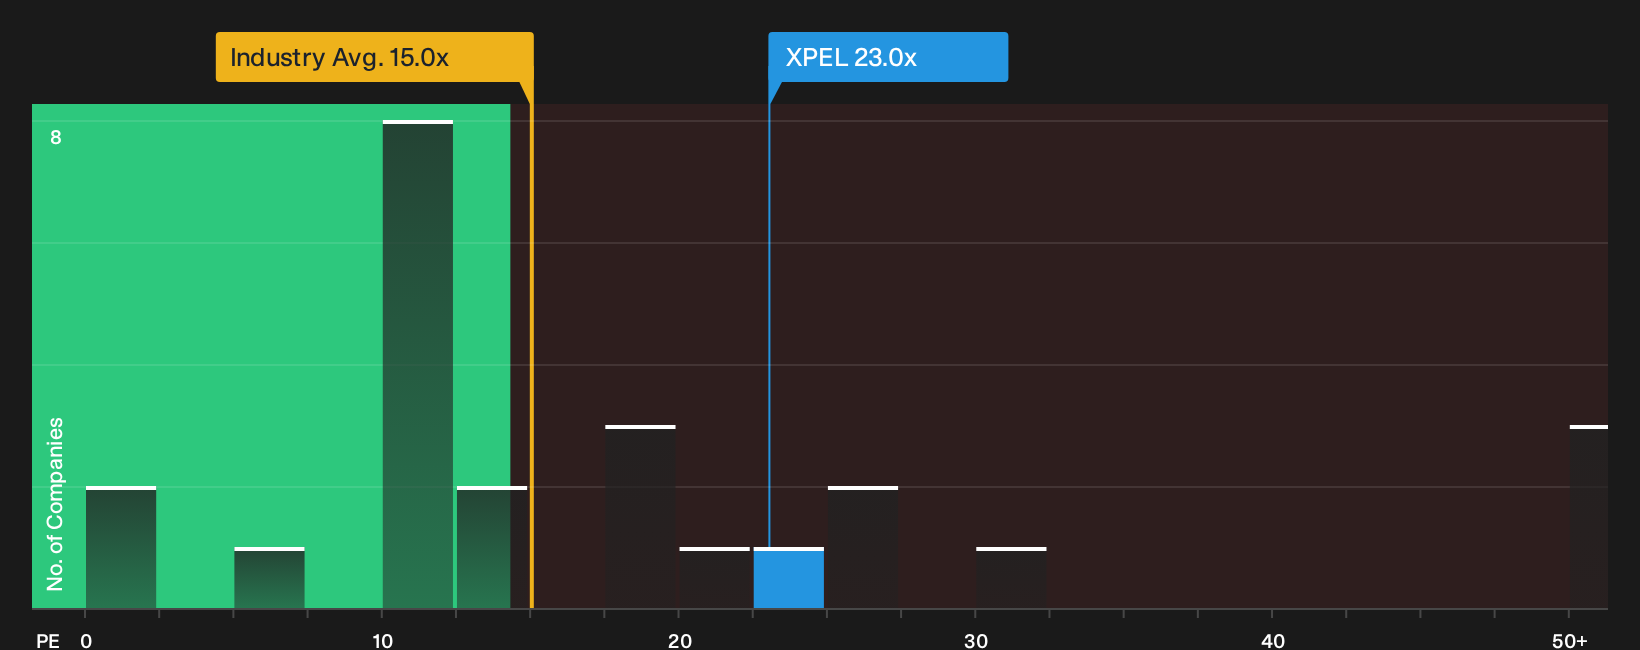
The narrative pegs XPEL at a fair value of $61.67, yet on simple earnings pricing the story is less generous. The stock trades on a P/E of 23x. The wider US Auto Components group sits near 13.6x, and the fair ratio for XPEL is 18.2x. This points to valuation risk if sentiment cools and multiples drift toward that lower anchor.
For a closer look at how this pricing gap might close from here, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment in this piece has leaned toward opportunity, but the real call rests with you and how you weigh both sides of the story. Act while the facts are fresh and review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond XPEL?
You have the story on XPEL. Now widen the lens and pressure test your next moves by lining up other opportunities against the same clear, fact driven framework.
- Target resilience first by scanning companies that pair solid finances with cleaner balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by checking out the 33 high quality undervalued stocks before momentum and sentiment fully catch up.
- Strengthen your income side by reviewing the 5 dividend fortresses and compare yields with the quality of the underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com