


EN
Beacon Financial (BBT) Stock Looks Reasonable On A 32% One Year Run
Beacon Financial shares have delivered a 31.5% return over the past year, which puts a bright spotlight on whether the current price lines up with what the bank is earning today. With that kind of move behind it and fresh corporate actions in play, the core issue for investors is how much of those earnings are already reflected in the valuation.
- The 31.5% gain over the last 12 months raises the question of how much future earnings strength the market is already pricing into Beacon Financial.
- A recent swing back to profitability, alongside higher revenue and an expanded stock repurchase plan, can influence how investors think about the durability of Beacon Financial's earnings power and capital return capacity.
- Your read on Beacon Financial is one view; the desks covering it have another. See what analysts think Beacon Financial's shares could be worth.
The issue now is whether Beacon Financial's current share price is adequately supported by its earnings profile when judged against the Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Beacon Financial across a wider field, compare it with companies in the 33 high quality undervalued stocks.
Does Beacon Financial Look Undervalued on Earnings?
For a bank like Beacon Financial that is back in the black, the P/E ratio is usually the cleanest way to see how much investors are paying for each dollar of earnings.
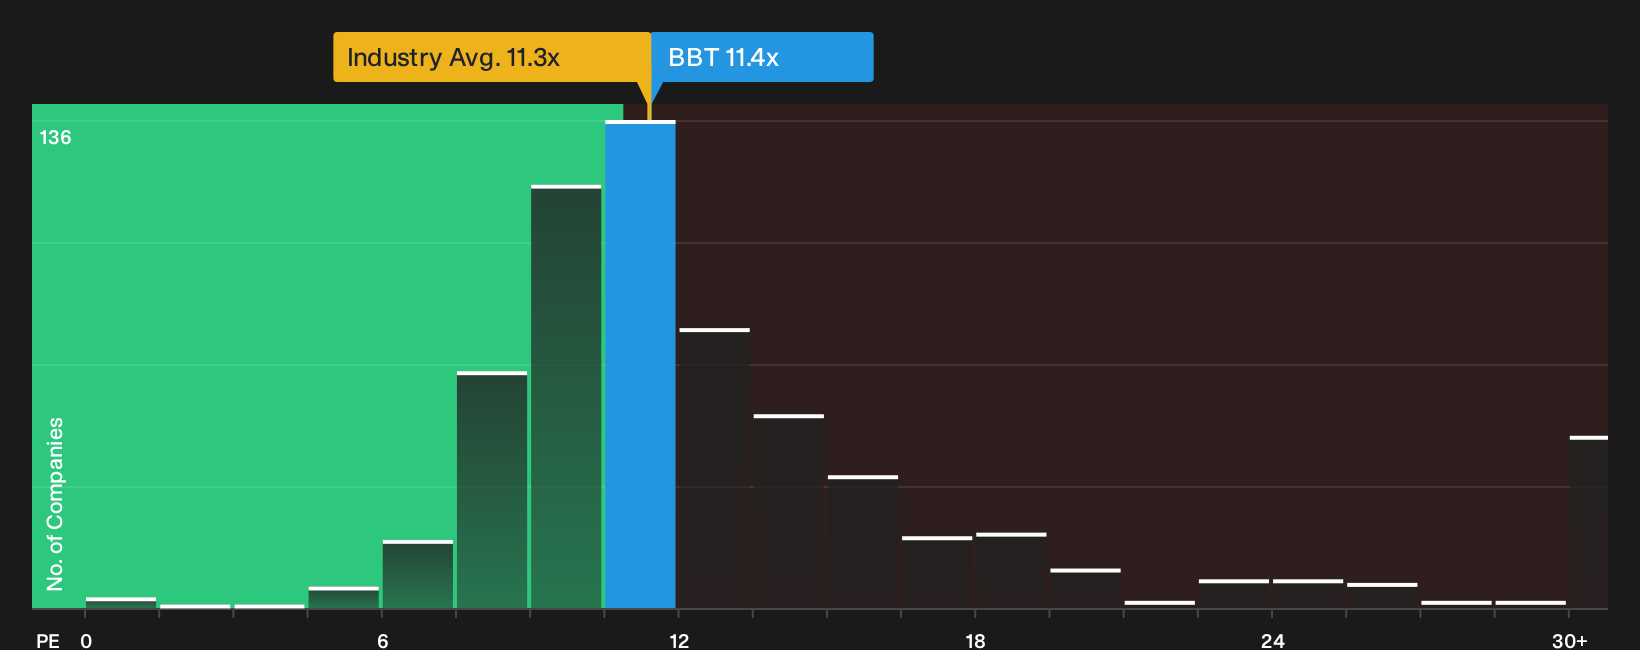
Beacon Financial currently trades on a P/E of 11.4x, which is close to the broader banks industry average of 11.3x but sits below peers on roughly 15.8x. Because the Fair Ratio benchmark points to a higher multiple than the current one, the stock screens as undervalued on this earnings yardstick. The recent swing to quarterly profits and the larger buyback plan help explain why investors may see room for that gap to narrow. Yet the market still prices Beacon Financial at a discount to similar institutions on this measure. Explore the numbers behind Beacon Financial's P/E valuation.
The Beacon Financial Narrative: What Would Justify Today's Price?
Narratives for Beacon Financial pick up where the valuation question leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the current share price to look too low or too high. Each scenario links its number to a clear view on how Beacon Financial's profitability profile and risk mix could evolve, giving you a reference point to revisit as fresh information comes through.
One of the top community narratives on Beacon Financial: 9% undervalued
"Realization of merger cost synergies, including further headcount reductions and vendor consolidation after the core conversion, should reduce operating expenses toward the targeted quarterly run rate..."
Discover why this Narrative puts Beacon Financial at 9% undervalued.
One more Beacon Financial factor to check before you act
Numbers only tell part of the story. The people choosing where Beacon Financial takes risk, and how rewards are shared with insiders, can heavily shape your outcome as a shareholder. See who runs Beacon Financial and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com