


EN
3 Philippine Bank Stocks Built For Higher Interest Rates
Inflation in the Philippines is heating up, policy rates are rising, and the peso is under pressure, which puts a harsh spotlight on which stocks are helped by higher borrowing costs and which ones are squeezed by them. That mix of risk and potential reward creates a window where pricing can move faster than most investors react. This article walks through three Philippine bank stocks from our screener that are directly exposed to these rate and inflation shocks, and explains how the same set of headlines can mean very different things for your portfolio depending on what you own.
The banks covered below are just a starter pack, and the full screen surfaced 4 more Philippine lenders with equally compelling rate and inflation stories that are not broken out in this article. To identify, compare, and analyze those potential net interest margin beneficiaries side by side, head straight into the Philippine Bank Stocks (Net Interest Margin Beneficiaries of Higher Rates) screener.
Metropolitan Bank & Trust (PSE:MBT)
Metropolitan Bank & Trust is a large Philippine commercial and investment bank whose broad loan and deposit base fits the screener’s focus on potential net interest margin beneficiaries. Revenue is led by branch banking at ₱80.1b, treasury at ₱29.8b, consumer at ₱19.4b, corporate at ₱14.2b, with a ₱271.2b market cap backing that scale.
Metropolitan Bank & Trust offers a mix of positive rate sensitivity, a P/E of 5.4x, and an 8.29% dividend yield. This ties to an environment where higher interest rates can support wider net interest margins. The key question is how a relatively small shift in funding costs versus loan repricing may affect outcomes.
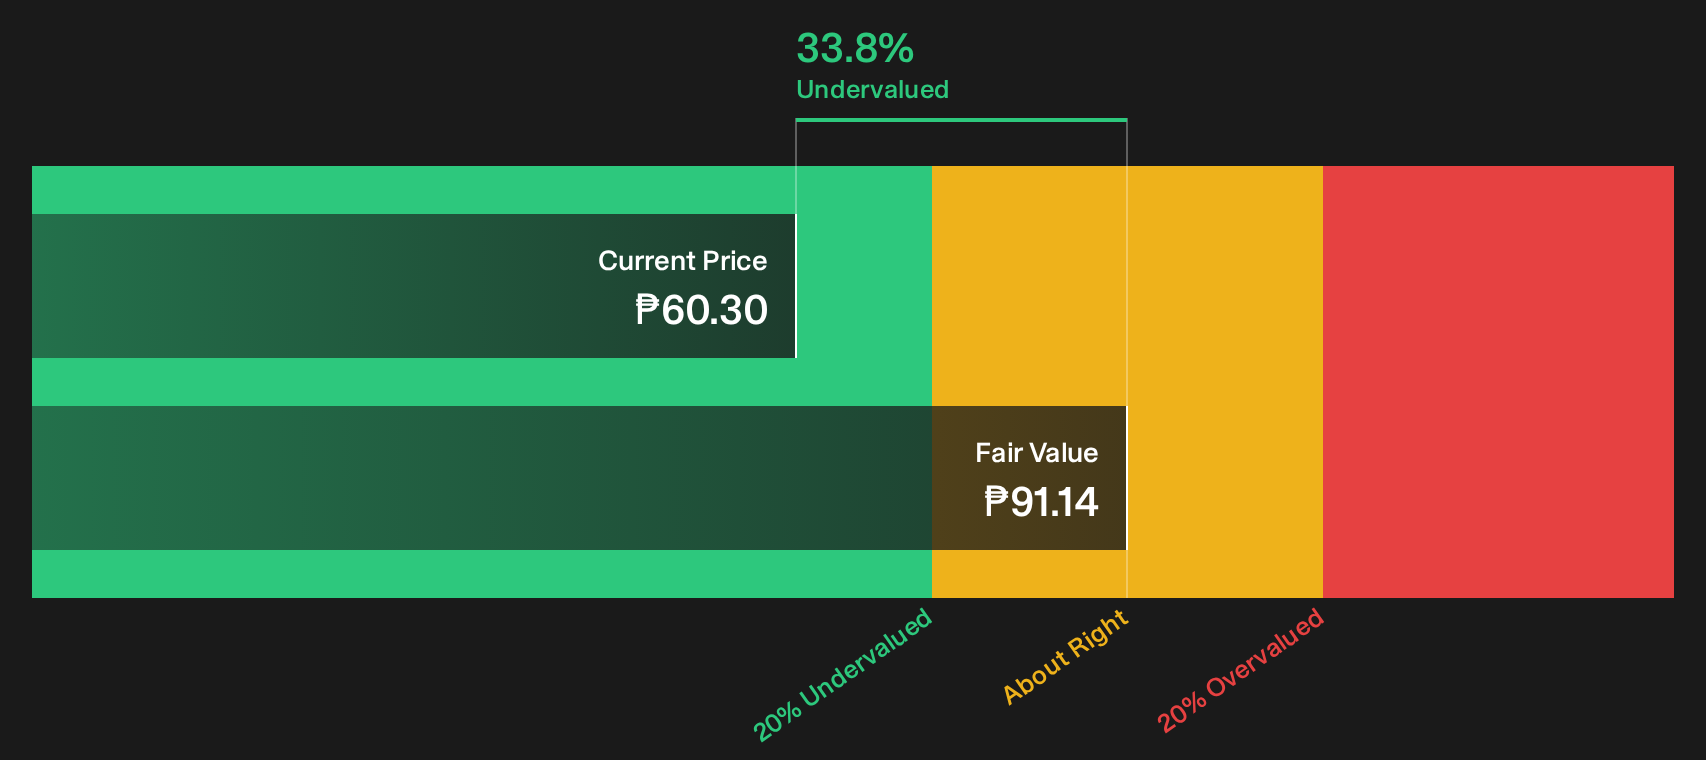
That repricing gap is exactly what stands out in the DCF valuation analysis for Metropolitan Bank & Trust, where rate sensitivity meets valuation and the trade-off between yield and risk comes into focus quickly.
China Banking (PSE:CBC)
China Banking is a full service lender for Philippine households and businesses, from basic deposits and cards to project finance, trade services, wealth management and digital channels, which fits the screener’s focus on rate sensitive loan books. The bank has a market cap of about ₱129.2b.
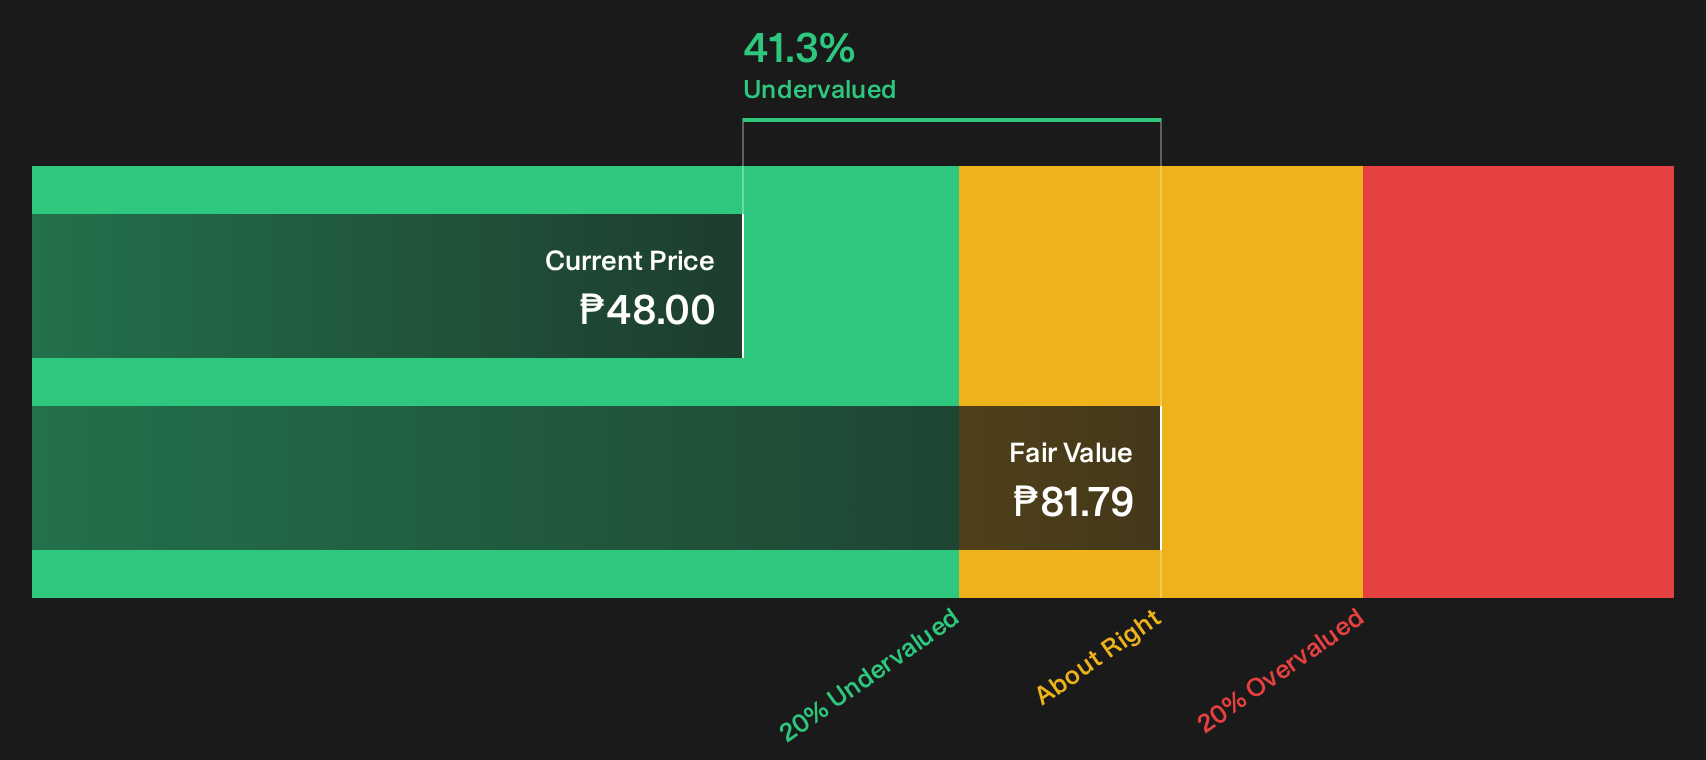
China Banking lines up squarely with the higher rate theme. It carries a P/E of 4.4x, trades at an estimated 41.3% discount to fair value, and pays a 5.83% dividend yield. Recent net interest income and profit data support the idea that loan repricing can help in a rising policy rate cycle, depending on how one unseen pressure plays out.
That unseen pressure is exactly where the analysis report for China Banking can help you spot whether China Banking’s rate story is quietly compounding or starting to strain.
Security Bank (PSE:SECB)
Security Bank is a Philippine lender focused on retail, business, wholesale and financial markets clients, so its loan book and deposit base fit the screener’s net interest margin theme. Retail Banking is at ₱25.8b, Wholesale at ₱20.5b, Financial Markets at ₱8.7b, Business Banking at ₱6.2b, and the bank has a roughly ₱47.0b market cap.
Rising Philippine policy rates and sticky inflation put a spotlight on Security Bank because its broad lending and deposit franchises give it room to benefit from wider net interest margins if funding costs stay in check. That makes the next set of numbers worth your attention.
"Security Bank delivered 22% revenue growth in 2025 to P66.9B, powered by strong core banking and a 26% surge in pre-provision operating profit."
What happens to that performance if a single pressure point in its loan book behaves differently to what the current rate story implies?
That hinge point starts with one detail in the full narrative for Security Bank, where Security Bank’s rate story, credit risk and fee engines either accelerate together or quietly decouple.

Seeking Alternatives Beyond Philippine Bank Stocks
Fresh ideas move first. By the time every chart shows a breakout, early momentum can be gone and under the radar opportunities are already flying. Do not get caught watching. Consider taking action based on your own research and risk tolerance.
- Spot resilient cash generators before the crowd by scanning the curated 196 high quality undervalued stocks while their valuations still look reasonable and sentiment has not fully caught up.
- Explore potential yield and stability in one move by checking the hand picked 226 dividend fortresses while payouts, balance sheets and prices still align with your criteria.
- Position ahead of possible infrastructure momentum by tracking the focused 42 power grid technology and infrastructure stocks while the grid upgrade story is still mostly under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com