


EN
PagSeguro Digital (PAGS) Stock Looks Cheap On a 74% 5 Year Fall
PagSeguro Digital has seen its share price fall sharply in recent years, and that kind of drawdown naturally prompts the question of what investors are really paying for its earnings today. With the stock back near single digits, the key issue is how well the current valuation lines up with the profitability the business is generating.
- Over the past 5 years the stock has fallen 74.4%, which puts the focus squarely on whether the current earnings base can support the price that remains.
- The business model is heavily tied to payments and financial services, so the sustainability of its margins and the quality of its cash conversion may shape what investors are prepared to pay for each dollar of profit.
- There is a second opinion on PagSeguro Digital worth weighing. See what analysts think PagSeguro Digital's shares could be worth.
For investors, the debate is whether PagSeguro Digital's current share price is adequately supported by the earnings it produces today and is expected to generate over time.
If you are weighing PagSeguro Digital's recent share price decline against its profits, it can help to compare that picture with a focused screen of 33 high quality undervalued stocks as a fresh research starting point.
Does PagSeguro Digital Look Undervalued on Earnings?
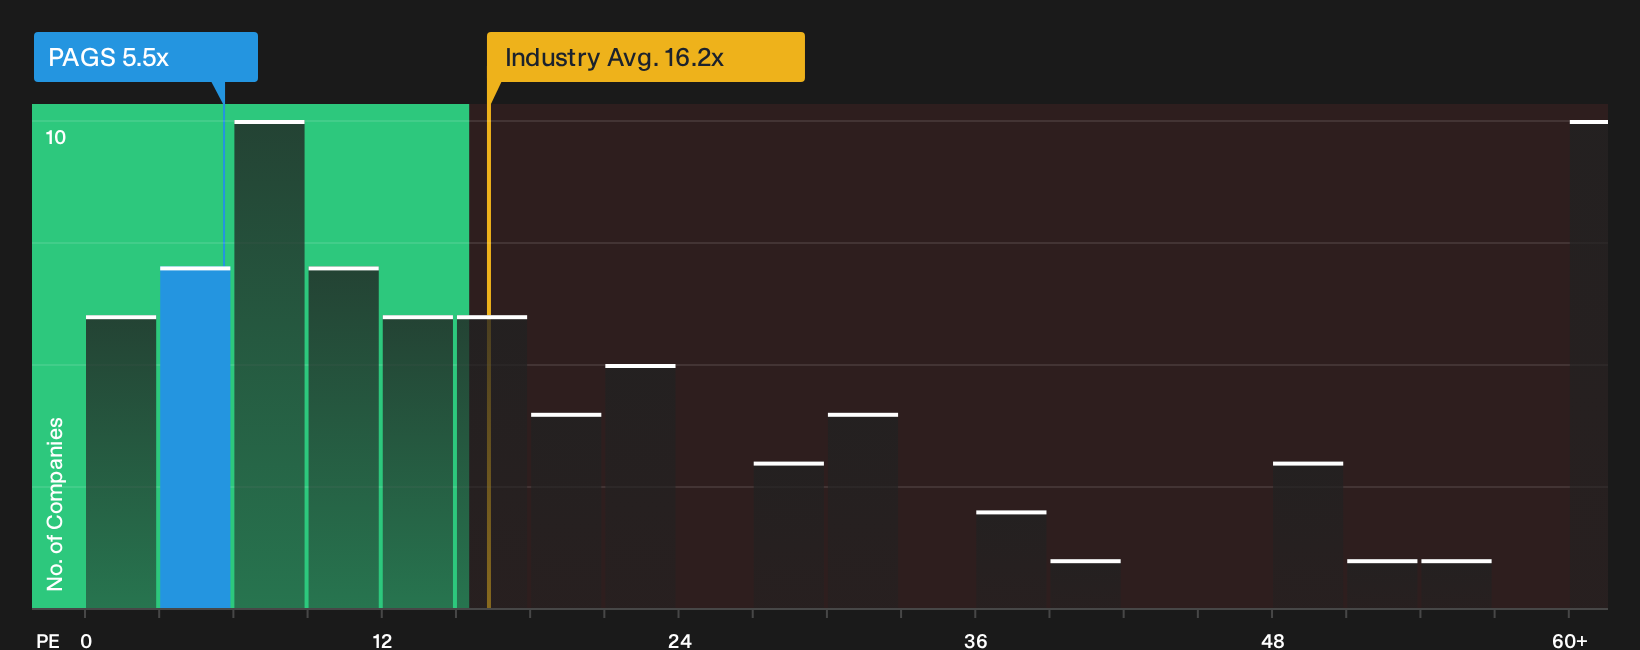
The P/E ratio fits PagSeguro Digital because earnings are a key way investors judge a payments and financial services platform. On this measure, the stock trades at about 5.5x earnings, using the latest figure provided. That sits well below the Diversified Financial industry average of roughly 16.2x and the broader peer group near 19.7x. As a result, the equity currently prices each unit of profit at a steep discount to many comparable businesses.
A tailored fair P/E that factors in PagSeguro Digital's profitability profile, risk and sector context points to a higher level than where the shares currently trade. This comparison implies the stock screens as undervalued on this framework. For anyone weighing that gap, the key questions are how durable the current earnings base looks and whether the quality of those profits matches what the model assumes. Explore the numbers behind PagSeguro Digital's P/E valuation.
The PagSeguro Digital Narrative: What Would Justify Today's Price?
PagSeguro Digital's low P/E raises a simple question. What would the business need to earn in future, in growth, margins and overall profitability, for that multiple to look cheap or expensive in hindsight? Simply Wall St Narratives on the Community page set out those implied paths in plain language. Where a single ratio gives one number, these outline the future that number quietly relies on so you can watch how reality lines up.
Community views on PagSeguro Digital split between a hidden opportunity and a risk that expectations already run too hot.
Bull case: 59% undervalued
"The single biggest lever is the credit portfolio, which sits at roughly R$5 billion today and management targets R$25 billion by 2029..."
Discover why this Narrative puts PagSeguro Digital at 59% undervalued.
Bear case: 13% overvalued
"PagSeguro Digital's current multiples, including references to low P/E and low P/B, imply the share price already reflects expectations of steady profitability..."
Explore why this Narrative puts PagSeguro Digital at 13% overvalued.
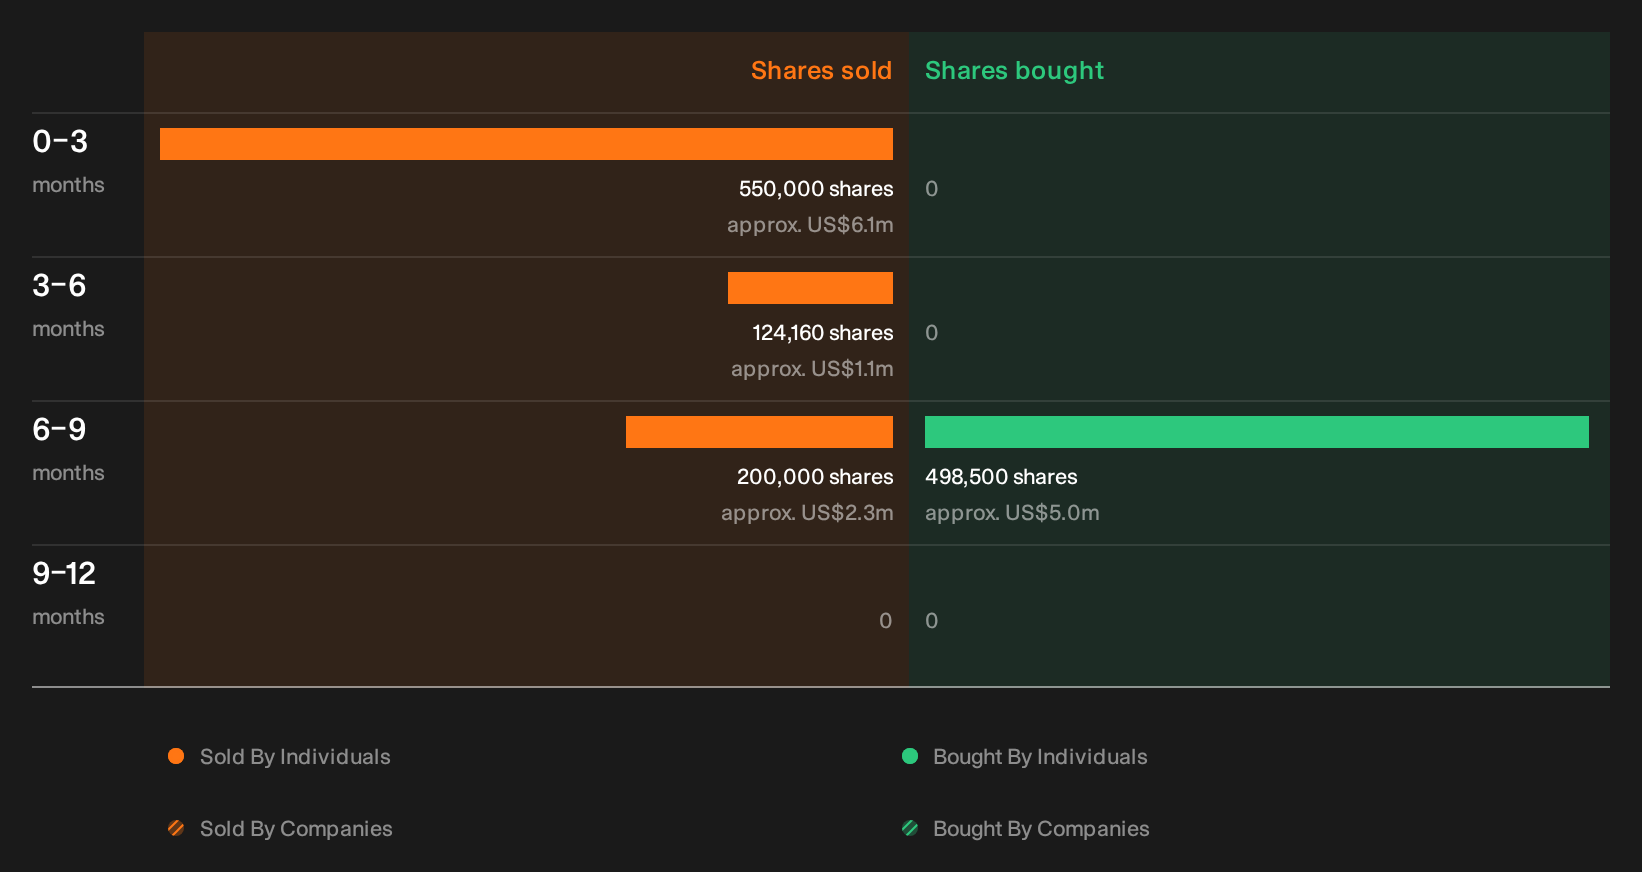
PagSeguro Digital’s price is visible, but investor decisions hinge on what insiders are quietly doing in the background
Our checks have picked up recent share disposals by people on the inside, and the who, how much and what it might mean are details you should review for yourself. See the recent insider selling flagged for PagSeguro Digital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com