


EN
What Northern Trust Stock's Strong Earnings Means For Shareholders
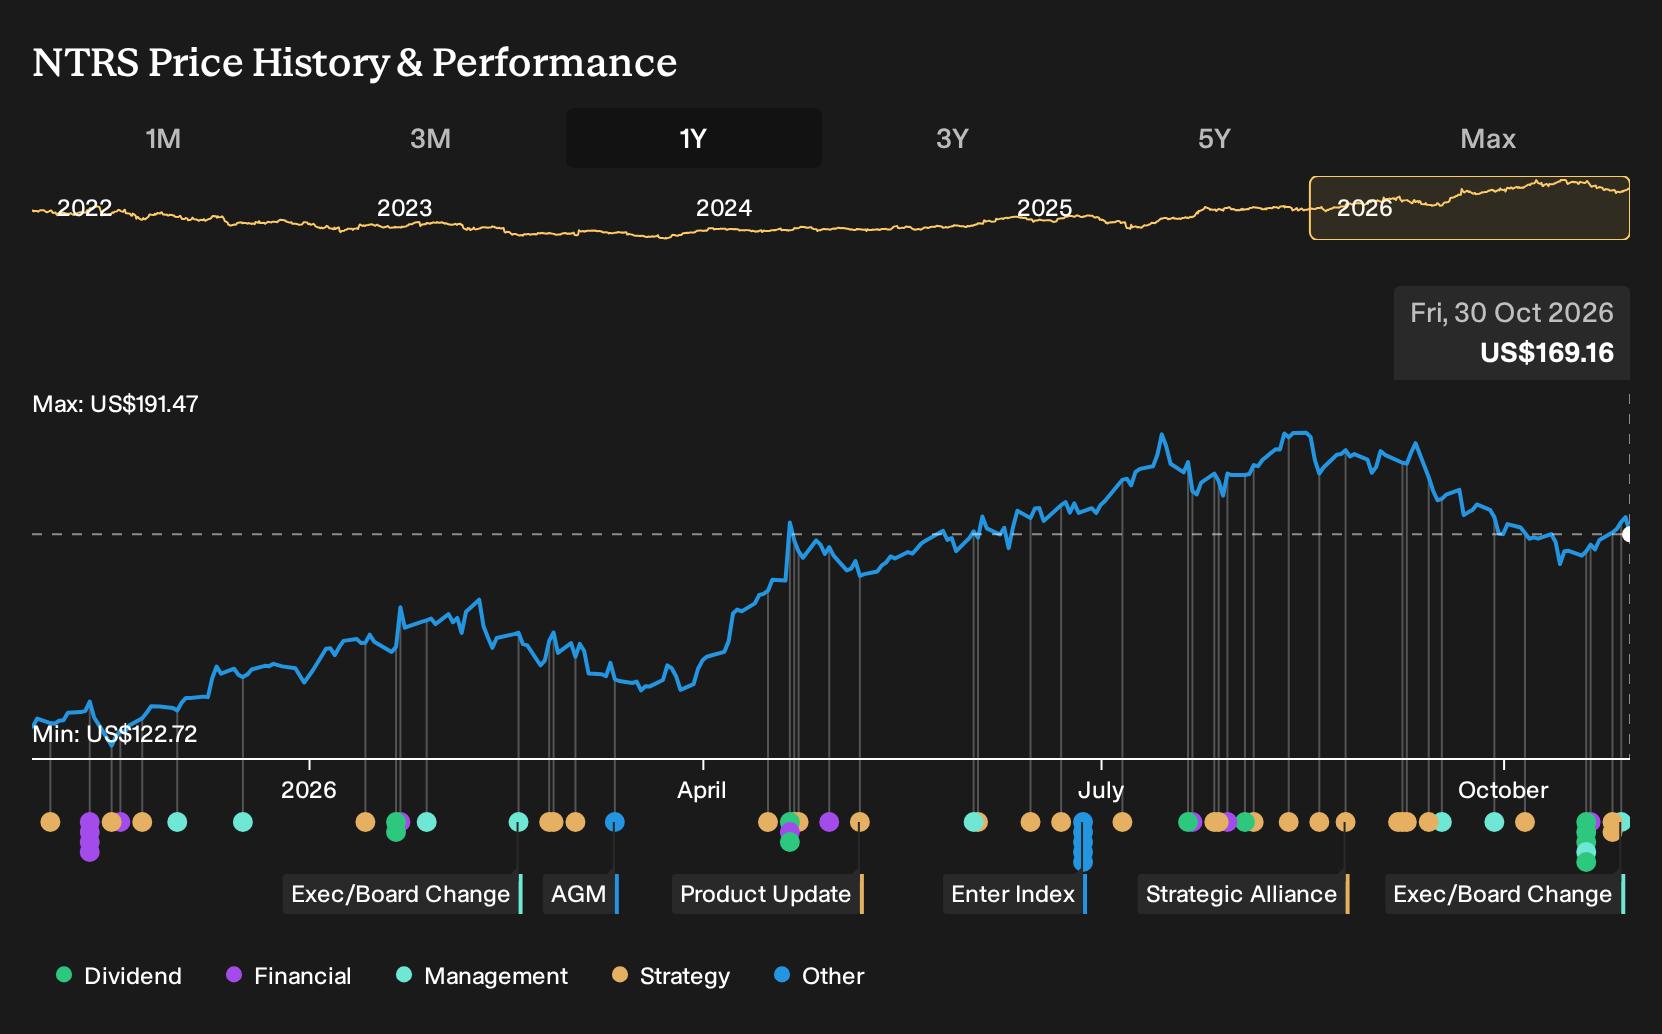
- Northern Trust reported higher third quarter and year to date net interest income and net income compared with the prior year, alongside ongoing common and preferred dividends and an authorized US$3.5b share repurchase program.
- New and renewed asset servicing mandates from LeavePlus and People’s Pension, along with senior insurance leadership hires in EMEA, indicate that Northern Trust is deepening its role with complex institutional clients across custody, administration, and regulatory support.
- Investors may now assess how Northern Trust's stronger earnings, in combination with new institutional servicing mandates, could influence the broader investment narrative.
Scan how Northern Trust’s latest earnings, dividends and new mandates compare with other wealth and custody players by running the hand picked list of solid balance sheet and fundamentals (24 results).
Northern Trust Investment Narrative Recap
For Northern Trust, the story to focus on is a specialist financial group that leans on complex asset servicing, technology efficiency and cross selling under the One Northern Trust model. The latest earnings, dividend decisions and fresh mandates all feed into that picture. The near term swing factor is whether management can keep expense growth below revenue growth as technology and AI investments scale.
The biggest operational risk still sits in people and pricing. Competition for advisers and potential fee pressure in liquidity products could make that efficiency story harder to sustain. Recent wins with insurers and pension schemes do not remove those pressures, but they help diversify revenue streams if client relationships remain sticky.
The new Head of Insurance for EMEA, Andy Ponsford, appears closely tied to the recent LeavePlus and People’s Pension mandates. Northern Trust is focusing on clients that need help across custody, accounting, private markets and regulation. That is where the firm already reports alternative assets under administration above US$1t and more complex fund structures.
In terms of catalysts, this appointment sits alongside the push in Complete FX, Integrated Trading Solutions and AI driven productivity. If the insurance build out in EMEA develops as intended, it could reinforce fee income from complex servicing and support the operating leverage targets management has set. The risk on the other side is execution, particularly if these projects raise costs faster than they add new revenue.
Northern Trust's narrative projects US$10.1b revenue and US$2.5b earnings by 2029. This implies revenue growth of 3.6% per year and an earnings increase of US$0.3b from US$2.2b today.
Uncover why Northern Trust's fair value indicates a 9% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Across just 2 fair value estimates from the Simply Wall St Community, Northern Trust’s projected prices cluster tightly between about US$184 and US$199, with no outliers flagging extreme mispricing. Those views were set before the latest buyback authorization, earnings update and new insurance mandates, so you may want to consider how these developments could reshape expectations and review several alternative viewpoints.
Explore another Northern Trust fair value estimate, including one that suggests it could be worth just $184.27.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northern Trust research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Northern Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Trust's overall financial health at a glance.
Looking for more investment ideas beyond Northern Trust?
Once you have a view on Northern Trust, it can help to compare it with a broader set of companies that meet clear financial criteria. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, income potential or resilience so you can build a watchlist that fits your own approach.
- If you want sturdy businesses with healthy finances, start with a list of solid balance sheet and fundamentals (24 results) that already clear a balance sheet quality bar.
- For investors hunting for potential value opportunities, check companies trading on appealing fundamentals through the 33 high quality undervalued stocks.
- If reliable income is your focus, filter for higher yielding payers with robust metrics using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com