


EN
Healthpeak Properties (DOC) Pulls Back, Is It Still 16% Undervalued?
Healthpeak Properties (DOC) has drawn fresh attention as investors reassess its performance after a recent pullback, with the share price down about 2% over the past month and roughly 12% over the past 3 months.
Despite that pullback, Healthpeak Properties still has a year to date share price return of 17.47%. The 1 year total shareholder return of 14.91% and 3 year total shareholder return of 36.09% point to momentum that has cooled in recent months but remains positive over a longer stretch.
Compare Healthpeak Properties with a curated group of REITs and other income-focused opportunities using our 5 dividend fortresses to see how its recent returns stack up against high-yield peers.
Healthpeak Properties now trades at a level that reflects a recent pullback, while analyst targets and intrinsic value estimates sit higher. How wide is that gap, and what does it suggest about fair value today?
Most Popular Narrative: 16% Undervalued
At a last close of $19.03 versus a widely followed fair value estimate of $22.61, Healthpeak Properties is framed as undervalued by narrative followers, who anchor that view in leasing metrics, Janus Living exposure, and capital recycling rather than short term price moves.
The accelerating shift of surgical and specialty care from inpatient hospital settings to outpatient centers, supported by Healthpeak Properties reporting roughly 5% cash re leasing spreads for 10 consecutive quarters with about 3% annual rent escalators and low tenant improvements, continues to support stronger same store outpatient NOI and cash flow.
See why 35 investors see Healthpeak Properties as 16% undervalued.
Result: Fair Value of $22.61 (UNDERVALUED)
Still, the Healthpeak Properties story depends on lab and life science income stabilising and on capital recycling deals remaining available on similar terms.
Find out about the key risks to this Healthpeak Properties narrative.
Another View on Healthpeak Properties' Valuation
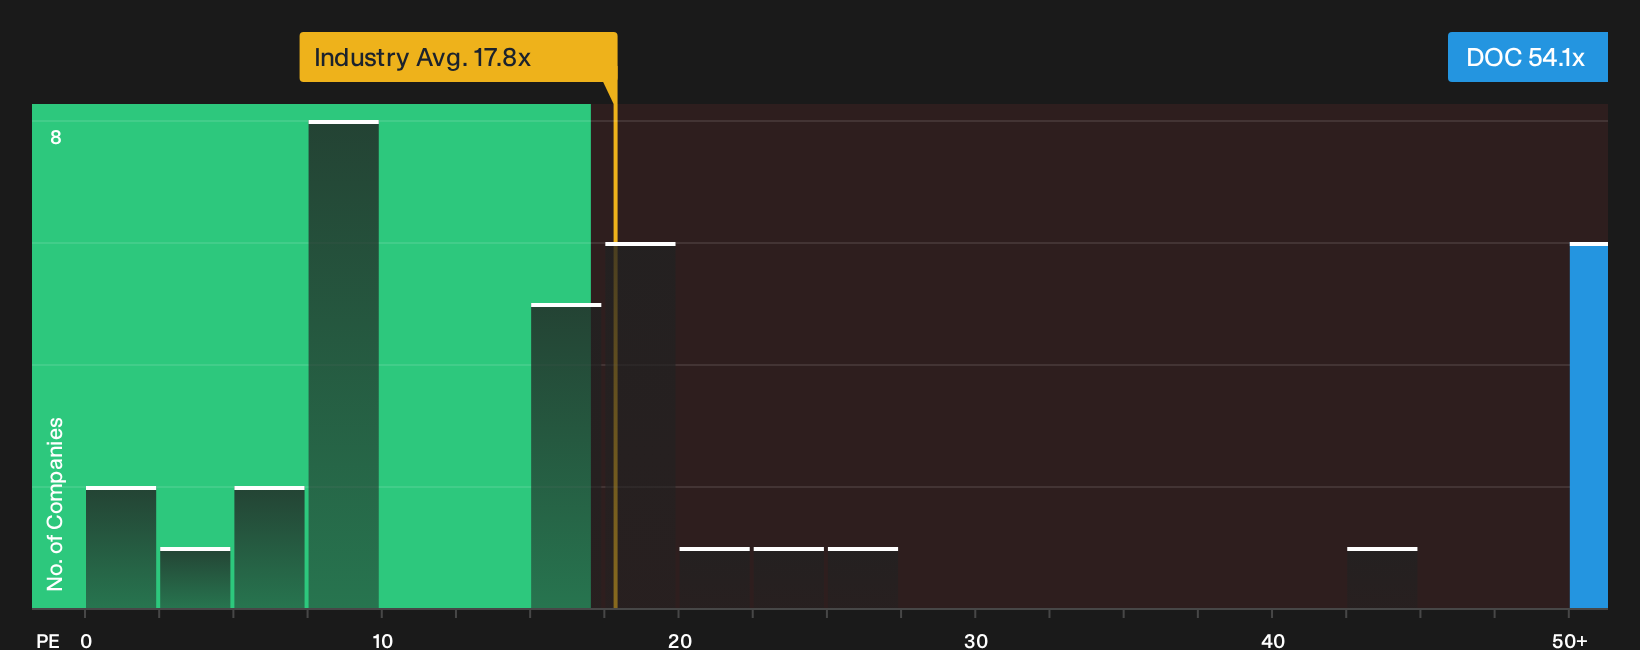
On price ratios, Healthpeak Properties paints a different picture. The stock trades on a P/E of 54.1x, while the fair ratio is 21.8x and the Global Health Care REITs average sits at 17.8x. That gap points to valuation risk rather than a clear bargain, so which signal should you trust?
To see how this pricing stacks up against detailed earnings assumptions and scenario work, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Healthpeak Properties so far. If you want to move before sentiment shifts again, weigh the potential benefits against the red flags by checking the 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Healthpeak Properties?
If Healthpeak Properties has you rethinking your watchlist, do not stop here. Broader context across sectors can sharpen every decision and highlight opportunities you might otherwise skip.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for quality at a discount by running through a curated 33 high quality undervalued stocks that pairs strong business metrics with appealing valuations.
- Build a more dependable income stream by reviewing a focused 5 dividend fortresses that highlights higher yield opportunities with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com