


EN
Amneal Pharmaceuticals (AMRX) Rallies As Its Complex Generics Story Tests Whether Value Remains
Recent share performance and business profile
Amneal Pharmaceuticals (AMRX) has drawn fresh attention after a strong run in its shares, with the price closing at $21.51 and year to date total return data indicating a solid move.
The business reports annual revenue of $3.12b and net income of $157.36m, spread across three operating segments that cover affordable generics, specialty treatments and government focused distribution through AvKARE.
Amneal Pharmaceuticals’ recent share price strength sits on top of steadily building momentum, with a 30 day share price return of 5.96%, a 90 day gain of 16.4% and a striking 1 year total shareholder return of 92.14% that points to investors reassessing both its growth runway and its risk profile over a longer horizon.
Scan beyond Amneal Pharmaceuticals to see how its momentum compares with other potential breakout candidates in our hand picked list of 19 high quality undiscovered gems
Bulls argue Amneal Pharmaceuticals now earns its richer reputation, while bears see a hot run fueled more by momentum than value. Which side do today’s fundamentals and valuation signals back up?
Most Popular Narrative: 6.5% Undervalued
Amneal Pharmaceuticals is framed as modestly undervalued, with a central fair value estimate of $23.00 set against the recent $21.51 close. This comparison puts the spotlight firmly on what needs to go right in the business to support that gap.
Amneal Pharmaceuticals is pursuing a deliberate shift toward complex generics such as transdermal patches, injectables, ophthalmics and drug device combinations. Management is targeting an additional US$1b to US$2b of Affordable Medicines revenue by 2030, which directly targets higher value revenue growth.
See why 20 investors see Amneal Pharmaceuticals as 6% undervalued.
The most followed narrative uses a 7.24% discount rate and a fair value of $23.00, which is only slightly above the current analyst consensus target of about $23.00 and around 6.5% above the market price. That framing puts Amneal Pharmaceuticals in a zone where small changes in expectations for complex generics, biosimilars execution or Specialty uptake could matter more than broad market moves.
Under that framework, revenue growth assumptions of roughly 9.1% a year and a move in profit margins toward about 10% are doing much of the heavy lifting. The implied 2029 earnings of $404.1m and an assumed P/E of 23.5x are what connect the business narrative around Affordable Medicines, Kashiv and GLP 1 partnerships back to the $23.00 fair value line in the model.
Result: Fair Value of $23 (UNDERVALUED)
Still, heavy U.S. generics price pressure and higher capital spending that does not translate into stronger earnings could quickly challenge the current Amneal Pharmaceuticals narrative.
Find out about the key risks to this Amneal Pharmaceuticals narrative.
Another View: What The P/E Ratio Says About Amneal Pharmaceuticals
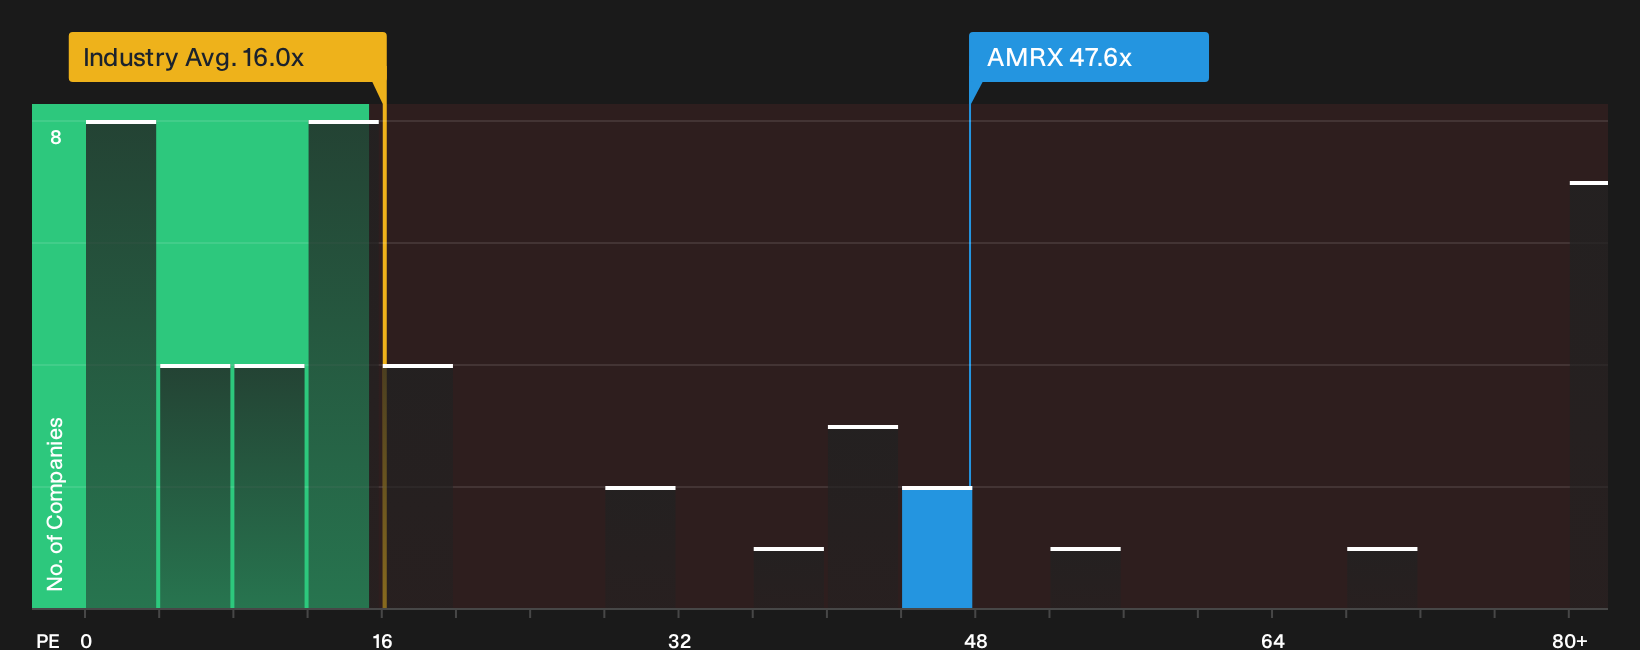
The fair value story for Amneal Pharmaceuticals at $23.00 leans on future earnings and cash flows. A different lens, the current P/E of roughly 47.6x, paints a far less forgiving picture given the US Pharmaceuticals sector closer to 16x and a fair ratio estimate of 28.1x.
That gap suggests investors today are paying a premium both to peers and to where the P/E ratio could move if expectations cool. The key question is whether earnings growth and execution on complex generics, biosimilars and Specialty are strong enough to prevent that premium from shrinking over time.
To see how the numbers stack up using this earnings based yardstick, take a look at See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Amneal Pharmaceuticals compares with sector valuations, review the latest
Next Steps
Mixed about what all this says on Amneal Pharmaceuticals yet? Act quickly, review the key data, and weigh both sides through 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Amneal Pharmaceuticals?
If Amneal Pharmaceuticals has sharpened your investing focus, do not stop here. The next strong idea often comes from looking just a little wider.
- Target potential mispricings by reviewing companies that pass rigorous value and quality filters in the 33 high quality undervalued stocks.
- Strengthen portfolio resilience by checking businesses that score well on balance sheet strength and fundamentals in the list of solid balance sheet and fundamentals (24 results).
- Hunt for under the radar opportunities by scanning companies that qualify as 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com