


EN
Morningstar (MORN) Earnings Put Its AI Growth Narrative And Valuation Back In Focus
Morningstar earnings and buyback catch investor attention
Morningstar (MORN) has drawn fresh interest after third quarter 2026 earnings showed higher sales, net income, and earnings per share, alongside progress integrating PitchBook data into AI platforms.
The business has also been active on capital returns. Between July and September 2026, Morningstar bought back 486,573 shares for US$100 million, completing a broader repurchase program totaling 4,180,678 shares for about US$800 million.
Morningstar’s recent earnings and buyback update come after a strong run in the share price, with a 30 day share price return of 23.23% and a 90 day gain of 13.70% at a last close of US$226.19.
Short term momentum looks firm compared with the 7.49% year to date share price return, while the 1 year total shareholder return of 7.71% contrasts with declines over the 3 and 5 year total shareholder return periods. This suggests that the recent optimism around earnings and the PitchBook AI integration is still relatively fresh in the longer history of the stock.
Scan how Morningstar’s AI and data momentum compares with other information and analytics businesses by reviewing the hand picked 19 high quality undiscovered gems now moving on stronger fundamentals.
After a sharp 30 day jump and a completed US$800 million buyback, Morningstar now asks a simple question of investors: pay up today for that momentum or wait and hope for a cheaper entry.
Most Popular Narrative: 8% Undervalued
Morningstar’s most followed narrative pegs fair value at $246.00 versus the last close of $226.19. This frames the recent rally as a move toward, not beyond, that estimate.
The integration of PitchBook private market data into AI platforms such as ChatGPT for Financial Services and Gemini Enterprise for Financial Services creates new data licensing and workflow subscription opportunities that can support higher revenue per user and improved margins as distribution scales.
Lumonic 12.0 and the MCP server that connects portfolio data to leading AI assistants point to deeper adoption of AI driven portfolio monitoring tools, which can expand Morningstar’s addressable spend with private market clients and support future revenue growth.
See why 1 investors see Morningstar as 8% undervalued.
The narrative applies an 8.29% discount rate and points to earnings of $541.7 million by around 2029, with a future P/E of 17.2x anchoring the $246.00 fair value. With the current price sitting about 8.1% below that mark and only a small gap to the analyst consensus target, the story presents Morningstar as roughly in line with those expectations rather than deeply mispriced.
Result: Fair Value of $246.00 (UNDERVALUED)
Still, the Morningstar narrative can break if AI tools such as PitchBook integrations fail to gain traction or if insider selling continues to dent confidence.
Find out about the key risks to this Morningstar narrative.
Another View on Morningstar’s valuation
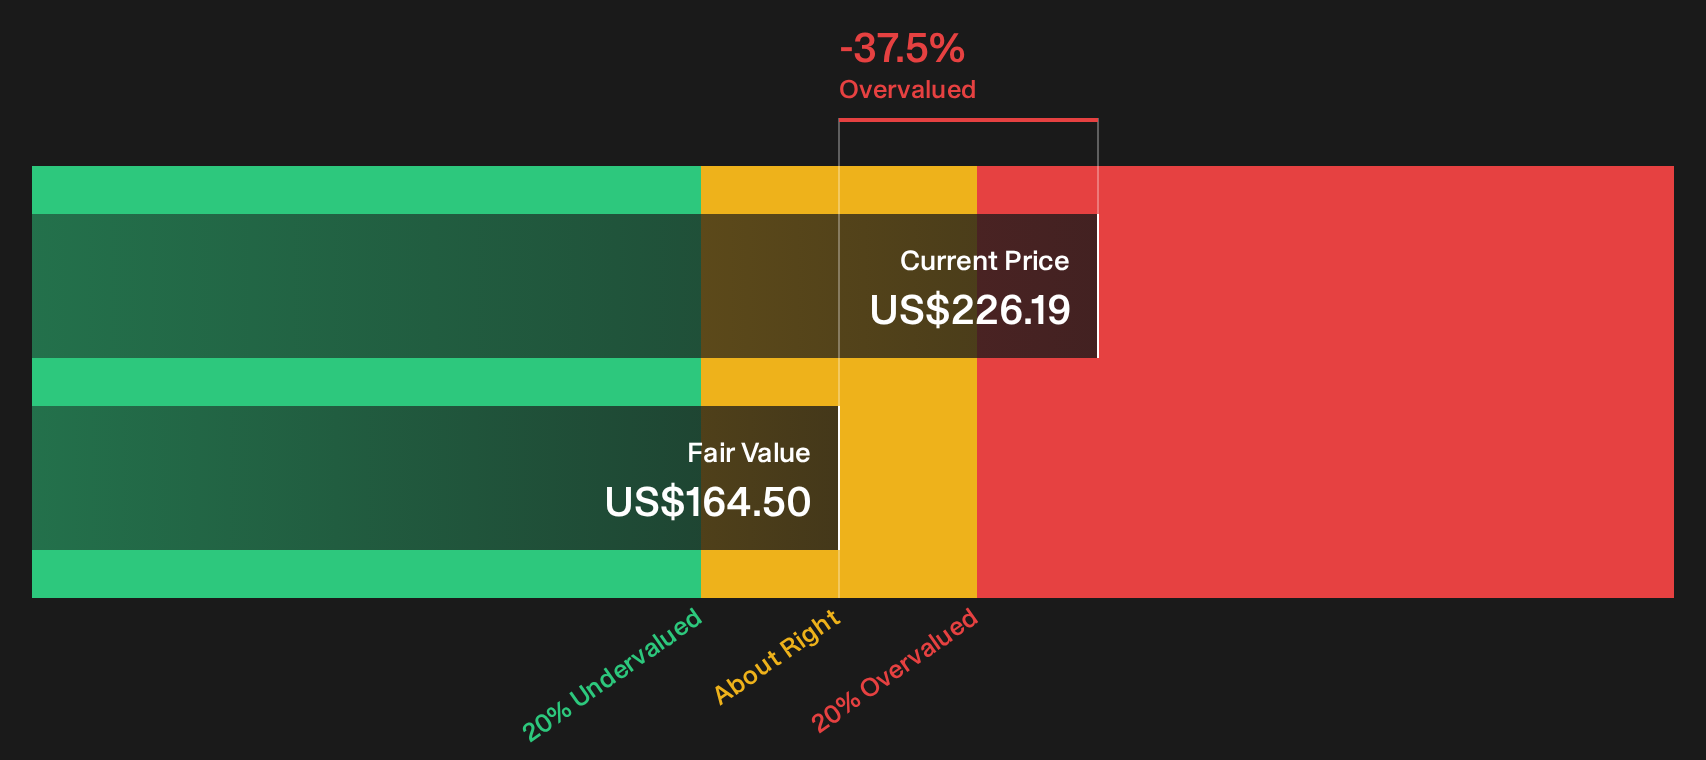
Fair value in the leading community narrative puts Morningstar at $246.00, with the stock described as 8% undervalued. The SWS DCF model lands in a very different place, with an estimate of future cash flow value around $164.50, which frames the current $226.19 price as expensive instead. Which story do you think fits your assumptions better?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed opinions on Morningstar’s value story are clear, so move quickly, review the underlying numbers yourself, and weigh up 3 key rewards and 1 important warning sign.
Looking for more Morningstar style investment ideas?
If Morningstar’s story has sharpened your focus, do not stop here. Cast the net wider now and give yourself more quality options to compare.
- Target stronger balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that filters for financial resilience and cleaner capital structures.
- Hunt for potential mispriced opportunities by reviewing a focused 33 high quality undervalued stocks that highlights companies with solid fundamentals trading below their implied worth.
- Build a more defensive watchlist by checking a hand picked 29 resilient stocks with low risk scores that concentrates on businesses with lower risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com