


EN
What Snap on Shares Earnings Slip Means For Shareholders
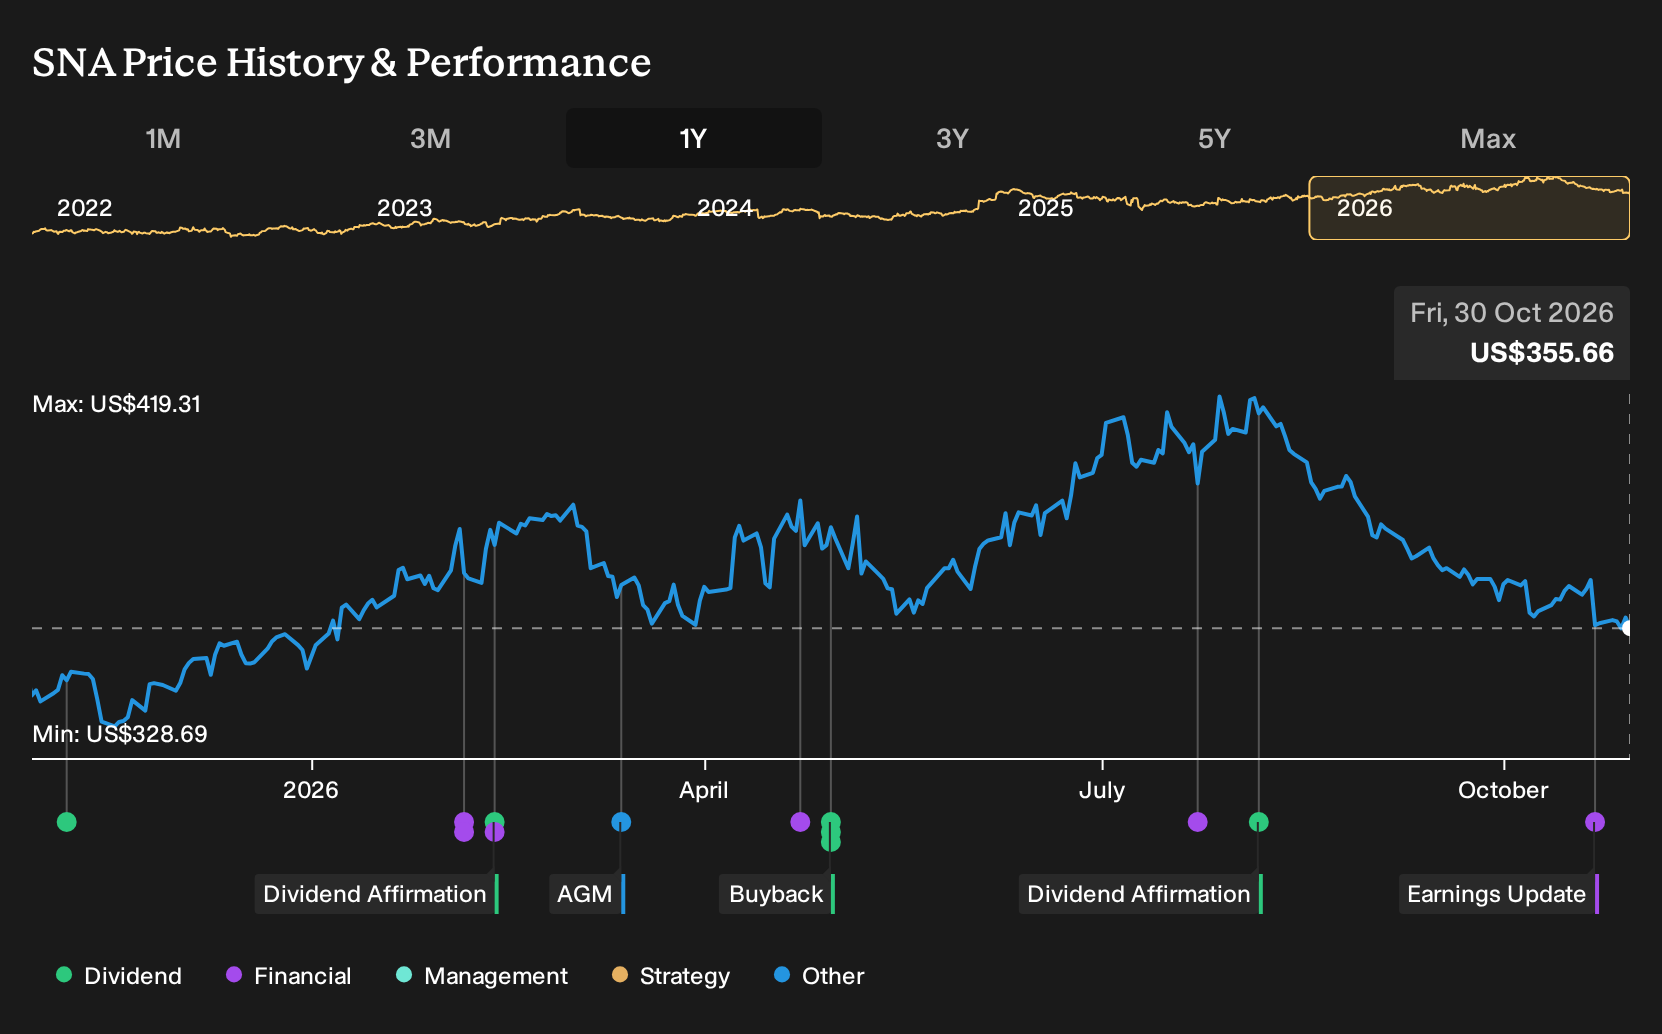
- Snap-on reported third quarter 2026 sales of US$1,183.7 million and net income of US$243 million, both slightly lower than the prior year, with diluted EPS from continuing operations of US$4.64 compared with US$5.02.
- Over the first nine months of 2026, Snap-on produced higher sales of US$3,626 million while net income stayed broadly similar, which points to modest top line progress but tighter pressure on profitability.
- We will look at how Snap-on's mixed quarterly earnings, especially softer net income, may reshape the broader investment narrative investors follow.
Look past Snap-on's mixed earnings and line up your next idea with our hand picked list of solid balance sheet and fundamentals (24 results) for comparison.
Snap-on Investment Narrative Recap
To own Snap-on, you need to believe its core customer base of professional technicians and critical industries keeps relying on its tools, diagnostics, software and finance offerings even when sentiment softens. The latest quarter shows sales broadly steady but net income and EPS under some pressure, which keeps the focus on margins rather than headline growth.
The key short term catalyst remains execution in higher margin areas like diagnostics, information systems and software driven platforms such as APOLLO. The biggest near term risk is that cautious technicians keep delaying larger ticket purchases and finance uptake. This earnings release does not fundamentally change that risk reward balance.
The most relevant disclosure here is the full nine month view that sits behind the third quarter earnings. Snap-on reported US$3,626 million of sales for the period, ahead of the prior year figure, while net income of US$750.6 million was broadly similar to US$756.2 million previously.
That combination of slightly higher revenue and flat profit underlines the current debate. Execution upside centers on whether diagnostics, software and industrial customers can support mix and margins. The operational downside sits in slower big ticket tool storage and financial services demand if cautious technicians and franchisees stay hesitant on longer payback spending.
Snap-on's current analyst narrative points to forecast revenues of US$5.6b and earnings of US$1.3b by 2029, based on an assumed 2.0% yearly revenue growth rate and an earnings increase of about US$300m from US$1.0b today.
Uncover why Snap-on's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Snap-on forecasts leaned heavily on electric vehicle disruption risk. Those analysts were already working with slower revenue assumptions of about US$5.5b and earnings of roughly US$1.3b by 2029, and this softer quarter may prompt them to reassess. Use that spread to explore how far opinions can differ.
Explore 4 other Snap-on fair value estimates, including one that suggests it could be worth just $343.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Snap-on research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Snap-on. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Snap-on's overall financial health at a glance.
Looking for more investment ideas beyond Snap-on?
Once you have a view on Snap-on, it can help to benchmark that thinking against other opportunities that match different risk and income profiles using the Simply Wall St Screener.
- If you want steadier balance sheets and fewer surprises, compare Snap-on against companies in the 29 resilient stocks with low risk scores that score well on resilience and financial strength.
- For investors who care most about dependable income, line up Snap-on beside high yield payers in our 5 dividend fortresses and see how the cash returns stack up.
- If you are hunting for quality that is not yet widely followed, widen your watchlist with the 19 high quality undiscovered gems and see which fundamentals appeal most.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com