


EN
Is ADP Small Business Tie Up Altering The Investment Case For PNC Bank (PNC)?
- PNC Financial Services Group, through PNC Bank, announced a partnership with ADP that embeds payroll, HR, benefits, time, insurance and retirement tools into its small business digital banking experience, with 24/7 access to ADP payroll experts.
- The deal plugs ADP’s AI enabled payroll and compliance expertise, built from serving more than 900,000 small businesses, directly into PNC’s cash management and payment workflows, tightening the link between operating accounts and workforce administration for small business clients.
- Attention now turns to how PNC Financial Services Group’s investment narrative evolves as ADP’s AI driven payroll platform is folded into its digital banking.
PNC Financial Services Group Investment Narrative Recap
To own PNC Financial Services Group, you need to believe that heavy spending on technology, AI and a broad branch footprint can turn into steadier fee income and controlled costs over time. The ADP integration fits that story by tying payroll, HR and banking into one workflow for small firms, which supports PNC’s push in cash management and treasury services.
Near term, the key swing factor is whether client activity holds up in those fee based businesses. The biggest risk is a turn in credit quality that lifts provisions and squeezes net margins. The ADP news helps the operating narrative but does not fundamentally change that risk balance right now.
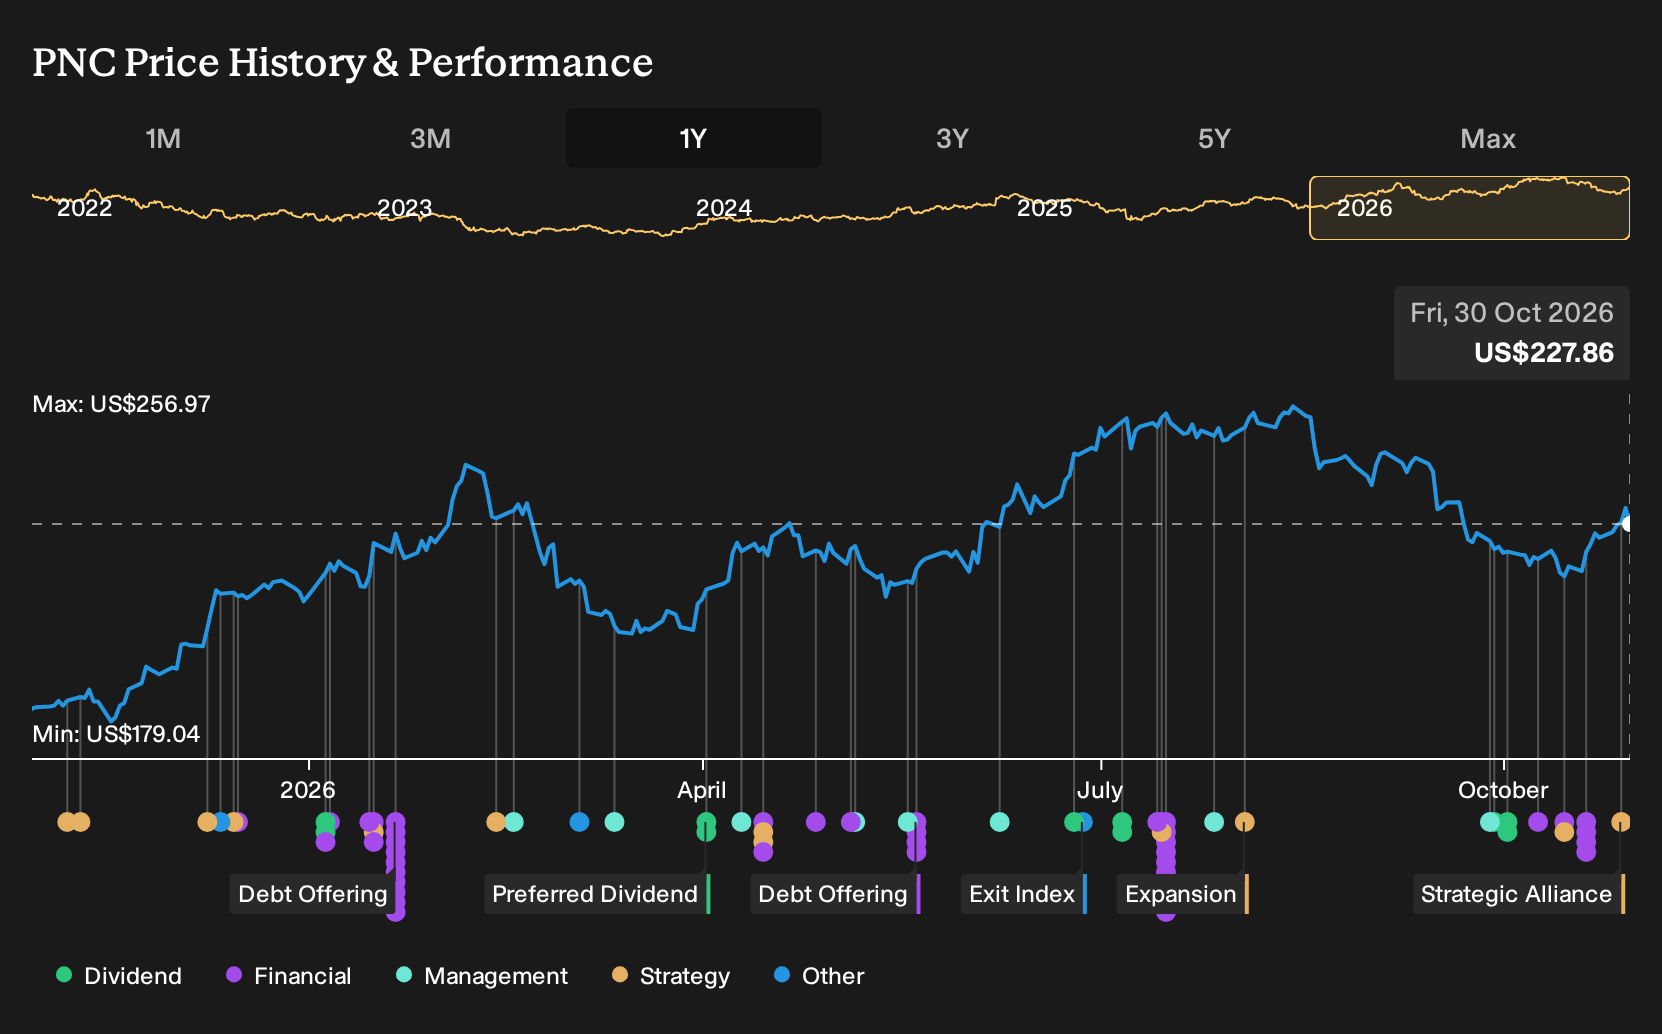
The fixed income offerings completed on 20 October 2026 are the other useful piece of context here. PNC issued US$300m of floating rate notes and US$1.2b of fixed to floating securities, all senior and unsecured. That gives the bank additional funding flexibility as it leans into technology projects and national expansion.
For you as an investor, these bond deals sit alongside PNC Payroll by ADP as part of the same execution test. Management is investing heavily in AI, automation and new products while adding branches. The potential upside for shareholders depends on whether those outlays improve operating leverage without eroding credit discipline. Any deterioration in loan quality would quickly dominate the story.
PNC Financial Services Group's current analyst narrative points to forecast revenue of US$29.2b and earnings of US$8.8b by 2029. That profile assumes revenue growth of 5.4% per year and an earnings increase of about US$1.3b from US$7.5b today to reach the 2029 consensus level.
Uncover how PNC Financial Services Group's fair value indicates a 16% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$264 to roughly US$395 per share, which shows how far apart retail views on PNC Financial Services Group can sit. Add in execution risks around credit quality and the new ADP partnership, and you get plenty of room for competing narratives.
Explore another PNC Financial Services Group fair value estimate, including one that suggests as much as 74% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PNC Financial Services Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PNC Financial Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PNC Financial Services Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond PNC Financial Services Group?
Once you have a view on PNC Financial Services Group, it can help to compare it with other opportunities that suit different risk levels, income needs and balance sheet profiles. The Simply Wall St Screener offers several focused filters that keep the heavy lifting off your plate while you concentrate on the stories behind each ticker.
- If capital preservation comes first for you, start with companies that score well on resilience and stability using our 29 resilient stocks with low risk scores.
- If you prefer to get paid while you wait, scan for income focused opportunities through the 5 dividend fortresses that prioritize higher yields.
- If you want to back strong business quality early, look through our 19 high quality undiscovered gems that highlight robust fundamentals before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com