


EN
Greatland Resources And 2 Australian Undervalued Stocks
Australian shares opened this week with a weak lead from Wall Street, as a heavy tech selloff reminded investors that earnings stories can move prices fast. When sentiment swings this hard, solid cash flows and realistic valuations start to matter more. That is where underpriced cash generators come in. This article highlights three Australian stocks that screen as undervalued on discounted cash flow, and explains why they may deserve a closer look.
The three stocks profiled below are just a sample of the idea, and the full screen on Simply Wall St surfaced 4 more companies with similarly interesting cash flow stories that are not covered here. To identify and analyze potential value opportunities for yourself, head straight into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper developer whose Havieron project sits squarely in the cash flow story this screener targets, making it a useful case study for how future production potential can influence DCF based estimates of value.
Greatland Resources focuses on the Havieron gold copper deposit in Western Australia, generating A$2.26b from the Telfer Havieron segment, and has a market value of about A$6.62b.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What happens to those projected margins and cash flows depends heavily on how one crucial external force evolves from here.
That uncertainty around the key driver is exactly what the full narrative for Greatland Resources unpacks, showing how Greatland Resources could accelerate or stall as scenarios shift.
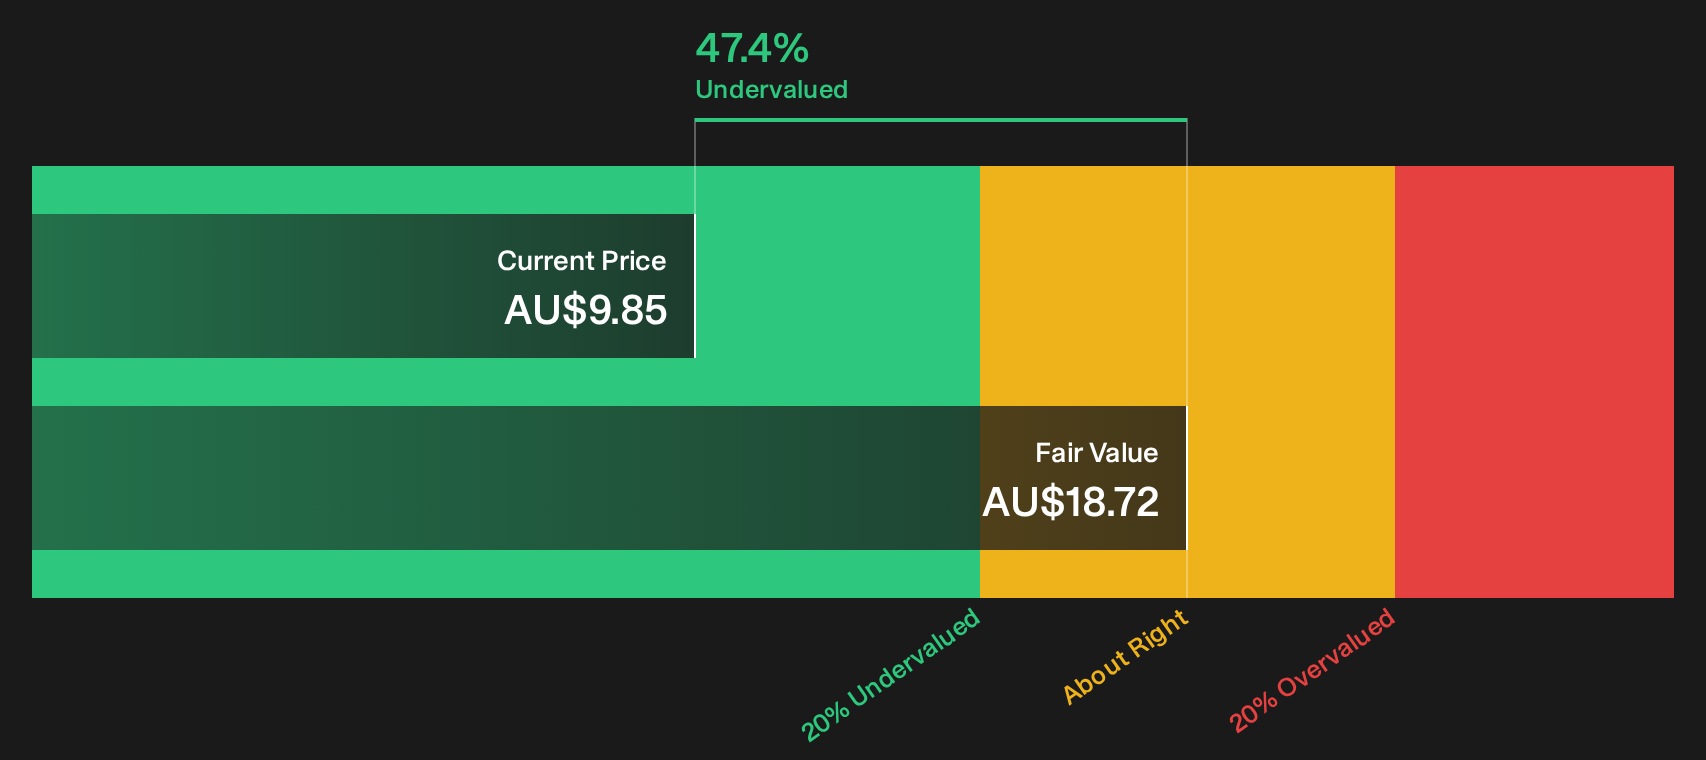
Ansell (ASX:ANN)
Ansell is a global personal protective equipment group that designs and sells disposable medical gloves and industrial protection gear. The Healthcare unit’s surgical and examination glove brands provide the recurring consumable cash flows that tie it to this cash flow focused screener. Healthcare produced about US$1.19b in revenue, Industrial around US$947 million, and the business has a market value near A$6.31b.
For investors tracking recurring cash flow potential rather than headline stories, Ansell offers a mix of consumable healthcare products and diversified industrial protection that fits neatly with this undervalued cash flows theme.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets. Volatility in raw-material prices (nitrile, latex, energy), freight disruptions, and trade/tariff risks (i.e., US import tariffs) can pressure margins."
This ultimately affects Ansell’s valuation signal by influencing how a single moving piece reshapes the balance between pricing power and cost pressure.
That pricing power versus cost squeeze is exactly what the full narrative for Ansell unpacks, revealing how Ansell’s PPE cash engine could accelerate or stall as conditions shift.
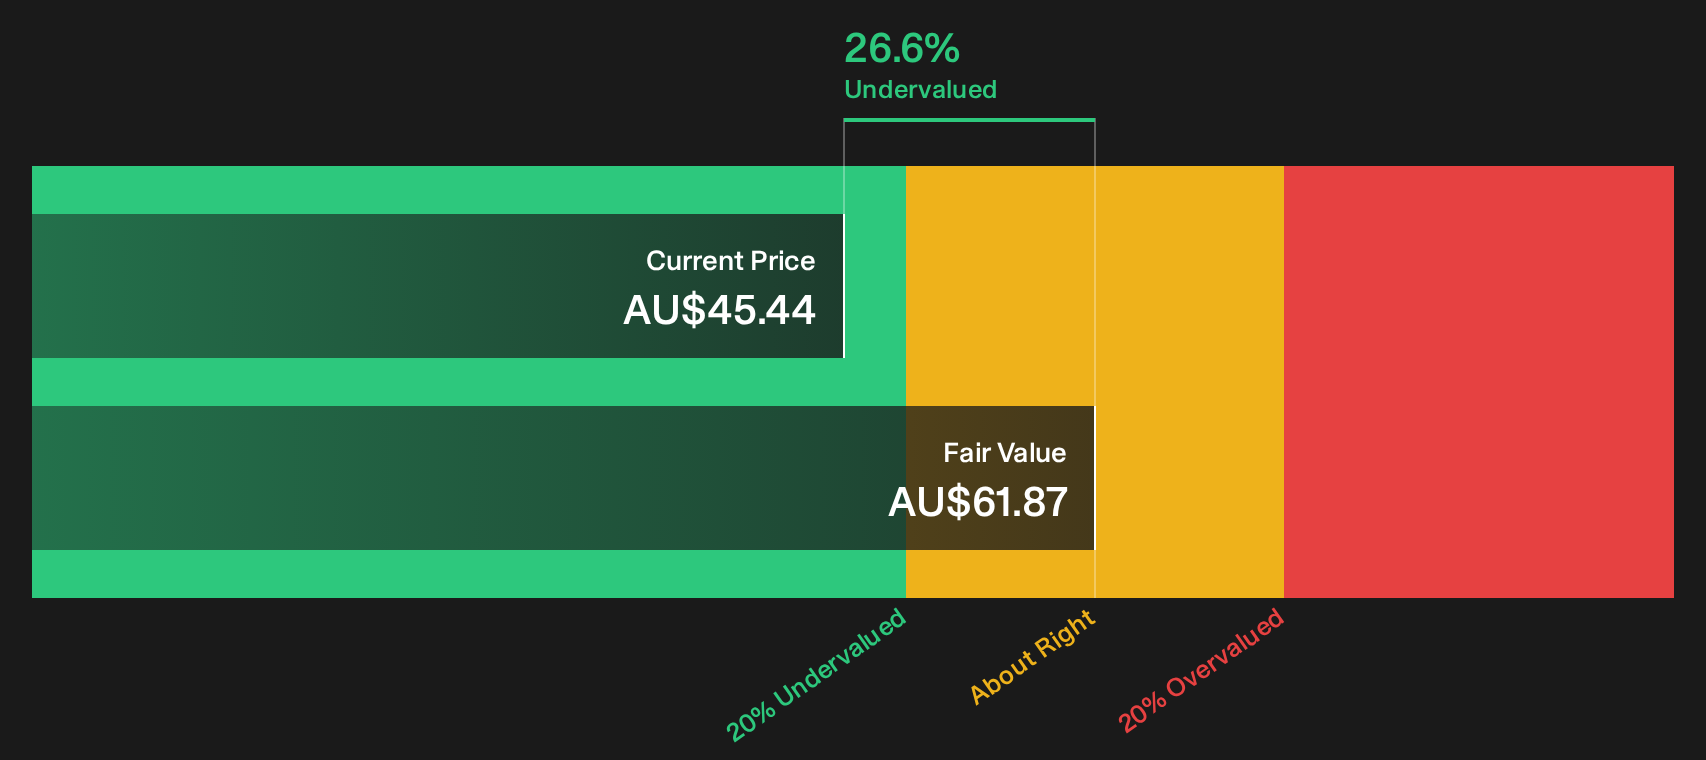
Life360 (ASX:360)
Life360 runs a family safety and location platform where paid tiers and add-ons turn user engagement into recurring subscription cash flows. This is exactly what this cash flow focused screen is trying to surface. The business reports about $573 million from Software & Programming and has a market value near A$5.1b.
Investors looking for recurring, subscription driven cash flows backed by a large user base may find Life360 an interesting fit for this undervalued cash flow screen, especially as its ecosystem broadens beyond pure tracking into wider household services.
"New premium services and integrated hardware (e.g., unified Tile and forthcoming GPS pet tracker) deepen Life360's value proposition, increase member engagement, and create higher conversion to paid tiers. These ecosystem enhancements reinforce recurring revenue growth and are likely to further expand net margins over time as premium offerings scale."
The real swing factor is how one subtle shift in user behaviour shapes the balance between recurring subscription strength and future margin resilience.
That shift is exactly what the full narrative for Life360 spells out, showing where Life360’s subscription momentum could accelerate, stall, or quietly decouple from headline sentiment.

Seeking Fresh Alternatives Beyond Today?
Markets move fast. Fresh opportunities can turn into crowded trades once momentum catches on and prices start flying. Scan what others might miss while it matters. Act now.
- Spot potential yield workhorses before income hunters crowd in by scanning 4 dividend fortresses, designed to surface high-payout candidates with staying power.
- Track potential AI momentum plays early by running 41 profitable AI stocks that aren't just burning cash, which filters for businesses already converting excitement into real earnings.
- Hunt for possible future infrastructure winners by reviewing 41 power grid technology and infrastructure stocks, focused on grids, hardware, and technology supporting rising electricity demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com