


EN
Should Weak Q3 Results Require Action From Enphase Energy (ENPH) Investors?
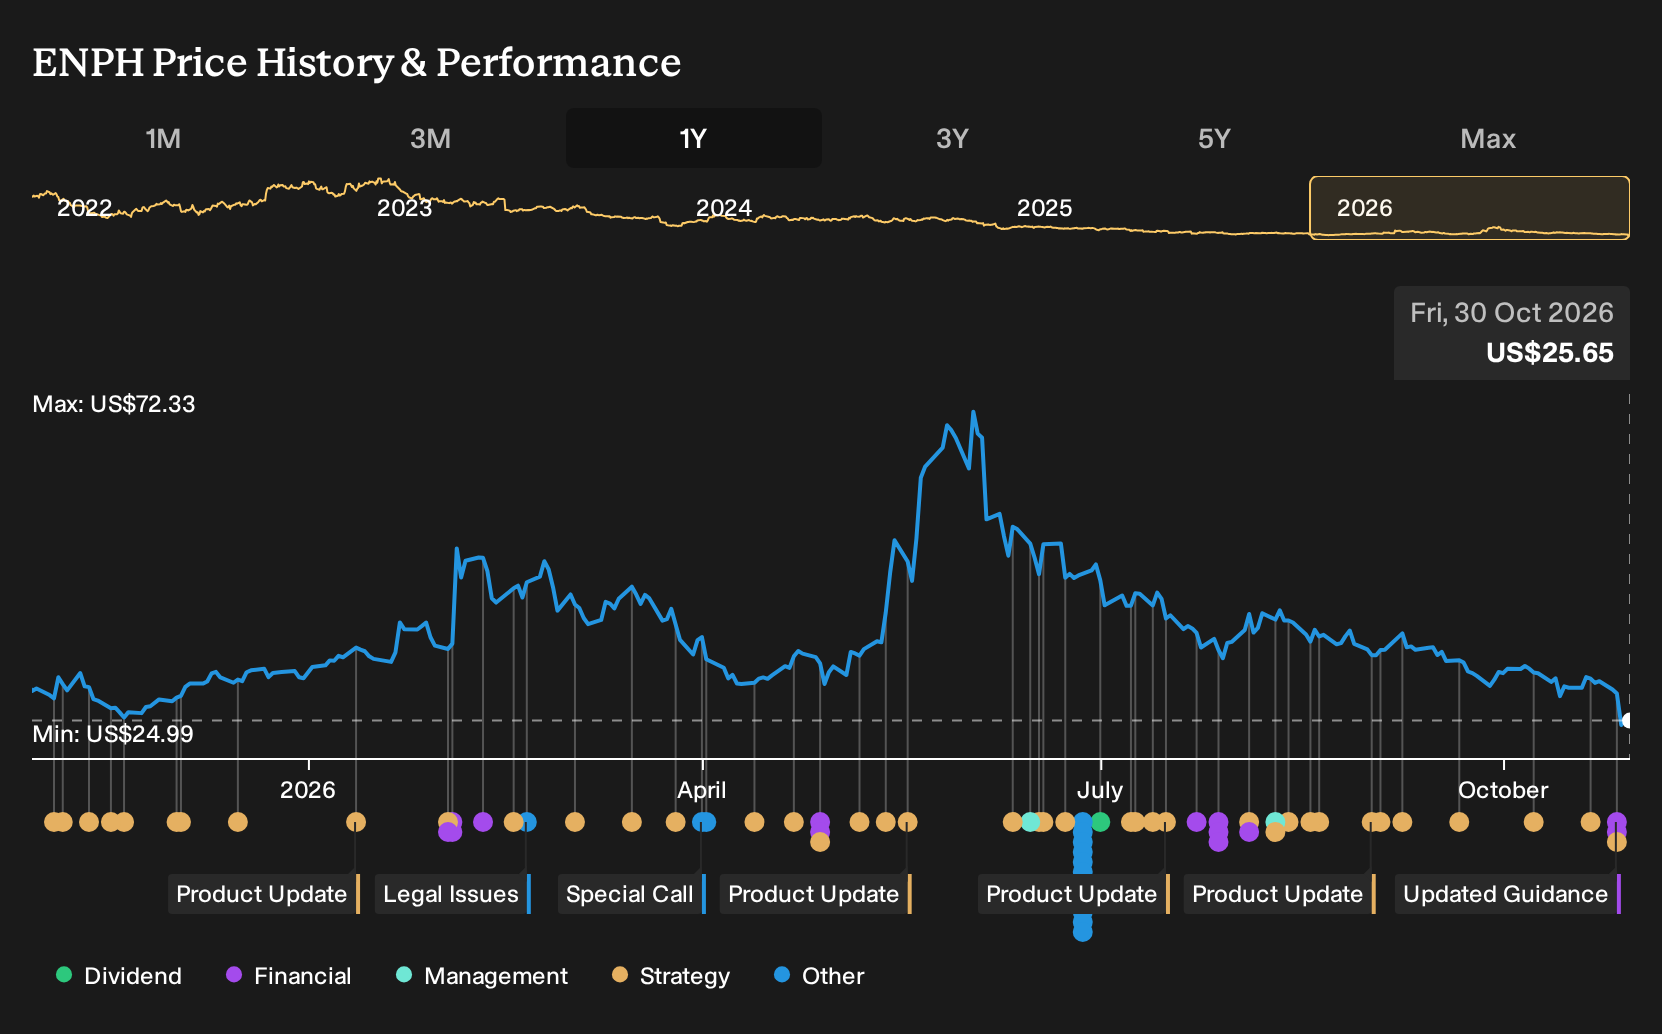
- Enphase Energy reported third quarter 2026 basic earnings per share from continuing operations of US$0.18, down from US$0.51 a year earlier, and issued cautious fourth quarter revenue guidance of US$225 million to US$255 million.
- The company paired weaker near term profitability with longer dated projects such as its IQ Solid-State Transformer and EU-ready IQ EV Charger 2, which highlights a tension between current market pressure and future product ambitions.
- This article examines how Enphase Energy's investment narrative is affected by weaker third quarter earnings together with cautious revenue guidance.
Scan beyond Enphase Energy and size up other power-grid and electrification players with the curated 41 power grid technology and infrastructure stocks that could benefit if AI data centers and EV charging keep demanding more capacity.
Enphase Energy Investment Narrative Recap
For an investor to stay with Enphase Energy, the belief has to be that residential solar and home energy systems remain a long term story while the business works through a downturn. The sharp fall in basic EPS, from US$0.51 to US$0.18 in Q3 and from US$1.02 to US$0.39 over nine months, underlines how tough the near term is. The key near term catalyst is any stabilisation in U.S. residential demand and channel sell through. Near term earnings softness and cautious Q4 revenue guidance keep that catalyst unresolved.
The biggest current risk is that a weaker market and pricing pressure keep profit margins under strain even if volumes stop falling. Tariffs, price cuts and the phase out of the 25D tax credit were already pressuring profitability, and the latest EPS figures show that margin compression is not yet easing. If residential demand stays subdued and Europe adds legal and competitive friction, Enphase Energy may find it harder to translate its product roadmap into higher earnings.
The IQ Solid State Transformer announcement is the most relevant operational update, because it connects directly to a possible new earnings driver beyond rooftop solar. Enphase Energy has shown lab level 13.8 kV AC to 800 VDC conversion with 132 power modules working in concert, using components and processes related to its IQ Microinverters. That matters because it extends the firm’s power electronics know how into medium voltage and data center style loads.
For catalysts, IQ SST targets high power applications such as AI compute racks where power efficiency and reliability are central. Management is already building IQ SST modules in Arlington, Texas, with megawatt scale racks targeted before the end of 2026 and customer pilots planned for 2027. Execution risk remains high, since this is a new category with different buyer dynamics, reliability requirements and competitors, yet successful pilots could gradually diversify Enphase Energy away from its most cyclical residential exposure.
What The Enphase Energy Consensus Is Pricing In
Analysts currently plug modest top line assumptions into the Enphase Energy model, with revenue expected to grow by 2.5% per year over the next 3 years. Earnings today are put at US$134.0 million, with consensus pointing to US$235.8 million by 2029, which implies an earnings increase of about US$101.8 million on that timeline. Those same estimates translate into implied 2029 revenues of US$1.4b and a move in profit margins from 10.1% today to 16.5% in 3 years, supported by a forecast P/E of 39.7x in 2029 compared with 30.9x currently.
Discover why Enphase Energy's fair value indicates a 92% potential upside to its current price, which could materialize sooner than many investors expect.
Exploring Other Perspectives
For Enphase Energy, the bullish twist revolves around IQ SST. The most optimistic analysts were pencilling in 7.3% annual revenue growth and earnings of about US$359.9 million by 2029, helped by medium voltage and AI data center exposure. Those projections were set before this earnings miss and cautious guidance, so you should expect some of those narratives to evolve and compare several viewpoints for yourself.
Explore 5 other Enphase Energy fair value estimates, including one that suggests as much as 362% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enphase Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enphase Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enphase Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Enphase Energy?
Once you have formed a view on Enphase Energy, it can help to widen the lens and compare it with other businesses that offer different balances of risk, quality and income. The Simply Wall St Screener gives you a curated way to do that, so you can line up several potential opportunities and see which ones really fit your goals.
- If capital preservation is a priority, start with sturdier businesses by checking out a 29 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors hunting for mispriced quality, scan through a 33 high quality undervalued stocks that combine solid fundamentals with more attractive pricing.
- If you want resilience backed by strong finances, filter for companies from a list of solid balance sheet and fundamentals (24 results) and compare how they stack up against Enphase Energy on core metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com