


EN
OPEC+ kept its December production target unchanged as scheduled. Setting the framework for next year on November 29 is a major test
The Zhitong Finance App learned that seven member countries in the OPEC+ (OPEC+) oil producer group have agreed to keep production quotas unchanged in December. Previously, these seven countries had already completed the final round of voluntary production cuts in September.
Although oil transportation through the Strait of Hormuz is picking up and Saudi Arabia's alternative export routes via the Red Sea increased in October, OPEC+ Persian Gulf member states are still limited in their ability to take advantage of higher production targets.
Following the meeting held on Sunday, the seven countries' production targets for December are shown in the table below (unit: 1,000 barrels/day), with each country's actual production in September — September is the most recent month in which OPEC published estimates through second-hand sources.
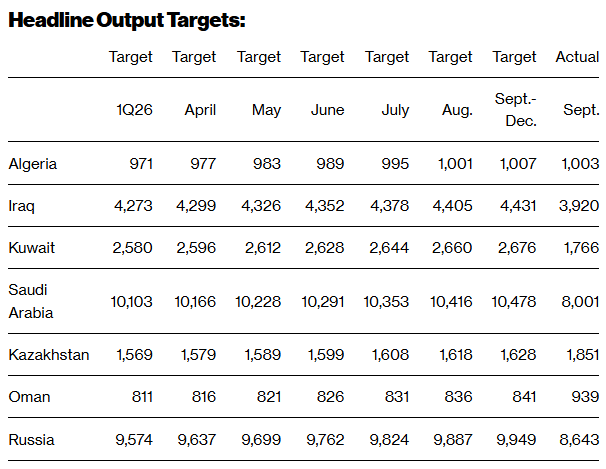
The seven countries will continue to meet monthly to assess market conditions, and the next meeting is scheduled for November 29, the same date as the OPEC+ plenary meeting.
The table above does not reflect additional production cuts made by Kazakhstan and Oman to make up for previous overproduction. The most recent revision of such “compensatory production cuts” was on April 7, in which Kazakhstan's effective production quota was cut by more than half, to only 710,000 b/d in May and 720,000 b/d in June. Oman's compensatory production cuts were minor, and its targets were lowered to 812,000 b/d in May and 806,000 b/d in June.
The period to make up for past overproduction has been extended until the end of the year, but up to now, compensatory production cuts after June have not been announced.
Oil price performance
On the trading day before this meeting (Friday, October 30), oil prices had just experienced a round of jumps. Brent's December contract settlement price was $117.64 per barrel, up 2.40%, hitting an intraday high of $118, a record high since April; the more active January contract rose $2.63 to $113.43 per barrel. WTI's December contract rose by $2.12, or 2.08%, to $104.12 per barrel. Statistics show that WTI climbed 0.82% and Brent rose 0.79% throughout the week, both rising for the sixth consecutive week.
Looking at the monthly outlook, October was a rare month of sharp increases in oil prices: WTI's main force rose 15.15% month on month, and Brent rose 13.63% month on month. The upward drive was attributed to a geopolitical premium — traders preparing for a possible escalation of the war in Iran after the US midterm elections. Middle East crude oil exports rose to 18.756 million b/d in September and maintained 17.588 million b/d in October, but US strategic oil reserves fell to 283 million barrels at the end of October, and the buffer space narrowed.
On the first trading day after the meeting (Monday, November 2), oil prices fell back in early Asian trading. Brent crude fell about 1.7% to around $111.60 a barrel.
What the decision means for oil prices
The first level is “no accident.” Maintaining the quota is within market expectations, so it does not in itself constitute an additional price signal. Jorge Leon, an analyst at Rystad Energy (Rystad), said bluntly that “today's decision is relatively simple” and did not give the market a signal that exceeded expectations; the real big test was the full ministerial meeting on November 29, which will determine the 2027 production framework.
The second level is the gap between paper quotas and actual exportable volumes. The quantitative meaning of “the ability of Persian Gulf member states to take advantage of higher production targets is still limited”: According to the International Energy Agency's September report, the total production of the larger group of 18 countries was 27 million b/d, while the total target was 34.27 million b/d, with a gap of more than 7 million barrels; production capacity of more than 10 million b/d in the Gulf region was shut down. In seven countries, second-hand data shows a total production volume of 24.3 million b/d in July, with a quota of 30.6 million b/d. As long as shipping in the Strait of Hormuz is not liberalized, it will be difficult to convert any quota adjustments into physical increases — this means that short-term price flexibility in quota news is limited, and physical supply depends on waterways rather than meetings.
The third tier is excess risk and asymmetric pricing in 2027. Seven countries completed the withdrawal of the 2023 round of voluntary production cuts of 1.65 million b/d in September, and another level of production cuts covering most member countries and about 2 million b/d was implemented until the end of 2026; before setting the 2027 benchmark, it is necessary to complete the production capacity assessments of member countries in the fourth quarter, and results are expected in mid-November. Agencies such as the International Energy Agency have warned that if supply normalizes in the Gulf, there may be an oversupply in 2027. For crude oil, this poses an asymmetric risk: disruptive news supports near-term monthly differences, and once normalization is implemented, the geopolitical premium will be compressed before the excess is reflected in actual production data.
UBS strategist Giovanni Staunovo said that although traffic in the Middle East is improving, it has not yet been fully normalized. According to Kpler data, as of September, crude oil flows through the region were about 44% of pre-war levels. Furthermore, the Islamic Revolutionary Guard Corps of Iran claimed on Sunday that two tankers hit and exploded by lightning while crossing the strait without their authorization. This claim has not been independently verified.