


EN
Marubun (TSE:7537) Stock Slides Despite Strong Q2 Earnings Growth
Marubun just dropped its Q2 2027 scorecard and the numbers hit harder than the share price suggests. The stock closed at ¥1,780 on 30 October, with the recent 7 day slide of about 4.6% and 30 day drop of about 5.4% looking out of step with a solid earnings run. Basic earnings per share for the quarter came in at ¥86.58 on revenue of ¥56,449 million, anchoring trailing earnings growth of 63.5% over the past year. That is a sentiment mismatch the market will eventually have to resolve.
Love Marubun’s strong trailing earnings run but unsure whether this pullback is giving you the right kind of opportunity and risk balance? Benchmark it against our curated list of resilient stocks with stronger fundamentals using the list of solid balance sheet and fundamentals stocks (22 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥56,449 million vs. ¥52,813 million (up about 6.9%)
- Net Income (Q2 2027 vs. Q2 2026): ¥2,273 million vs. ¥360 million (very large year-on-year increase)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥86.58 vs. ¥13.75 (very large year-on-year increase)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 2.3% vs. 1.4% (margin improved)
Earnings jumped faster than forecasts suggest they will from here. Ask Charlie what makes Marubun look this undervalued now.
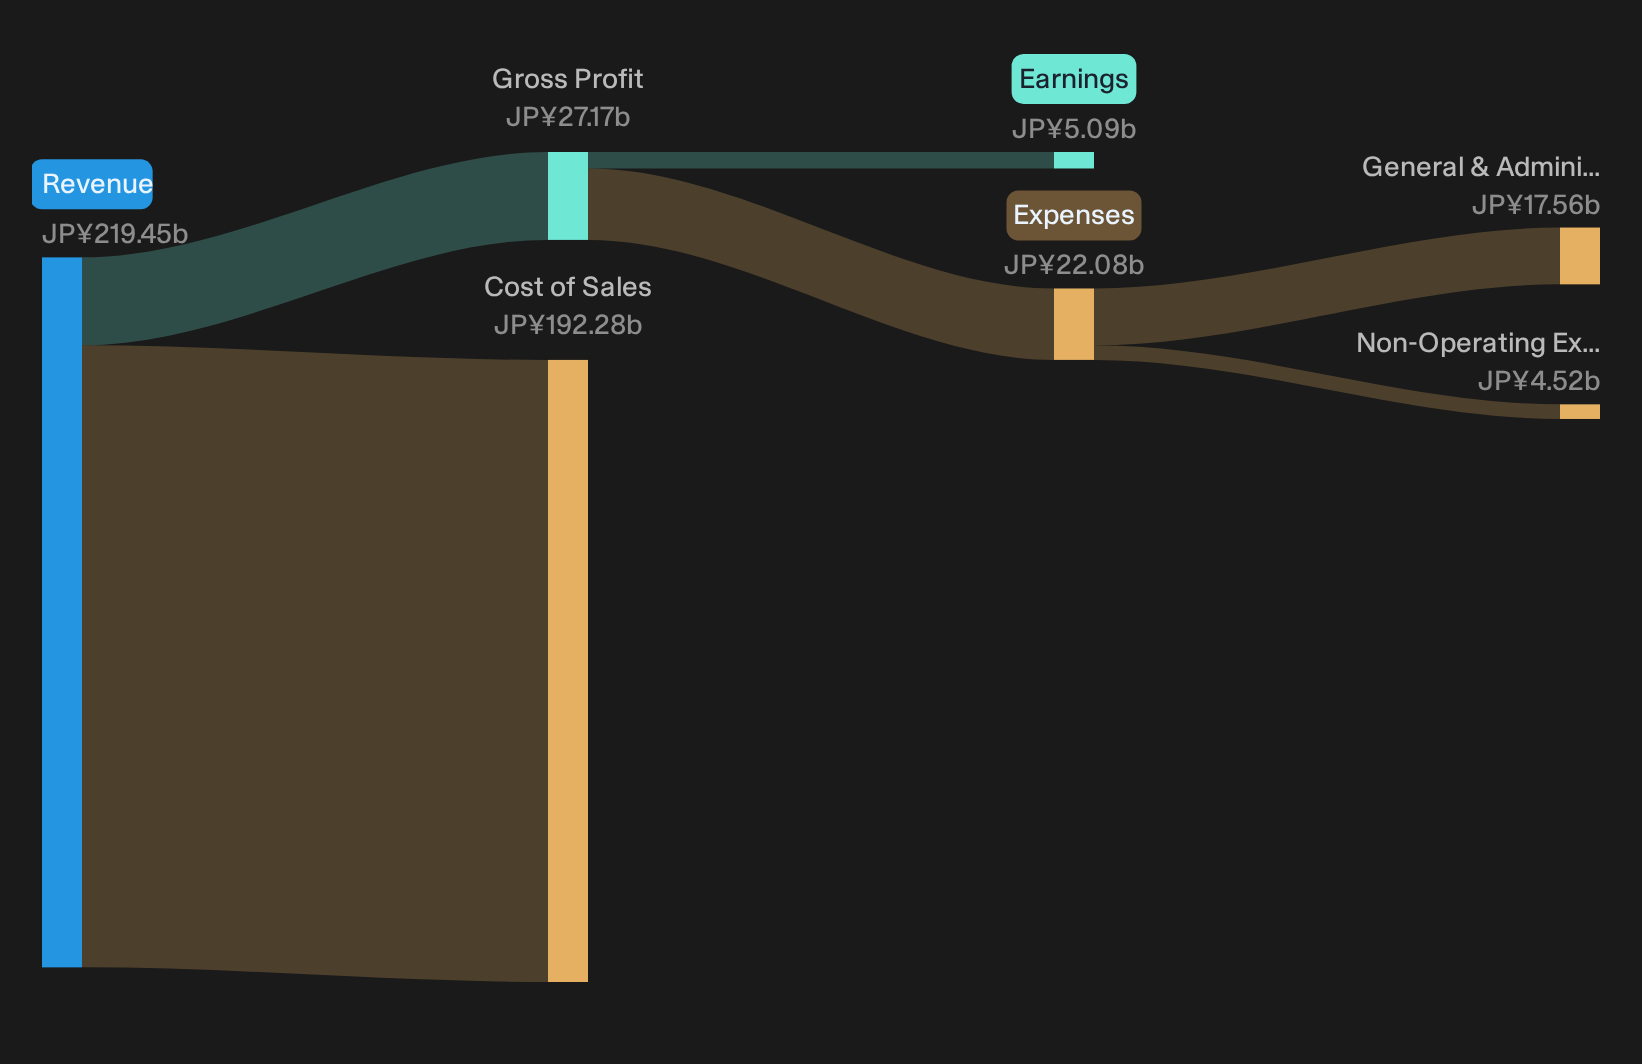
Marubun earnings, where the bullish story holds
For a distributor that is often seen as low margin and cyclical, Marubun just printed numbers that back a constructive view. Revenue in Q2 rose to ¥56,449 million while net income and EPS moved sharply higher year on year. Profitability on a trailing basis improved, with net margin at 2.3% versus 1.4%. That kind of uplift hints that the diversified technology enabler story is tracking with the income statement, at least for now.
Marubun risks, what the latest quarter does not answer
The flip side is that higher earnings do not settle the usual concerns about a distributor model. Even with better margins, this remains a low margin electronics middleman that can feel inventory swings quickly. Recent share price weakness over 7 and 30 days shows investors are not treating one strong half as a new baseline. For now, the financial trend softens the bearish case on near term earnings pressure, but it does not remove it.
After a quarter where Marubun lifted earnings while the share price slid, it is fair to ask whether margin pressure, volatile trading and an uneven dividend record are early warning signals or just noise. Review the full risk analysis for Marubun which shows 2 important warning signsHunt For Quiet Balance Sheet Upside
Marubun just showed how earnings strength and share price pressure can pull in different directions. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - expands a maintenance-focused sales force to secure recurring contracts and deepen route density.
- Company 2 - 45% below our estimate - pushes an AI-first security platform so more subscription clients consolidate core protection spending in one bundle.
- Company 3 - 35% below our estimate - scales AI hiring tools that convert job postings and local services searches into performance-linked matching contracts.
Those are three of them. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com