


EN
What Zigup Buyers Were Betting On
If Zigup sat on a watchlist rather than in a portfolio, the result over this stretch may feel like an avoidable miss. Holding Zigup from the start of the year would have returned 26.3%, including dividends. That outcome now raises a sharper question. Back on 1 January 2026, with urbanization, e-commerce demand, and heavy digital platform spending all at record levels, what specific belief about logistics efficiency would have helped you treat this as an opportunity rather than just another cyclical rental business?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Zigup. Zero in on 14 high quality undervalued stocks for companies trading below our estimates.
The Two Zigup Stories Investors Had To Weigh
The shares cost £3.83 at the start of the period, and you had to choose which story about Zigup felt more realistic.
On the bullish side, one Narrative suggested a Fair Value of £4.76, 24% above the start price. That view leaned on digital platforms, fleet upgrades, and new partnerships supporting efficiency and recurring revenue.
The bearish Narrative pointed to a Fair Value of £3.50, 9% below the start price. It focused on heavy fleet and technology CapEx, higher leverage, and the risk that replacement spending could keep cash generation tight for years.
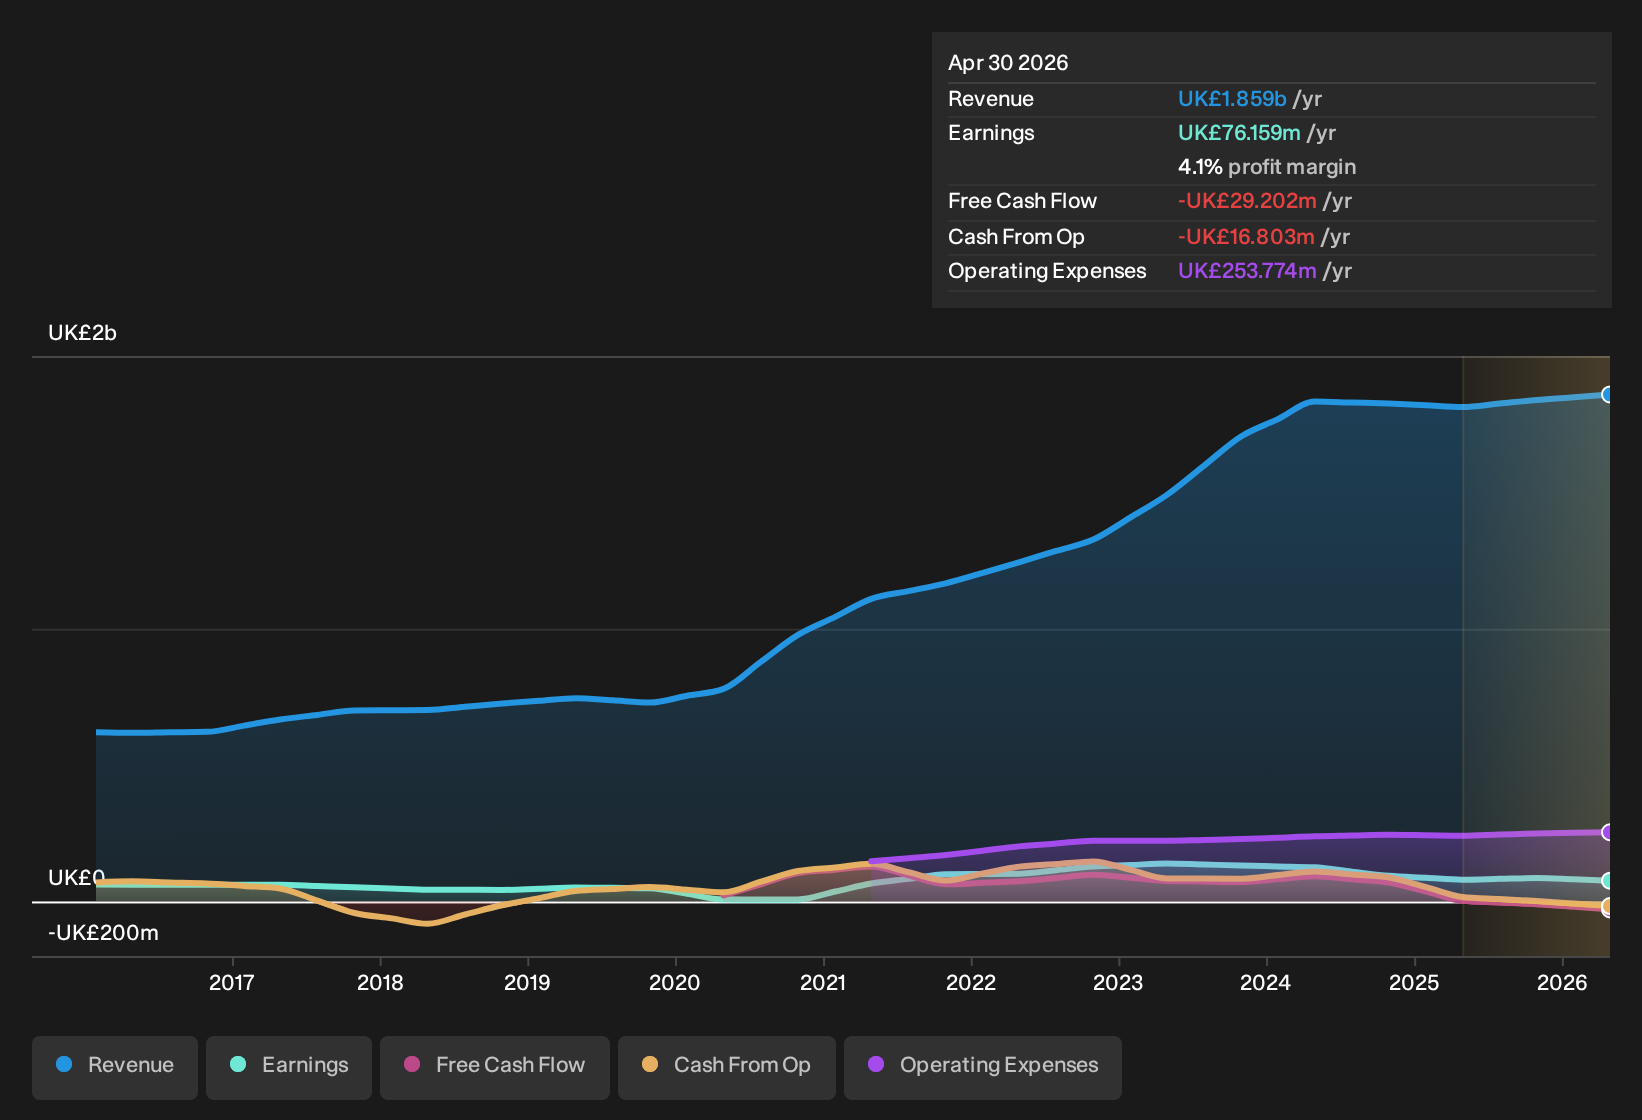
What The Results Changed For The Zigup Debate
The H2 2026 numbers did the heavy lifting. Zigup reported revenue of £929.285m versus £909.005m in H2 2025, which supported the growth angle from the optimistic case. Net income fell to £26.581m from £36.428m and net margin moved from 4.0% to 2.9%. That profitability squeeze, even on a larger top line, kept the cautious story very much alive.
For another stock, treat this as a reminder to test any efficiency claim against net margin, not just headline sales. If the thesis leans on better logistics or tech, track whether profit per pound of revenue is actually improving in subsequent reports.
What Zigup's Current Price Already Assumes
Zigup now trades at £4.61, up from £3.83 from the start of the year. The selected Narrative still places its Fair Value below that level, framing today’s quote as already baking in meaningful execution on margins and cash generation.
The core question for you is what must keep going right for that price to hold. A buyer today would be assuming Zigup converts heavier fleet investment and technology spending into lasting EBIT margin gains and steady cash, while funding costs and lower disposal profits do not erode that progress.
"Bearish analysts expect Zigup's heavy investment in fleet, technology, and facilities to keep pressure on margins and slow the translation of higher rental revenue into strong steady-state cash generation, while vehicle disposal profits normalize and financing costs reflect a larger fleet. The main thing that has to go right is that Zigup converts its shift toward higher rental revenue, long term contracts, simplification savings, and technology and AI deployment into sustained EBIT margin improvement and higher steady-state cash, while keeping leverage within its 1 to 2x target range."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 28% below our estimate - uses a single tech stack and AI tools to handle rising inflows efficiently.
- Company 2 - 32% below our estimate - raises capital into renewable and infrastructure vehicles that charge fees on long-lived assets.
- Company 3 - 18% below our estimate - scales new production capacity to meet sports nutrition demand via retailers and distributors.
Those are three of them. See the full list of 10 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com