


EN
NGK (TSE:5333) Stock Slips As Q2 Earnings Strength Fails To Shift Doubts
NGK closed at ¥4,613 on 30 October, capping a choppy month that left the stock down about 18% over 30 days even as fresh Q2 2027 figures hit the tape. The main takeaway is that profitability kept climbing while the share price looked tired.
Basic earnings per share for the quarter came in at ¥111.45, with net income of ¥31,426m on revenue of ¥187,159m. That kind of earnings power can be especially important for a specialty ceramics manufacturer whose value is increasingly tied to multi year cash flow models rather than short term price swings.
Like the earnings profile at NGK but uneasy about a share price that just dropped 18% in a month? Take a look at our list of peers with strong cash generation and sturdier recent trading in the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥187,159m vs. ¥159,746m (up about 17%)
- Net Income, Excl. Extra Items (Q2 2027 vs Q2 2026): ¥31,426m vs. ¥5,971m (very large increase, more than 5x)
- Basic EPS (Q2 2027 vs Q2 2026): ¥111.45 vs. ¥20.44 (very large increase, more than 5x)
- Net Profit Margin, Trailing 12 Months (current vs prior year): 13.5% vs. 8.2% (meaningful margin improvement over the year)
Ask Charlie what NGK’s profit jump means for future growth.
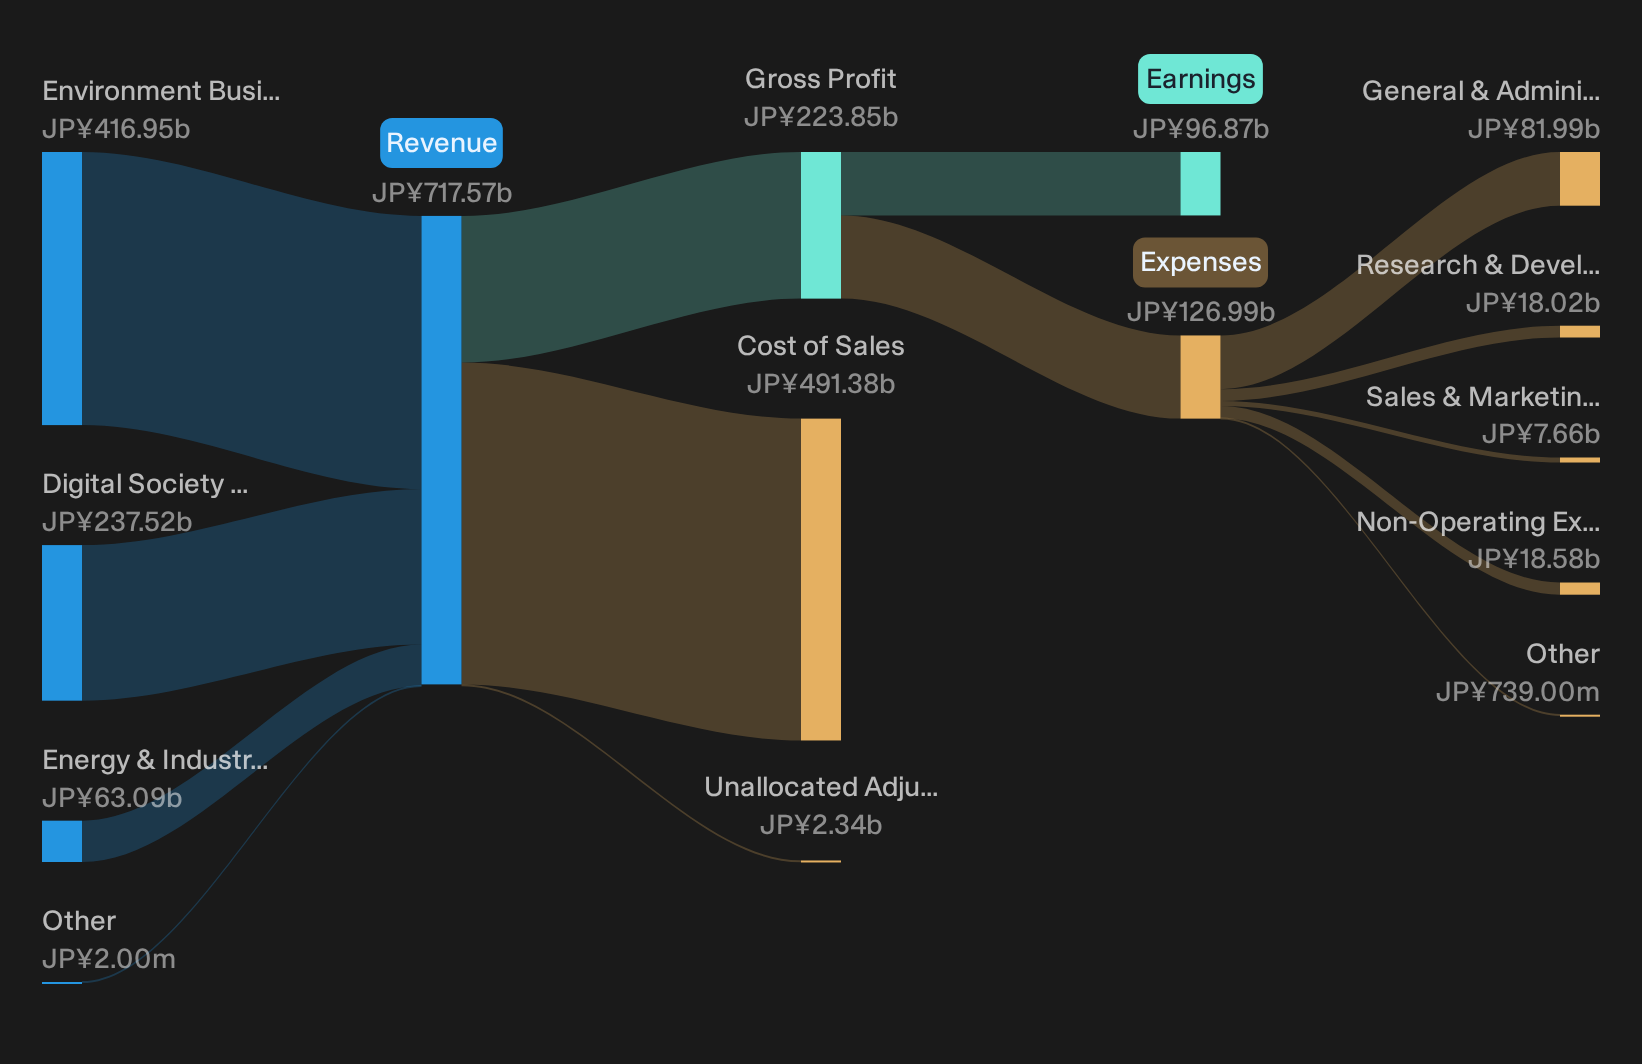
NGK earnings give bulls real support
For anyone leaning positive on NGK, the story now rests on earnings power rather than hope. Revenue of ¥187,159m and net income of ¥31,426m line up with a much stronger profit engine than a year ago, with basic EPS at ¥111.45 and a trailing margin of 13.5%. That margin level matters for a ceramics producer tied to autos, electronics, and infrastructure, because it suggests the multi segment model is converting sales into cash flow, which fits the longer term environmental and grid exposure pitch.
Recent share slide still feeds the worriers
Bears are not out of material. The stock has fallen about 18% over 30 days and 17% over 90 days even as Q2 2027 earnings improved, which indicates that investors remain cautious on cyclically exposed suppliers. A better 13.5% trailing margin against last year’s 8.2% helps counter fears about structural weakness, so near term selling appears more like doubt about sustainability than proof of a broken business. For now, the financials indicate that immediate risks to NGK’s basic profit engine are contained, even if sentiment disagrees.
After a slide like this, strong earnings results can sometimes hide weaker areas in the overall picture. Review NGK’s full risk scorecard and uncover potential blind spots in the risk analysis for NGK which shows 2 important warning signs.Hunt For Strong Balance Sheets
NGK just showed how earnings strength and a sliding share price can pull in different directions. The real opportunity sits in finding stocks that could be low debt before the market fully cares.
- Company 1 - 35% below our estimate - uses AI tools to align hiring demand with job ads and performance-based fees.
- Company 2 - 18% below our estimate - expands a maintenance-focused sales force to secure recurring contracts from modernisation work.
- Company 3 - 45% below our estimate - directs spending into an AI-native security platform turning subscription renewals into recurring revenue.
Those are three of them. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com