


EN
Coca-Cola Bottlers Japan (TSE:2579) Q3 Earnings Revive Profitability As Sales Slip
Coca-Cola Bottlers Japan entered this Q3 2026 earnings print with its share price at ¥3,870 and a flat 90 day return that suggested investors were undecided. The release then landed with a jolt. Basic earnings per share jumped to ¥91.96 for the quarter and net income reached ¥14,845m, a clear break from the losses seen as recently as early 2025.
The stock reaction around the result told only part of the story. The real headline was margin repair, helped by price increases and cost discipline. This turned a low growth beverage distributor into a profitability story again.
Love the earnings rebound at Coca-Cola Bottlers Japan Holdings but still uneasy about whether this is a durable reset in profitability or just a short burst of margin repair? Use our screener of list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): ¥250,744m vs. ¥265,581m (decline of 5.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): ¥14,845m vs. ¥17,158m (decline of 13.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥91.96 per share vs. ¥101.42 per share (decline of 9.3%)
- Trailing 12 Month Revenue (Q3 2026 TTM vs. Q3 2025 TTM): ¥884,217m vs. ¥899,592m (decline of 1.7%)
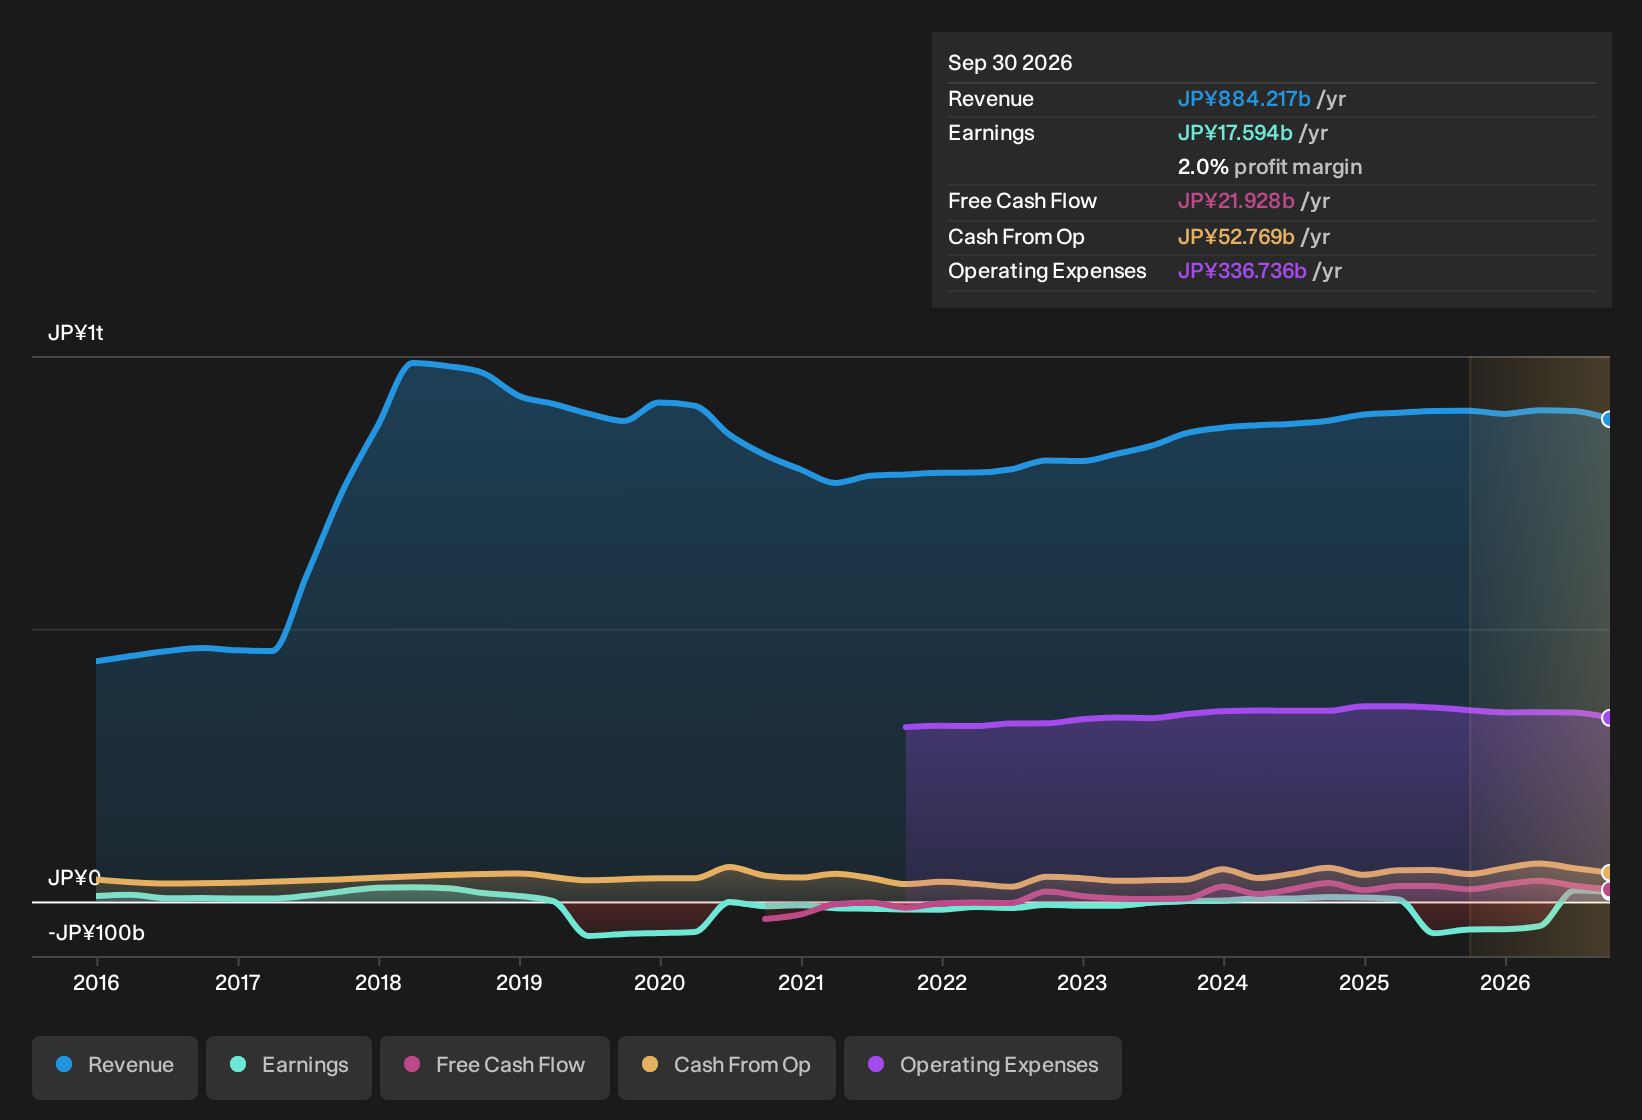
Coca-Cola Bottlers Japan: Pricing Playbook On Trial
The bullish story hangs on Coca-Cola Bottlers Japan turning pricing power and cost programs into steadily higher business income and richer shareholder payouts.
"Bullish analysts expect Coca-Cola Bottlers Japan Holdings to use pricing power, category mix and cost savings to keep lifting business income from the levels reached in 1H 2026 while returning more cash to shareholders through buybacks and dividends."
Q3 progress lines up with that script. Business income year to date is higher despite softer revenue and lower volumes, helped by unit price gains of ¥12.1b and about ¥4.1b of transformation benefits. Segment profit in vending and OTC also moved ahead even as volume slipped. Buybacks of ¥30b are completed, and a new ¥40b program together with a 20% dividend increase show that the capital return leg is being executed as advertised.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Coca-Cola Bottlers Japan: Pricing Power Meets Volume Strain
Bears argue Coca-Cola Bottlers Japan is leaning too hard on repeated price hikes in a shrinking drink market, inviting a slow squeeze on future earnings power.
"The company is leaning heavily on repeated price revisions, including the 9th increase since 2022 and a further focus on pricing in 2026. This approach risks hitting volume in a market that management itself describes as contracting and challenging, putting future revenue growth at risk even if wholesale revenue per case rises."
Q3 results give that concern teeth. Wholesale price per case improved, yet revenue slipped 5.6% year on year and overall volume fell, with vending down about 4%. Business income is up on unit price gains and transformation savings rather than healthier demand. That mix of higher ticket, lower throughput, and a 1.4% year-to-date revenue decline supports the cautious narrative rather than challenging it.
Hunt For Quiet Balance Sheet Strength
Coca-Cola Bottlers Japan Holdings just reminded investors how quickly a pricing story can shift. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - expands a maintenance-focused sales force so recurring elevator service contracts scale faster.
- Company 2 - 45% below our estimate - shifts security buyers onto an AI-native platform so subscription contracts deepen as workloads move into cloud environments.
- Company 3 - 35% below our estimate - sells AI-powered job and services matching so hiring budgets and commerce spending flow through performance-based fees.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com