


EN
Panasonic (TSE:6752) Stock Slips As Q2 Earnings Clash With Margin Doubts
Panasonic Holdings went into its Q2 2027 earnings with the stock under pressure, down about 22% over the past month and closing at ¥3,548 on 30 October. The fresh numbers contrast with that price weakness. Basic earnings per share reached ¥60.72, with net income of ¥141.78b in the quarter, and the trailing P/E of 25.6x now has to be weighed against a discounted share price.
For short term traders the recent slide has stung. For long term holders the bigger question is whether those earnings forecasts and the implied valuation gap still justify staying patient.
Love Panasonic Holdings’ solid Q2 earnings print but concerned that the recent 22% slide means you are stuck in a value trap rather than a value opportunity? Set a higher bar for your capital by comparing it with our 14 high quality undervalued stocks.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥2,073,606 million vs. ¥1,923,785 million (up about 7.8%)
- Net Income (Q2 2027 vs. Q2 2026): ¥141,780 million vs. ¥70,939 million (up about 99.8%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥60.72 per share vs. ¥30.39 per share (up about 99.9%)
- Trailing 12 Month Net Margin (last 12 months vs. prior 12 months): 3.9% vs. 4.0% (slight margin compression over the year)
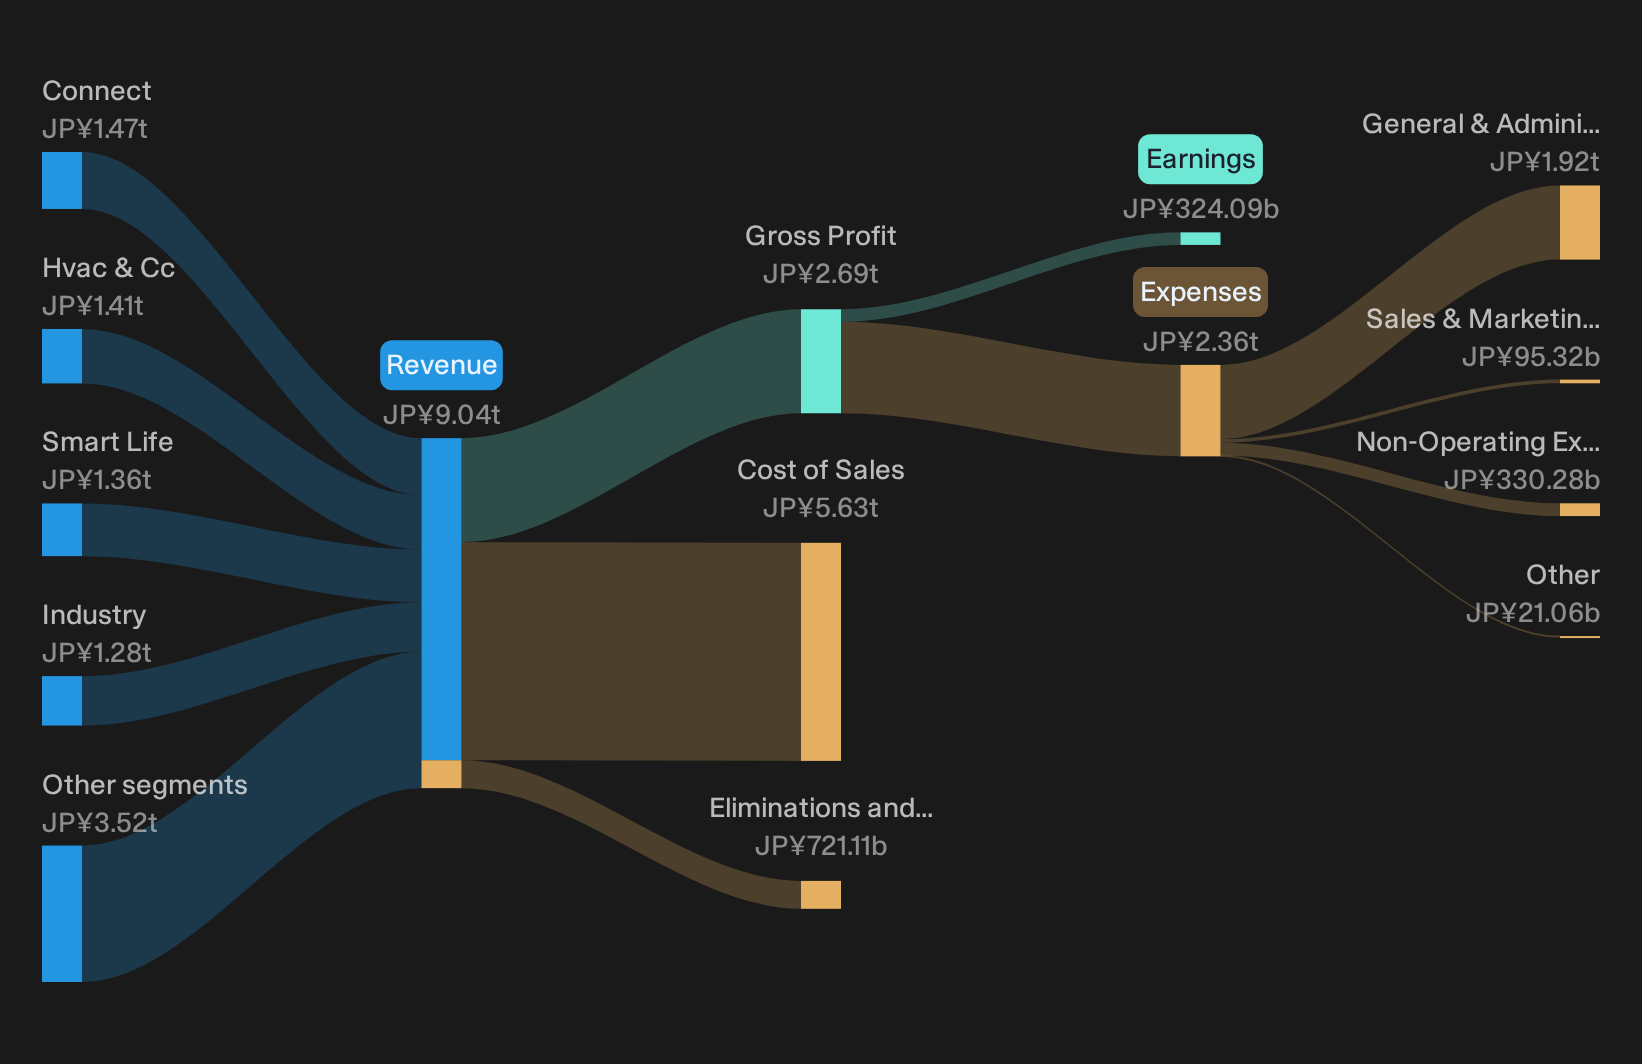
Panasonic bullish AI and cost story on trial
Optimists argue Panasonic Holdings can lean on AI and data center demand plus disciplined cost work to reshape earnings quality.
"Analysts expect Panasonic Holdings to keep using its strength in energy storage and automotive battery technology, together with continued investment in AI infrastructure and data center batteries, to build more recurring revenues and operating leverage over time."
The latest quarter shows solid profit delivery, with net income of ¥141.78b and basic EPS of ¥60.72 while the trailing net margin holds near 4%. That supports the idea of earnings power stabilising. However, the slight margin compression and recent share price slide suggest operating leverage is not yet breaking out.
Panasonic bearish execution risks under the microscope
Sceptics focus on whether Panasonic Holdings can actually translate restructuring headlines into cleaner, repeatable profitability.
"Execution Challenges in Business Portfolio and Restructuring: While the group has moved ahead with restructuring and larger-than-planned headcount reductions, there are still risks that remaining portfolio pruning, integration of acquired assets, and delivery of targeted fixed cost savings do not fully translate into sustained profitability improvements. This would pressure earnings quality and returns on equity."
Current results show earnings almost doubling year on year, yet the trailing net margin sits roughly flat and only slightly lower. That mix, together with ongoing divestments and Q2 2027 strength, suggests restructuring is helping profits today, while the margin plateau keeps the execution question firmly open.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Quiet Balance Sheet Stories
Panasonic Holdings just showed how a solid quarter can coincide with a sliding share price. The real opportunity is spotting stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - uses AI to deepen hiring and local services matching, then relies on GMV-linked fees.
- Company 2 - 45% below our estimate - builds an AI-first security platform where ARR from key products must outpace elevated spending.
- Company 3 - 18% below our estimate - expands a maintenance-focused sales force so dense customer clusters can lift productivity and reshape its revenue mix.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com