


EN
Ohsho Food Service (TSE:9936) Q2 Results Reveal A Sharper Margin Squeeze
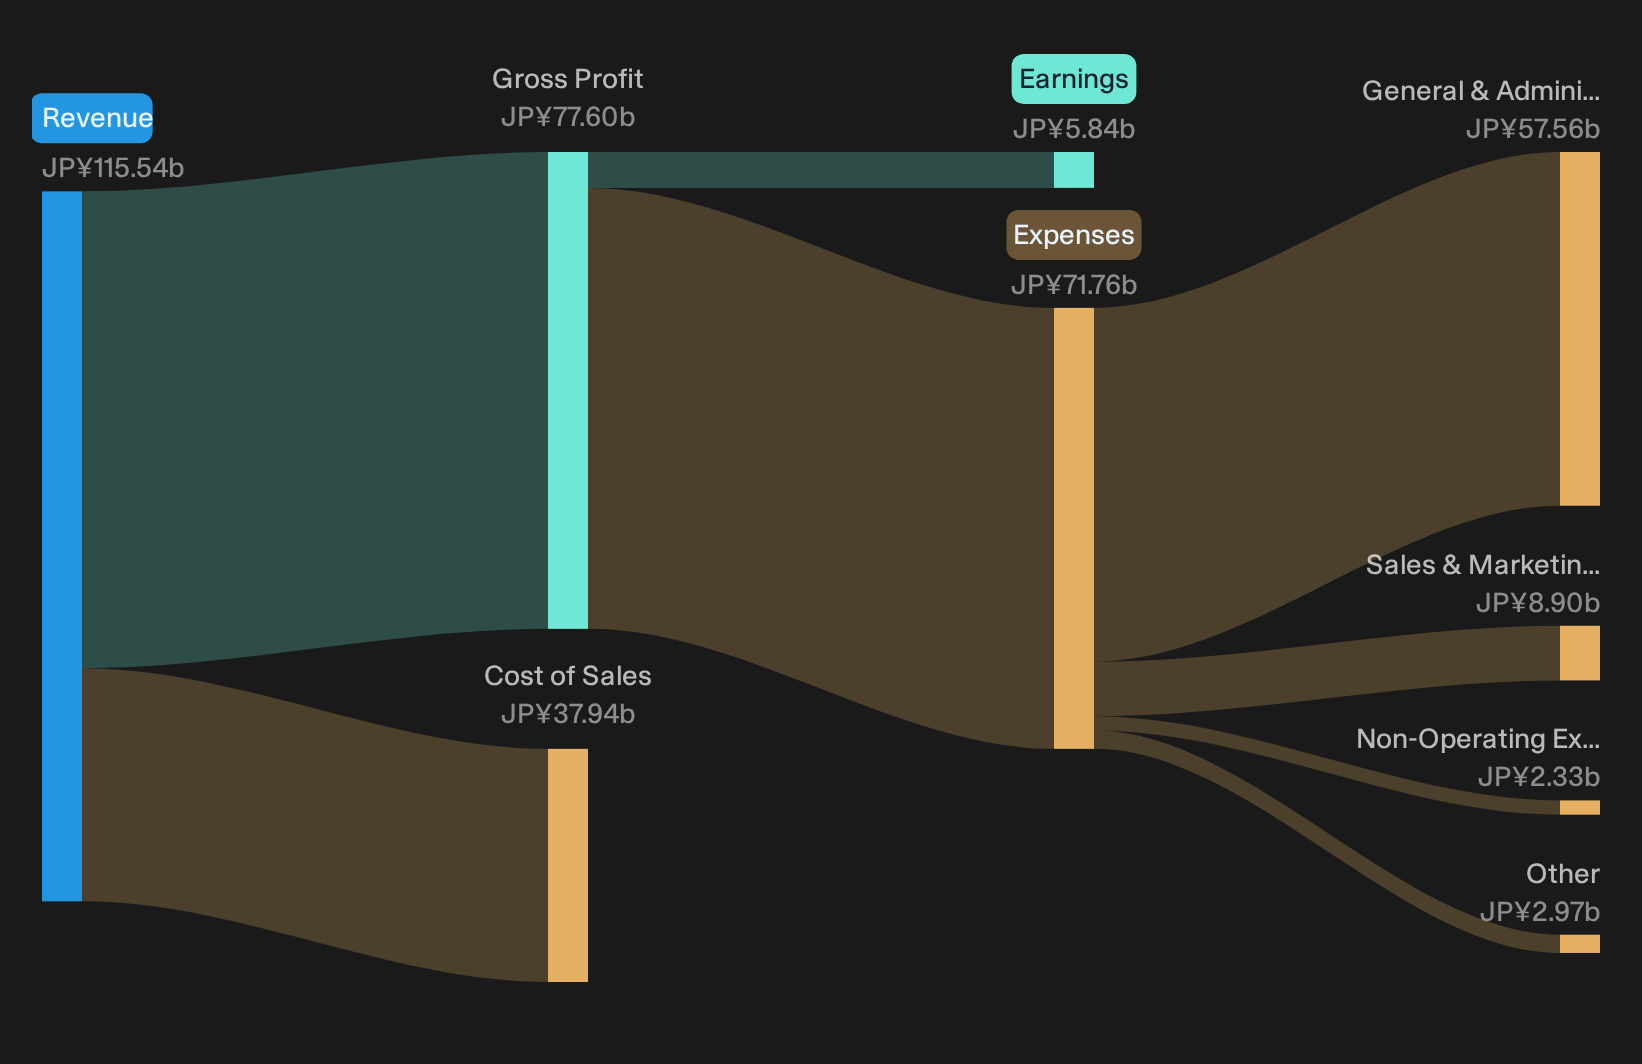
Ohsho Food Service just dropped its Q2 2027 results and the market blinked. The stock closed at ¥2,930 on the day of the release, roughly flat over the past month, even as earnings per share ticked to ¥19.69 and quarterly revenue reached ¥28,989m.
The real story is profit pressure. Trailing net margin sits at 5.1%, down from 7% a year earlier, while the shares still trade on a 26.4x P/E. That mix of squeezed profitability and premium pricing creates a tension between cautious fundamentals and investors who are still paying up for the ramen chain.
Love the steady top line at Ohsho Food Service but uneasy about paying a 26.4x P/E while margins compress. Take a look at our curated 14 high quality undervalued stocks to see how other high quality operators with firmer profitability compare with TSE:9936.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥28,989m vs. ¥28,835m (broadly flat top line)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,035m vs. ¥1,521m (profitability contracted)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥19.69 vs. ¥28.89 (earnings per share weakened)
- Trailing Net Margin (TTM, Q2 2027 vs. prior year): 5.1% vs. 7.0% (margin pressure intensified)
Ohsho’s net margin slipped from 7% to 5.1%. Ask Charlie what Ohsho’s falling margin says about future earnings.
Ohsho Food Service: Resilience In Everyday Dining
For a business built on repeat, affordable meals, the latest quarter keeps the Ohsho Food Service “defensive brand” story alive but with less comfort. Revenue of ¥28,989m is broadly in line with last year, which fits the idea of steady demand for everyday dining. Share performance over 30 and 90 days has been roughly flat, which points to investors viewing the franchise as stable rather than broken. The appeal remains a familiar chain that can still draw traffic even when profit per bowl is under pressure.
Margin Squeeze Tests The Mature Chain Narrative
The Bearish angle finds more backing in these results. Net income fell from ¥1,521m to ¥1,035m and trailing net margin compressed from 7.0% to 5.1%. That shift supports worries that a mature, competitive niche leaves limited room to offset higher costs. Earnings per share moved from ¥28.89 to ¥19.69, which reinforces the concern that operational complexity and input inflation are biting. Recent share price moves look muted rather than panicked, yet the direction of profitability clearly leans toward the cautious side of the story.
Access the analyst road map for Ohsho Food Service and see where the consensus breaks as the surface looks calm, but the models for revenue, earnings and free cash flow start to diverge in the outer years through our analyst estimates for Ohsho Food Service
Hunt Quiet Balance Sheet Outliers
Ohsho Food Service shows how a steady brand can still face profit pressure while the share price holds its ground. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - expand a maintenance-focused salesforce that targets denser customer clusters and deeper recurring service relationships.
- Company 2 - 45% below our estimate - push an AI-first security platform that turns rising cloud threats into durable subscription demand.
- Company 3 - 35% below our estimate - stitch together hiring and marketing marketplaces where AI tools guide clients toward higher-margin automated placements.
Three companies from the same screener. Open every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com