


EN
AS ONE (TSE:7476) Q2 Results Flag Margin Pressure Behind Revenue Growth
AS ONE stock closed at ¥2,576 on 30 October, fractionally weaker over the past week, just as investors absorbed Q2 2027 results. The headline figures were not about rapid growth. The main focus was pressure on profitability, with basic earnings per share at ¥26.26 and quarterly net income of ¥1,873 million, both lighter than the prior quarter.
Short term traders focused on that squeeze. Long term holders will be more interested in the trailing twelve month earnings of ¥9,579 million, which support a P/E of 18.5x and keep the valuation debate active.
If you appreciate the stability of AS ONE's trailing earnings base but are concerned about the recent profitability squeeze, consider screening for companies that combine consistent earnings with stronger margins using the list of solid balance sheet and fundamentals stocks (22 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥27,637 million vs. ¥25,775 million (up about 7.2%)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,873 million vs. ¥2,047 million (down about 8.5%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥26.26 per share vs. ¥28.56 per share (down about 8.0%)
- Trailing 12 Month Net Income (Q2 2027 vs. Q2 2026): ¥9,579 million vs. ¥8,733 million (up about 9.7%)
Earnings tell part of AS ONE's story, but investors who care about what they are paying for usually focus on the cash flowing through the business. If you run the numbers on AS ONE's cash generation alone, the stock could be a dramatic 36% undervalued.
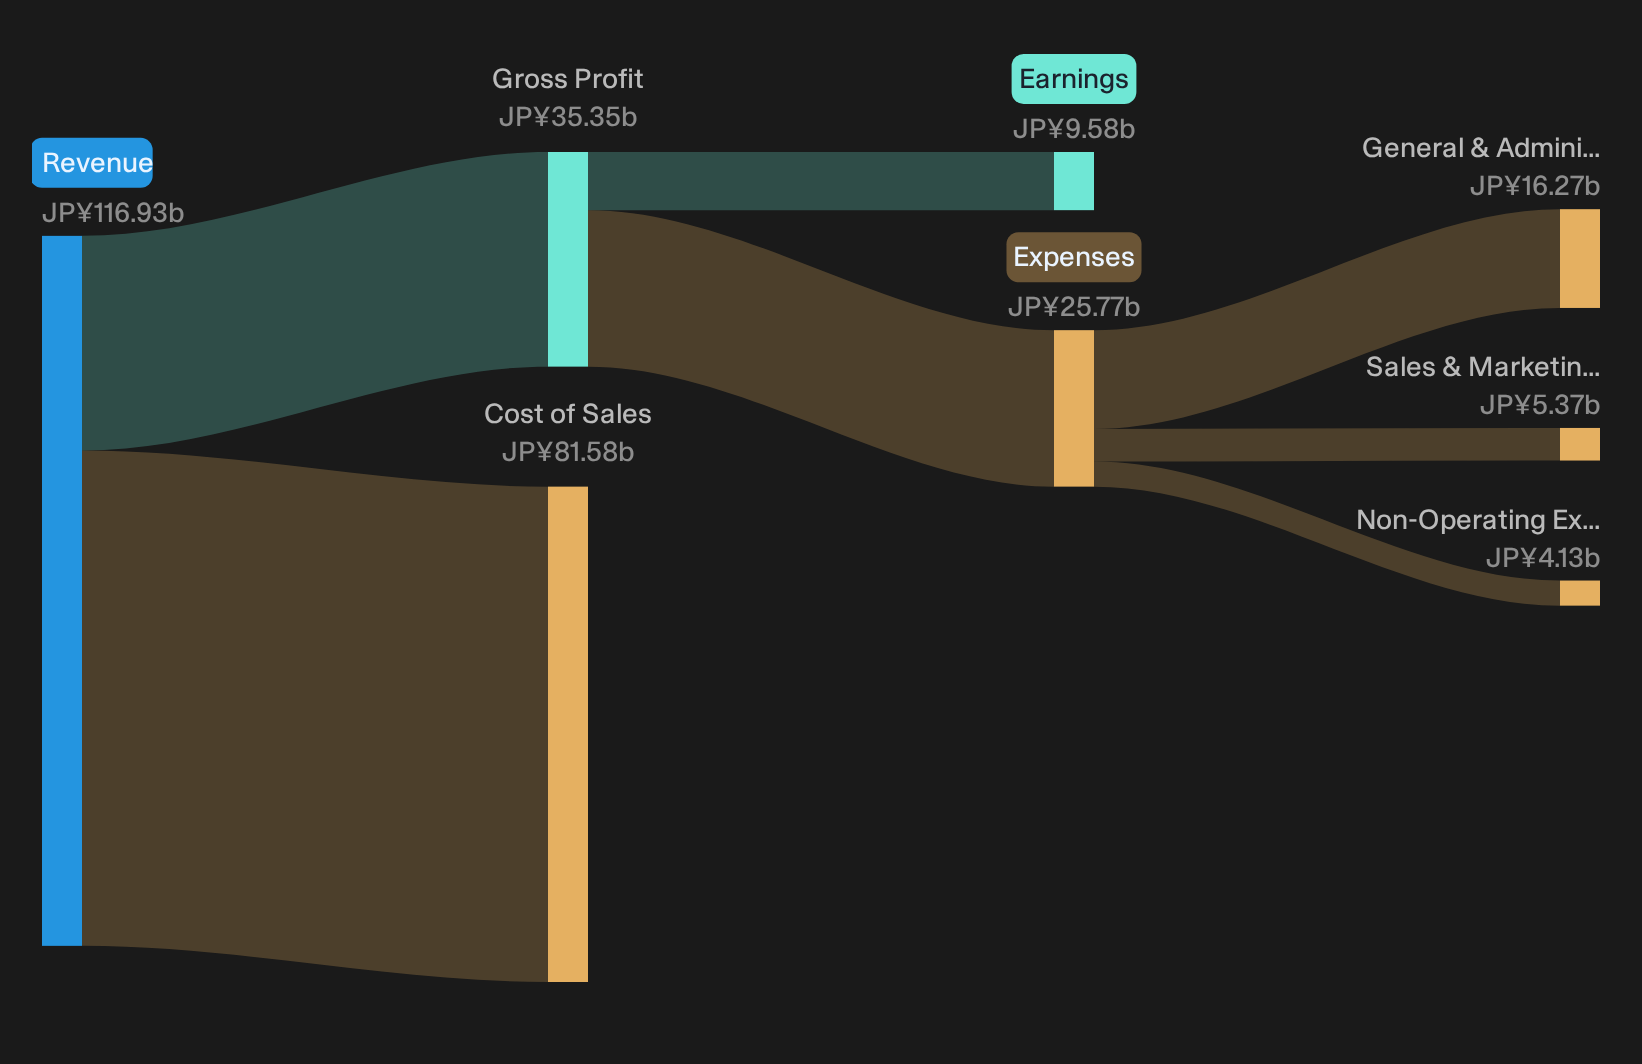
AS ONE growth story meets a profit squeeze
Bulls argue that AS ONE’s investment phase should set up stronger profitability and returns rather than simply inflate the cost base.
"The FY3/27 financial guidance points to a year of growth investments, which should translate to profitability improvement in future years. We note that AS ONE has maintained a strong track record of cost discipline, which makes us believe the elevated SG&A spend in FY3/27 is expected to generate meaningful returns."
Q2 tells a more mixed story. Revenue grew about 7.2%, yet quarterly net income and EPS both declined. That combination suggests the step up in spending is arriving, while the margin uplift that the bullish narrative expects is not visible yet.
AS ONE investment risks show up in margins
The cautious view is that the same investment push could drag on earnings longer than bulls hope if new services scale slowly.
"FY3/27 guidance points to steady revenue growth but earnings impacted by growth investments, AS ONE guided for FY3/27 net sales of ¥117.9bn (+6.5% YoY) and operating profit of ¥12.9bn (+0.5% YoY), with reported EPS declining -1.9% YoY to ¥125.86."
Latest quarterly figures lean toward this concern. Revenue moved higher, yet Q2 net income fell about 8.5% and EPS eased about 8.0%. That pattern lines up with guidance for a transition year and shows the earnings drag from higher SG&A is already in play.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
Hunt For Stronger Earnings Setups
AS ONE just showed how a solid revenue line can still come with margin pressure. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - expands a maintenance-focused salesforce to secure contracts and deepen dense service routes.
- Company 2 - 35% below our estimate - pushes AI-led hiring tools and local services that help convert job traffic into higher-fee placements.
- Company 3 - 45% below our estimate - shifts security customers to a unified platform and subscriptions tying pricing to recurring protection needs.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com