


EN
Autobacs Seven (TSE:9832) Stock Shrugs Off Strong Q2 Earnings Results
Autobacs Seven came into this Q2 2027 earnings print with a stock that had drifted lower over the past week and month, closing at ¥1,506 on 30 October. The company has a reputation as a steady auto aftermarket retailer with modest growth and a solid dividend. The fresh numbers told a sharper story. Quarterly net income reached ¥5,507m with basic EPS at ¥70.11, and the latest trailing P/E of about 10x keeps the valuation below both the broader Japanese market and specialty retail peers, even as the share price barely responded.
Like the income line and modest valuation at Autobacs Seven but wary that the market seems unconvinced? Compare this setup with our list of other retailers and consumer names trading on modest earnings multiples and stronger perceived momentum in our 14 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥72,376m vs. ¥64,615m; up about 12%
- Net Income (Q2 2027 vs Q2 2026): ¥5,507m vs. ¥1,500m; up very sharply, more than 3x
- Basic EPS (Q2 2027 vs Q2 2026): ¥70.11 vs. ¥19.10; up very sharply, more than 3x
- Trailing 12-Month Basic EPS (Q2 2027 vs Q2 2026): ¥150.76 vs. ¥127.34; up about 18%
Tired of scrolling through walls of Autobacs Seven figures and trying to stitch the story together on your own? Get the full picture in a clean visual dashboard that lays out the valuation context at a glance in our company report for Autobacs Seven.
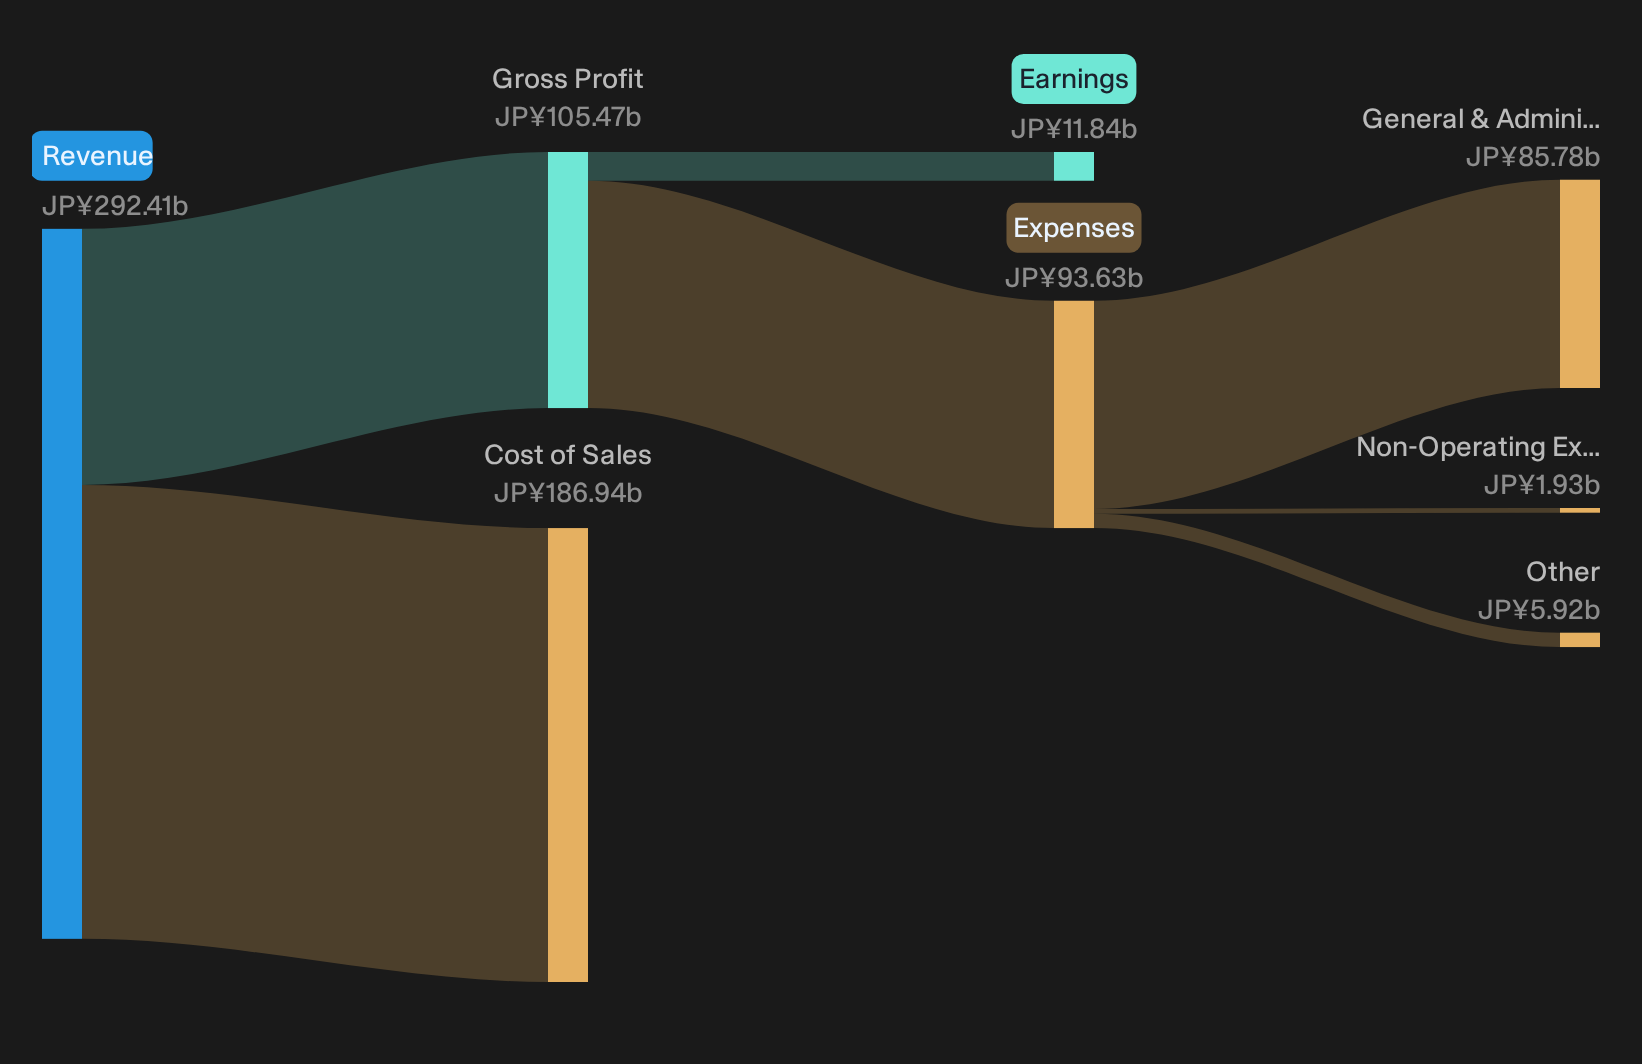
Autobacs Seven earnings lean into the steady story
For investors who see Autobacs Seven as a defensive aftermarket retailer, this set of results largely backs that view. Revenue of ¥72,376m versus ¥64,615m and net income of ¥5,507m compared with ¥1,500m show the engine is not just idling. Profitability looks healthier when basic EPS jumps from ¥19.10 to ¥70.11 and trailing EPS reaches ¥150.76. Adding the fresh buyback of up to 2,000,000 shares makes the message clear: management is treating current cash generation as strong enough to return capital.
Where the cautious Autobacs Seven thesis still bites
Bears focus less on one strong quarter and more on whether a mature auto retailer can keep earnings quality intact. Recent share performance supports their caution. The stock is down about 2% over 7 days and about 2% over 30 days, even with sharply higher quarterly profit. That muted reaction suggests investors still worry about long term growth or competitive pressure. The buyback improves capital efficiency, but it also hints at limited internal uses for cash if organic reinvestment opportunities are constrained.
After a quarter like this, the bigger concern is whether Autobacs Seven is quietly leaning on buybacks while core earnings power softens. Before assuming this is simply a healthy income story with a shareholder-friendly payout, review the independent risk analysis for Autobacs Seven which shows 2 important warning signsHunt For Quiet Balance Sheet Strength
Autobacs Seven recently reported earnings that still left some investors cautious about its balance sheet. The real opportunity may be in stocks that could already have low debt before the market reassesses them.
- Company 1 - 18% below our estimate - expands its maintenance-focused sales team to secure more service contracts and improve route density.
- Company 2 - 35% below our estimate - deploys AI tools that streamline hiring workflows and link pricing more tightly to successful placements.
- Company 3 - 45% below our estimate - redirects sales incentives toward subscription security bundles so AI products reinforce recurring revenue.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com