


EN
Okabe (TSE:5959) Stock Ignores Q3 Earnings Rebound As Profit Jumps
Okabe closed at ¥918 on Friday, capping a flat month for the stock even as fresh Q3 2026 earnings landed after the bell. The headline is simple and hard to ignore. Profit and earnings per share jumped sharply, with basic EPS at ¥37.94 on revenue of ¥19,579m.
Short term traders may focus on the muted price response. Longer term holders will likely be more interested in the pattern unfolding underneath, where quarterly net income has stepped up each period this fiscal year and now feeds into a modest 11x trailing P/E that already reflects the rebound.
Like the sharp rebound in Okabe's earnings but wish you had a broader shortlist of companies pairing reasonable valuations with clear profit momentum? Benchmark this result against our 14 high quality undervalued stocks to see how other cash generative stocks with solid balance sheets stack up.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): ¥19,579m vs. ¥18,178m (up about 8%)
- Net Income (Q3 2026 vs. Q3 2025): ¥1,677m vs. ¥1,024m (up about 64%)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥37.94 vs. ¥22.43 (up about 69%)
- Trailing 12 Month Basic EPS (Q3 2026 vs. Q3 2025): ¥81.69 vs. a loss of ¥9.36 (swing back to profit over the year)
Tired of scrolling through dense earnings tables and raw figures? See Okabe's full financial picture in clean, visual charts that place its valuation and recent profit rebound in context through our company report for Okabe.
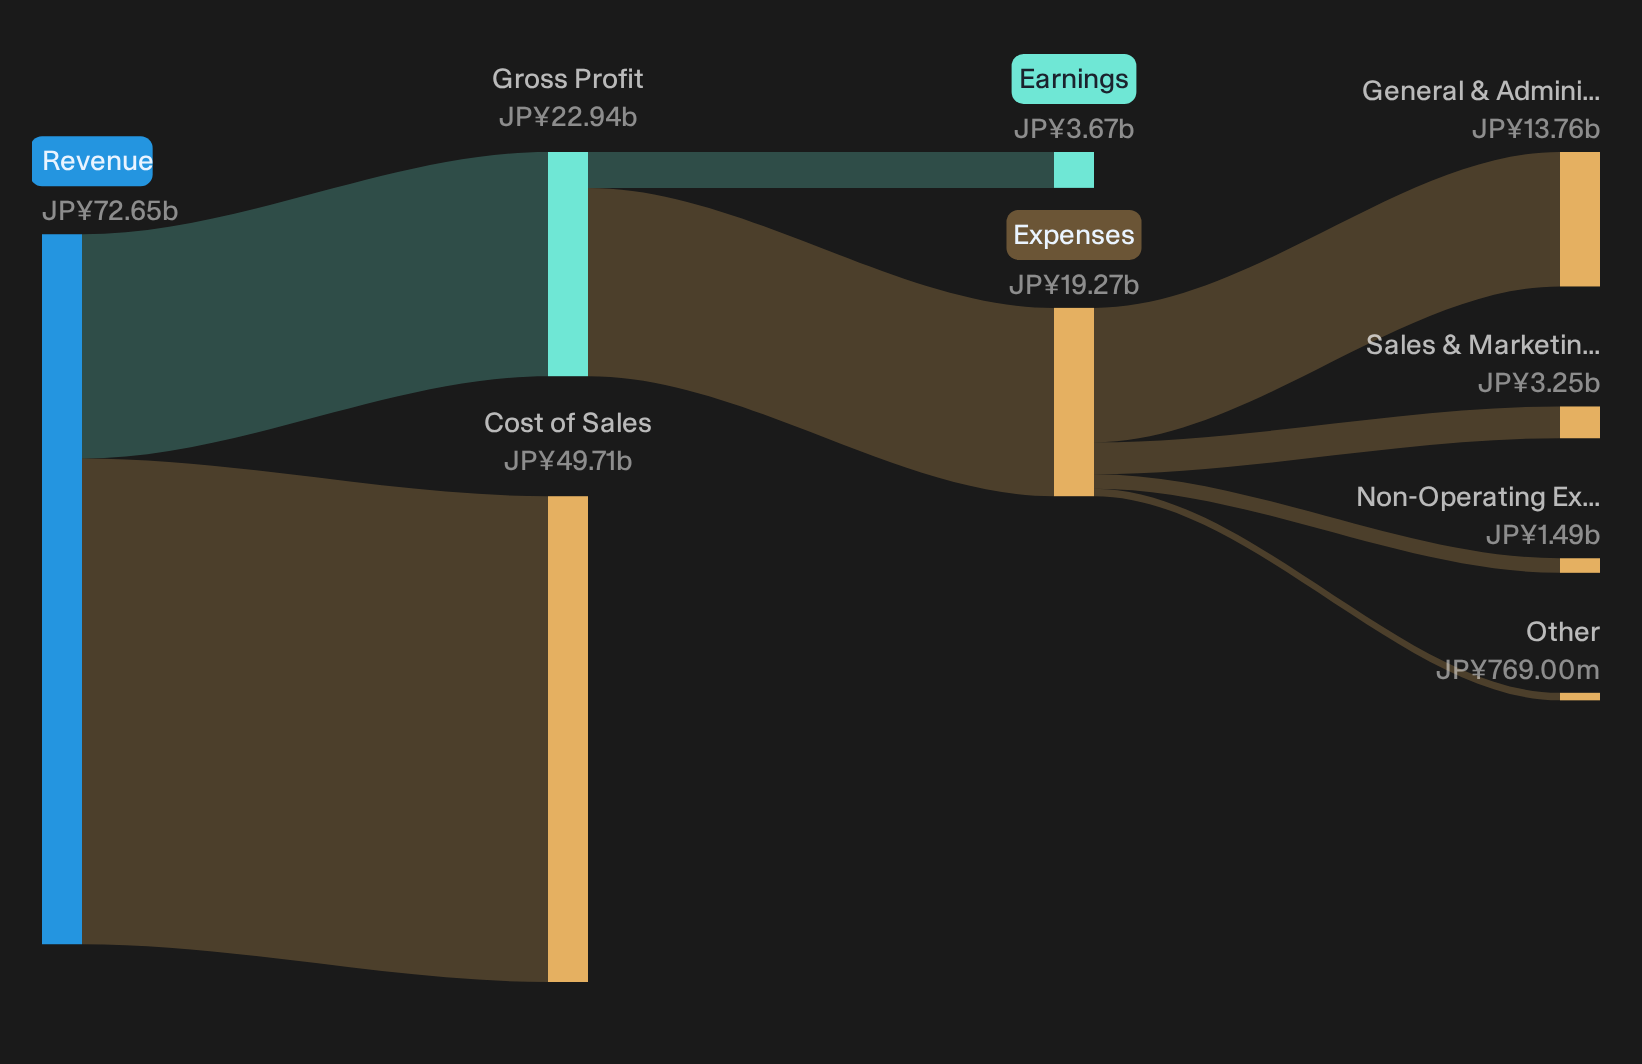
Okabe earnings rhythm backs steady infrastructure story
For a business tied to construction cycles, Okabe is putting up the kind of consistency that supports the steady infrastructure enabler angle. Revenue moved to ¥19,579m and quarterly net income rose to ¥1,677m, which lifted basic EPS to ¥37.94 and turned trailing EPS into ¥81.69 after a loss a year earlier. Profitability is moving in the right direction while the share price has been roughly flat over 30 days, so the operational recovery is outpacing recent trading.
Muted share response leaves room for caution
The bear story around a cyclical construction supplier is not fully erased. Recent returns are soft, with the stock down about 0.4% over 7 days and roughly flat over 30 days despite stronger EPS and income. That disconnect can imply investors are treating this upswing as potentially fragile for a sector tied to project volumes and budgets. Okabe is showing better earnings, yet the market reaction so far hints that concerns about cycle risk and pricing power have not disappeared.
After years of shrinking earnings and a dividend that is not well covered by free cash flows, it is worth asking whether the current recovery at Okabe is masking deeper structural issues in its end markets or balance sheet resilience. Scan the independent risk analysis for Okabe which shows 2 important warning signsHunt Quiet Balance Sheet Shifts
Okabe has posted stronger earnings while its recent share price has barely moved. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - expands its salesforce to win elevator maintenance contracts and deepen recurring modernization revenue.
- Company 2 - 35% below our estimate - builds AI tools that push recruiters toward automated job matching and higher value HR technology services.
- Company 3 - 45% below our estimate - pours spending into an AI-first security platform designed to convert customers onto higher margin subscription-style ARR contracts.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com