


EN
Fujibo Holdings (TSE:3104) Stock Drifts After Strong Q2 Earnings
Fujibo Holdings entered this Q2 2027 earnings release with a premium story and a tired share price. The stock closed at ¥3,265 on 30 October, with returns over the past month and quarter both in decline, which hinted at investors questioning how much good news was already priced in.
The new numbers directly addressed that tension. Quarterly revenue reached ¥14,182 million and net income came in at ¥1,602 million, keeping the profit engine intact for a business already trading on a 17.7x P/E against lower peer and industry averages.
Impressed that Fujibo Holdings is keeping profits steady on a premium 17.7x P/E but uneasy about paying up while the share price drifts? Compare it against a curated list of companies with strong earnings power backed by sturdier balance sheets in our list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥14,182 million vs. ¥11,275 million (up roughly 26%)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,602 million vs. ¥1,248 million (up roughly 28%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥47.50 vs. ¥36.94 (up roughly 29%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 12.3% vs. 11.5% (improved margin profile year over year)
Earnings are only half the story, since cash flows show what is actually available to owners and how much of Fujibo Holdings' current strength is backed by hard yen coming through the door.
If you anchor on Fujibo Holdings' cash flows rather than just the latest Q2 profit line, the stock could be a solid 16% overvalued.
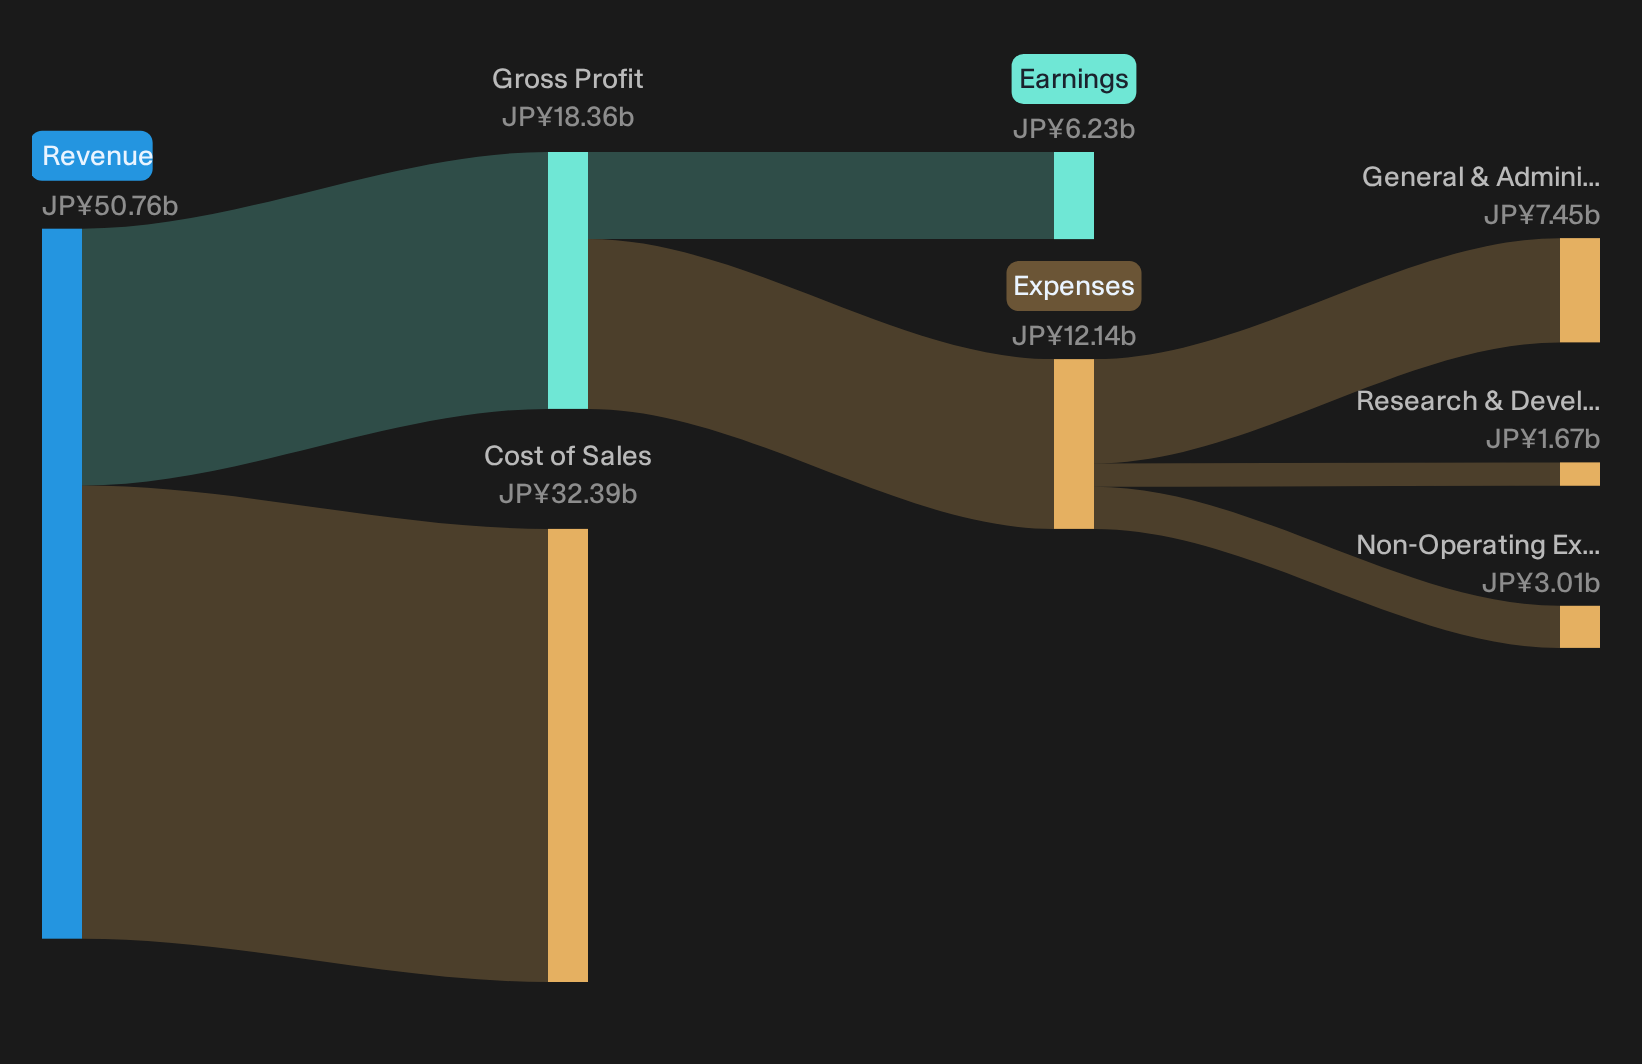
Fujibo bullish story leans on profit resilience
For investors leaning toward the optimistic side, Fujibo Holdings just handed you cleaner evidence. Revenue of ¥14,182 million and net income of ¥1,602 million both sit well above last year’s Q2 levels, while trailing net margin edges up to 12.3% from 11.5%. That mix suggests the industrial and chemicals portfolio is not only bringing in more business, but is also doing so with slightly tighter profitability. For a group straddling semiconductors, specialty materials and textiles, these trends fit a steady, cash generative profile rather than a fragile one.
Share price drift keeps bearish worries alive
Concerned about the other side of the story? The share price has slipped roughly 4% over 7 days, 6% over a month and 7% over a quarter into 30 October 2026. That weakness contrasts with higher Q2 revenue and earnings, so some holders may still question how durable the mix of semiconductor, chemical and apparel businesses really is. The modest margin improvement to 12.3% helps counter the idea of an operational slide, yet the muted market reaction shows scepticism has not cleared out.
After a 7% slide over three months while earnings hold up, share price volatility can hint at deeper fragility. Review our risk analysis for Fujibo Holdings which shows 1 important warning signHunt Stronger Balance Sheets Quietly
Fujibo Holdings shows how steady earnings and a drifting share price attract both fans and sceptics. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - uses an expanding sales force to win long-term maintenance contracts and deepen installed-base coverage.
- Company 2 - 45% below our estimate - ties richer AI spending to subscription security platforms combining device, cloud and digital life protection in one contract.
- Company 3 - 35% below our estimate - turns AI tools and fee structures into hiring and local services platforms that monetise each successful match.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com