


EN
Orient (TSE:8585) Stock Faces Profit Squeeze After Q2 Earnings
Orient came into this Q2 2027 earnings release with a mixed story in investors’ minds, a consumer finance stock with a trailing P/E richer than its peers and a share price that has slipped over the past three months. The headline today is straightforward: quarterly net income reached ¥2,945 million on revenue of ¥66,307 million, and earnings per share printed at ¥17.19.
The twist is in the reaction. The stock closed at ¥767 on 30 October, barely budging despite that profit figure. That gap between a muted price move and solid earnings power is what matters now for Orient holders.
Love Orient’s earnings power but uneasy about a richer P/E and a flat share price reaction? Check your expectations against our list of 24 resilient stocks with low risk scores to see how this lender stacks up against steadier options in the same space.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥66,307 million vs. ¥62,001 million (up about 6.9%)
- Net Income (Q2 2027 vs. Q2 2026): ¥2,945 million vs. ¥4,471 million (down about 34.1%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥17.19 vs. ¥26.12 (down about 34.2%)
- Trailing 12-month Net Income (to Q2 2027 vs. to Q2 2026): ¥10,162 million vs. ¥16,440 million (down about 38.2%)
Earnings are forecast to jump faster than revenue for Orient. Ask Charlie what makes Orient’s forecast earnings growth believable.
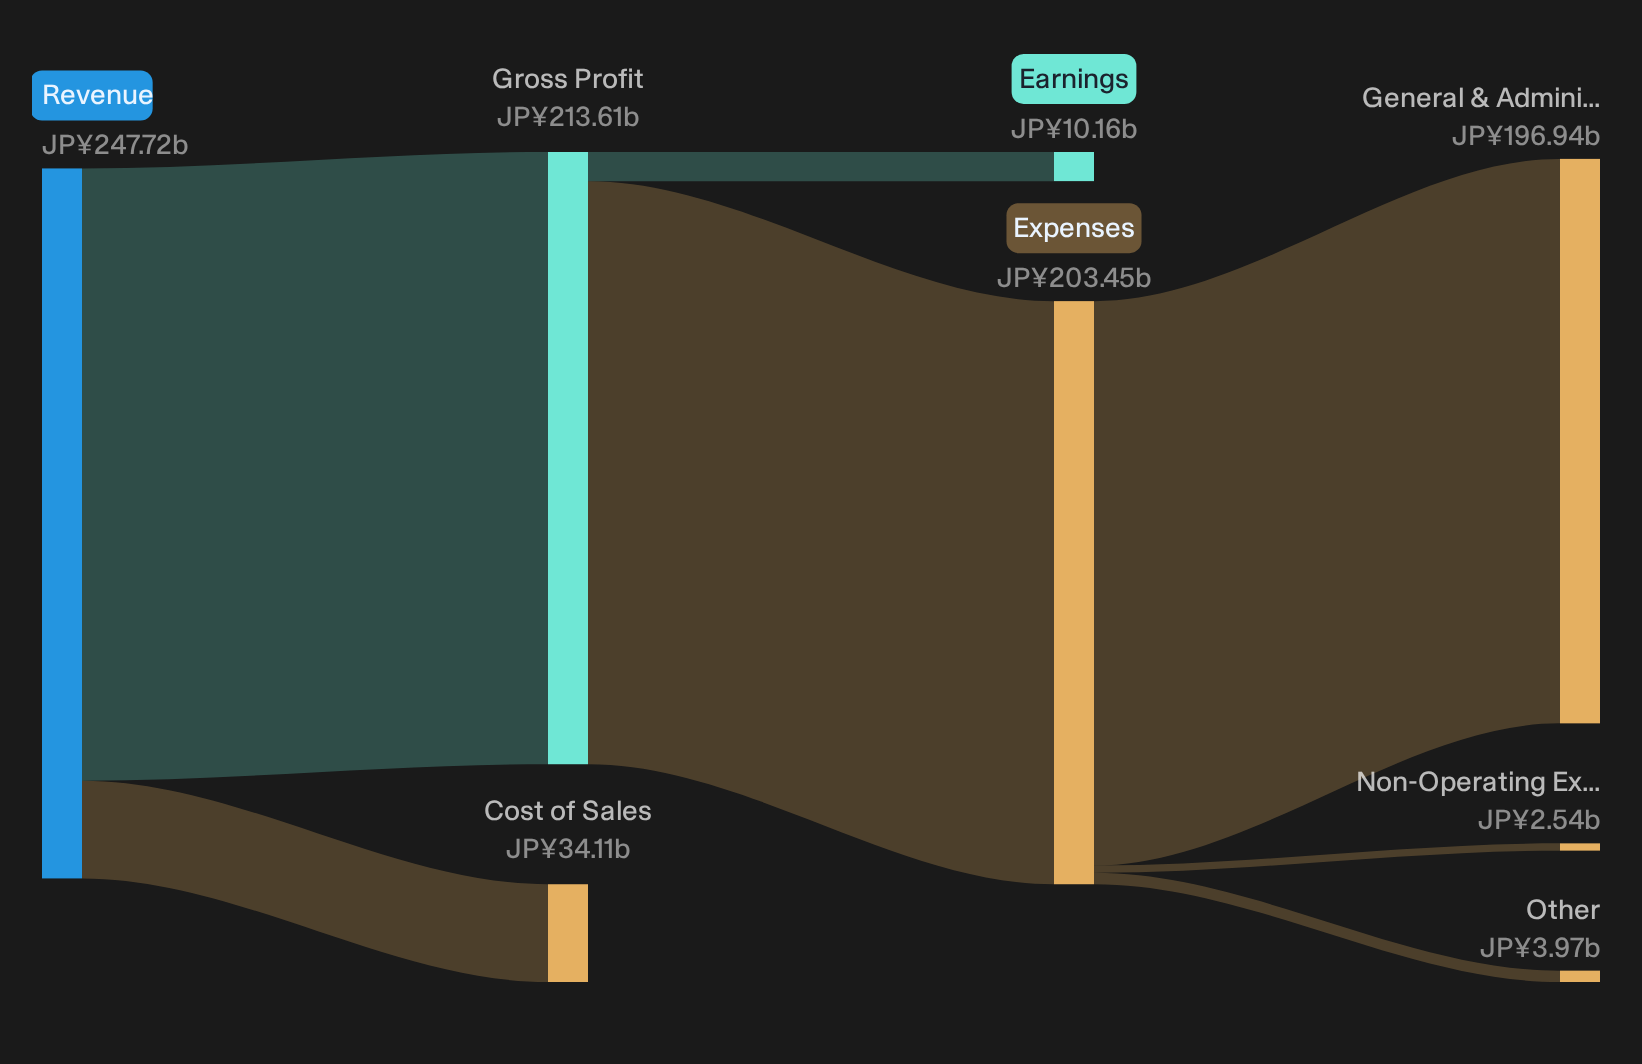
Orient’s diversified engine meets mixed earnings reality
For a bullish read, Orient still offers a broad set of income streams. Q2 revenue of ¥66,307 million sits ahead of the prior year and supports the idea of a wide, fee and interest driven platform. The issue is that this higher top line did not translate into stronger profits. Net income of ¥2,945 million and basic EPS of ¥17.19 sit well below last year’s levels, so any optimistic view now leans more on franchise depth than recent earnings momentum.
Profit compression keeps bearish concerns in play
On the cautious side, the data gives skeptics fresh material. Net income and EPS each declined more than 30% year on year. Trailing 12 month profit moved from ¥16,440 million to ¥10,162 million, which points to pressure on the earnings base across more than one quarter. For a consumer finance stock, that kind of profit squeeze can feed worries about credit costs or pricing power, even though headline revenue still looks resilient.
After profit margins slipped from 6.7% to 4.1% while debt and dividends strain cash generation, it is fair to ask whether these pressures are isolated or part of a deeper pattern inside Orient. Review the full risk analysis for Orient which shows 3 important warning signsHunt For Quiet Balance Sheet Strength
Orient just reported revenue growth while its share price stayed subdued. The real opportunity is searching for stocks that could be low debt before balance sheets gain wider attention.
- Company 1 - 45% below our estimate - shifts intensive AI security and cloud spending into recurring platform subscriptions that deepen bundled protection.
- Company 2 - 18% below our estimate - expands a maintenance-focused sales force so more installed elevators convert into modernization and service contracts.
- Company 3 - 35% below our estimate - builds AI driven hiring and services tools that move job ads and local bookings onto higher margin matching platforms.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com