


EN
Mitsubishi Logistics (TSE:9301) Q2 Results Reveal Profit Slide Behind Steady Revenue
Mitsubishi Logistics stock closed at ¥1,504 on 30 October, barely moved over the past week, yet the fresh Q2 2027 earnings tell a more uncomfortable story for short term traders. Quarterly net income came in at ¥3,462m on revenue of ¥74,276m, which keeps the warehouses and transport assets busy but puts the spotlight firmly on profitability.
The real issue is the squeeze in earnings power over the past year and what that means for a stock already trading on a richer P/E than many Asian infrastructure peers. If you are only watching today’s price flicker, you miss the longer term pressure building in this logistics group’s margins and valuation.
Like the stability of Mitsubishi Logistics' revenue base but uneasy about the pressure on earnings and a richer P/E? You may want to shift your attention to our screener of companies with stronger profitability and sturdier balance sheets in the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥74,276m vs. ¥67,554m (higher top line year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥3,462m vs. ¥14,280m (sharp decline in quarterly profit)
- Basic EPS (Q2 2027 vs Q2 2026): ¥10.21 vs. ¥40.42 (earnings per share down materially)
- Trailing Net Profit Margin (Last 12 Months vs Prior Year): 11.1% vs. 16.9% (margin compression over the year)
Prefer clear visuals instead of another wall of earnings tables and ratios for Mitsubishi Logistics? View the complete financial picture, including valuation details and how the market is pricing this stock today, in the company report for Mitsubishi Logistics.
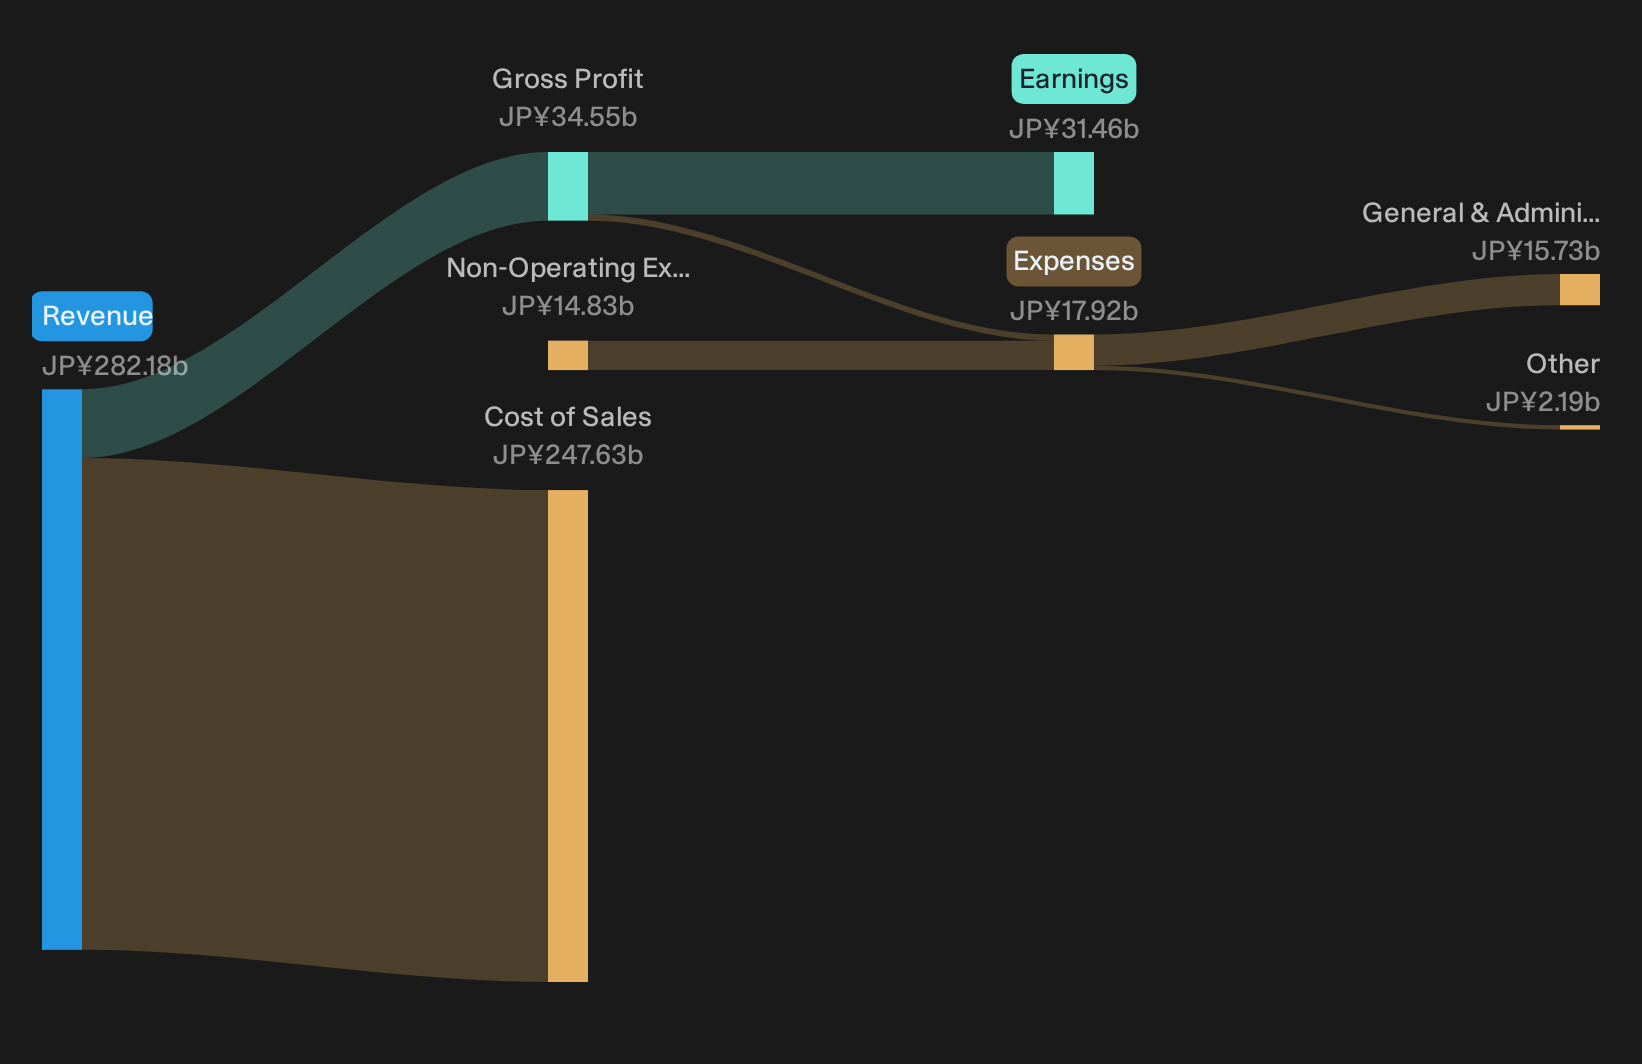
Mitsubishi Logistics: Revenue Resilience Supports Defensiveness
Mitsubishi Logistics still looks like a defensive infrastructure play at the top line. Quarterly revenue of ¥74,276m compared with ¥67,554m a year earlier points to customers that keep using the network. The new US distribution center projects also fit that story of steady demand for warehousing capacity. For investors who see the group as an essential part of trade flows and real estate, the ability to hold a higher revenue base while expanding overseas assets lends some support to the longer term, stability focused narrative.
Profit Compression Keeps Bearish Concerns In Focus
The profit trend tells a tougher story. Net income excluding extra items moved from ¥14,280m to ¥3,462m and trailing net margin slid from 16.9% to 11.1%. That kind of earnings squeeze challenges any simple "safe haven" label for Mitsubishi Logistics. The business is still busy, but it is getting paid less for that effort. Until profitability stabilises, concerns about operational pressure, project returns and the overall earnings quality of this diversified logistics and property group remain hard to dismiss.
After such a steep compression in Mitsubishi Logistics' profit margin and earnings, it is worth asking whether this is an isolated squeeze or the start of a deeper pattern. Review the independent risk analysis for Mitsubishi Logistics which shows 4 important warning signsHunt Stronger Balance Sheets Quietly
Mitsubishi Logistics shows how steady revenue can still sit beside tightening earnings and valuation tension. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 45% below our estimate - focuses spending on AI-native security platforms that convert legacy license customers to recurring subscriptions.
- Company 2 - 35% below our estimate - pushes AI hiring tools and sponsored listings that turn basic job posts into higher value, performance-linked contracts.
- Company 3 - 18% below our estimate - expands its maintenance-focused sales force to pull more elevator contracts into recurring service and modernization pipelines.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com