


EN
Takeda Pharmaceutical (TSE:4502) Shares Just Moved, So What Is Going On?
Takeda Pharmaceutical (TSE:4502) has just raised its fiscal 2026 guidance, paired with positive TAK-921 and ENTYVIO data and a slightly higher dividend, giving investors fresh information on both current earnings and pipeline progress.
Takeda Pharmaceutical’s latest guidance hike and clinical readouts arrive while momentum in the shares has been strong, with a 30 day share price return of 17.86% and a year to date share price return of 35.29%, alongside a 1 year total shareholder return of 65.79% that reflects both capital gains and reinvested income and indicates rising optimism about the earnings outlook and pipeline risk profile.
Scan other pharma and biotech names riding similar sentiment with the curated 10 healthcare AI stocks that puts recent clinical catalysts and earnings momentum front and center.
After a 65.79% 1 year total return and fresh upgrades to Takeda Pharmaceutical’s earnings path, the question now is whether the current price still offers a clear upside skew or already prices in the good news.
Most Popular Narrative: 2% Undervalued
Takeda Pharmaceutical’s most followed narrative points to a fair value of ¥6,759.56 versus the last close at ¥6,651. This places the current rally against a view that the shares still trade at a small discount built on long term earnings and cash flow expectations.
The numbers suggest that Takeda Pharmaceutical’s share price reflects caution around loss of exclusivity and competitive risks relative to the potential contribution from the orexin sleep portfolio, zasocitinib’s expansion across immune mediated diseases, late stage oncology assets and company wide transformation. This narrative interprets these factors as indicating the stock may be undervalued with a positive outlook.
See why 17 investors see Takeda Pharmaceutical as 2% undervalued.
Result: Fair Value of ¥6,759.56 (UNDERVALUED)
Still, the Takeda Pharmaceutical story can break if ENTYVIO and VYVANSE erosion hits harder than expected or if key launches such as ORZEYFUL and zasocitinib underperform commercially.
Find out about the key risks to this Takeda Pharmaceutical narrative.
Another View: What Multiples Say About Takeda Pharmaceutical
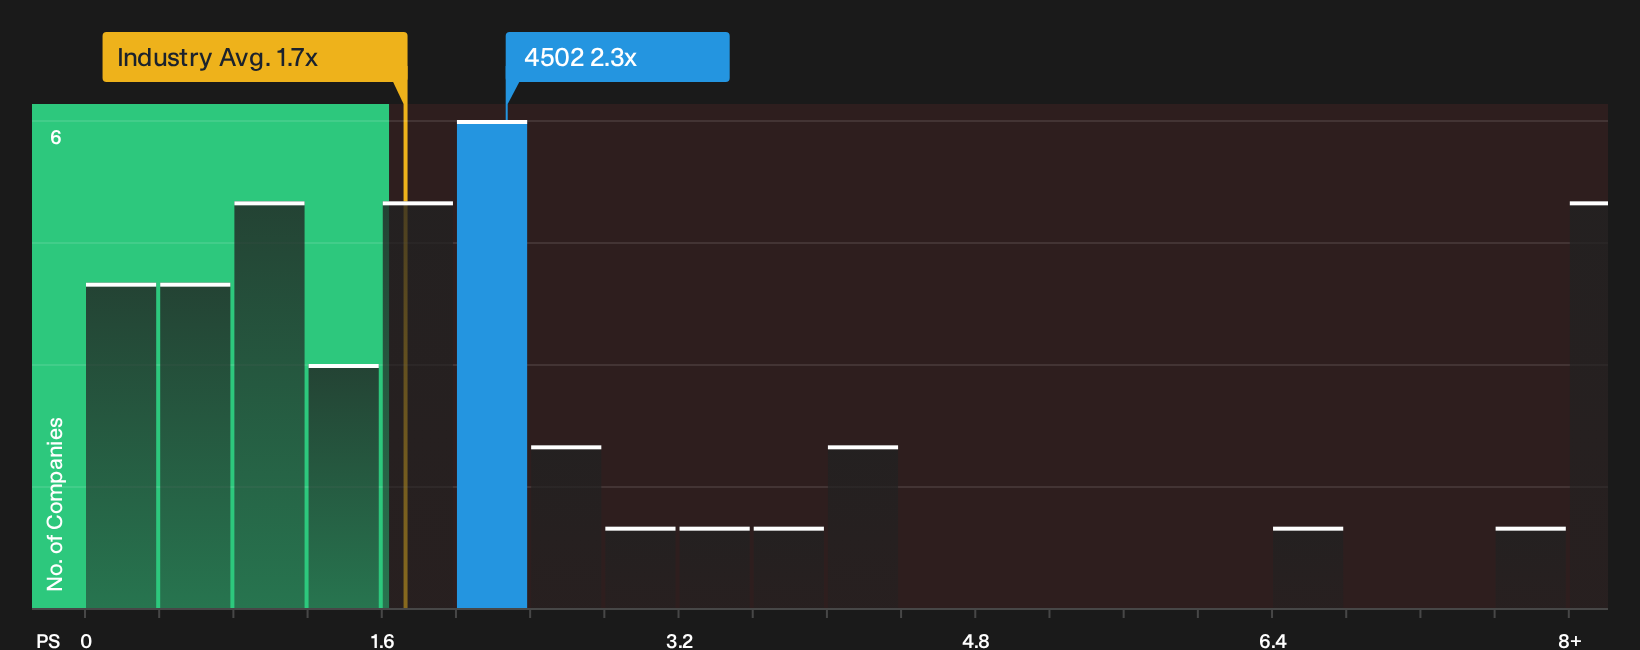
The story looks very different when switching from fair value models to a simple sales based yardstick. Takeda Pharmaceutical trades on a P/S of 2.3x, which is higher than the JP Pharmaceuticals industry at 1.7x, yet below a 3.7x fair ratio estimate and the 3.6x peer average. That mix of premium versus the sector but discount versus peers points to valuation risk if sentiment changes, but also potential for the ratio to move higher if the pipeline performs well. Which side of that tradeoff the market will favor remains uncertain.
For a closer look at how this pricing gap lines up against fundamentals, focus on our detailed valuation breakdown, including the See what the numbers say about this price — find out in our valuation breakdown..
To see how Takeda Pharmaceutical’s pricing compares visually with the rest of the sector, review the latest relative valuation chart here
Next Steps
If this mix of optimism and caution around Takeda Pharmaceutical leaves you undecided, do not wait for others to shape the narrative. Instead, evaluate the potential benefits alongside the risks using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Takeda Pharmaceutical?
Do not leave your watchlist anchored to just one story. Broaden your options now with a few targeted collections of stocks that match different goals.
- Zero in on quality at a discount by scanning companies that appear mispriced relative to their fundamentals through the 16 high quality undervalued stocks.
- Strengthen your portfolio’s resilience by focusing on businesses with low risk profiles using the 23 resilient stocks with low risk scores.
- Get ahead of the crowd by hunting for strong fundamentals in companies that are not widely followed through the 69 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com