


EN
Azenta (AZTA) And The Valuation Question As GENEWIZ Expands
Azenta’s GENEWIZ expansion and what it could mean for investors
Azenta (AZTA) has set a fresh marker for its genomics ambitions with two linked moves around its GENEWIZ unit. Management signed an exclusive DNA technology license with Elegen Corp and acquired synthetic biology player SynPlexity Inc.
Those decisions give GENEWIZ access to a cell free DNA manufacturing platform alongside pooled gene assembly tools that can generate thousands of variants inside a single library. For investors watching Azenta’s push into multiomics and drug discovery support, this pairing raises new questions about capital allocation, execution risk, and potential payoff horizons.
Azenta’s latest GENEWIZ moves land after a sharp 30.7% 90 day share price return and a 29.3% 1 year total shareholder return, although the 3 and 5 year total shareholder returns are still well below break even. This suggests that recent momentum is rebuilding confidence after a tougher stretch.
Scan how other life sciences and genomics players are responding to similar pressures by reviewing our curated list of 34 healthcare AI stocks alongside Azenta’s latest moves.
Azenta now sits between a sharp recent rerating and a still unproven multiomics push. Has most of the upside already played out in the share price, or does the latest GENEWIZ deal flow suggest there may be more on the table?
Most Popular Narrative: 20% Overvalued
Azenta closed at $39.06, exactly in line with the $39 fair value in the most followed narrative, yet that same framework classifies the shares as overvalued once risk and required return are factored in. For readers weighing the GENEWIZ expansion against the wider earnings story, this gap between headline fair value and implied downside is where the real tension sits.
The analysts have a consensus price target of $39.0 for Azenta based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $691.8 million, earnings will come to $29.5 million, and it would be trading on a PE ratio of 63.2x, assuming you use a discount rate of 8.1%.
See why 3 investors see Azenta as 0% overvalued.
Result: Fair Value of $39 (OVERVALUED)
Still, the CEO resignation in August 2026 and the ongoing securities investigations could unsettle confidence in Azenta’s governance and earnings visibility.
Find out about the key risks to this Azenta narrative.
Another view on Azenta’s valuation
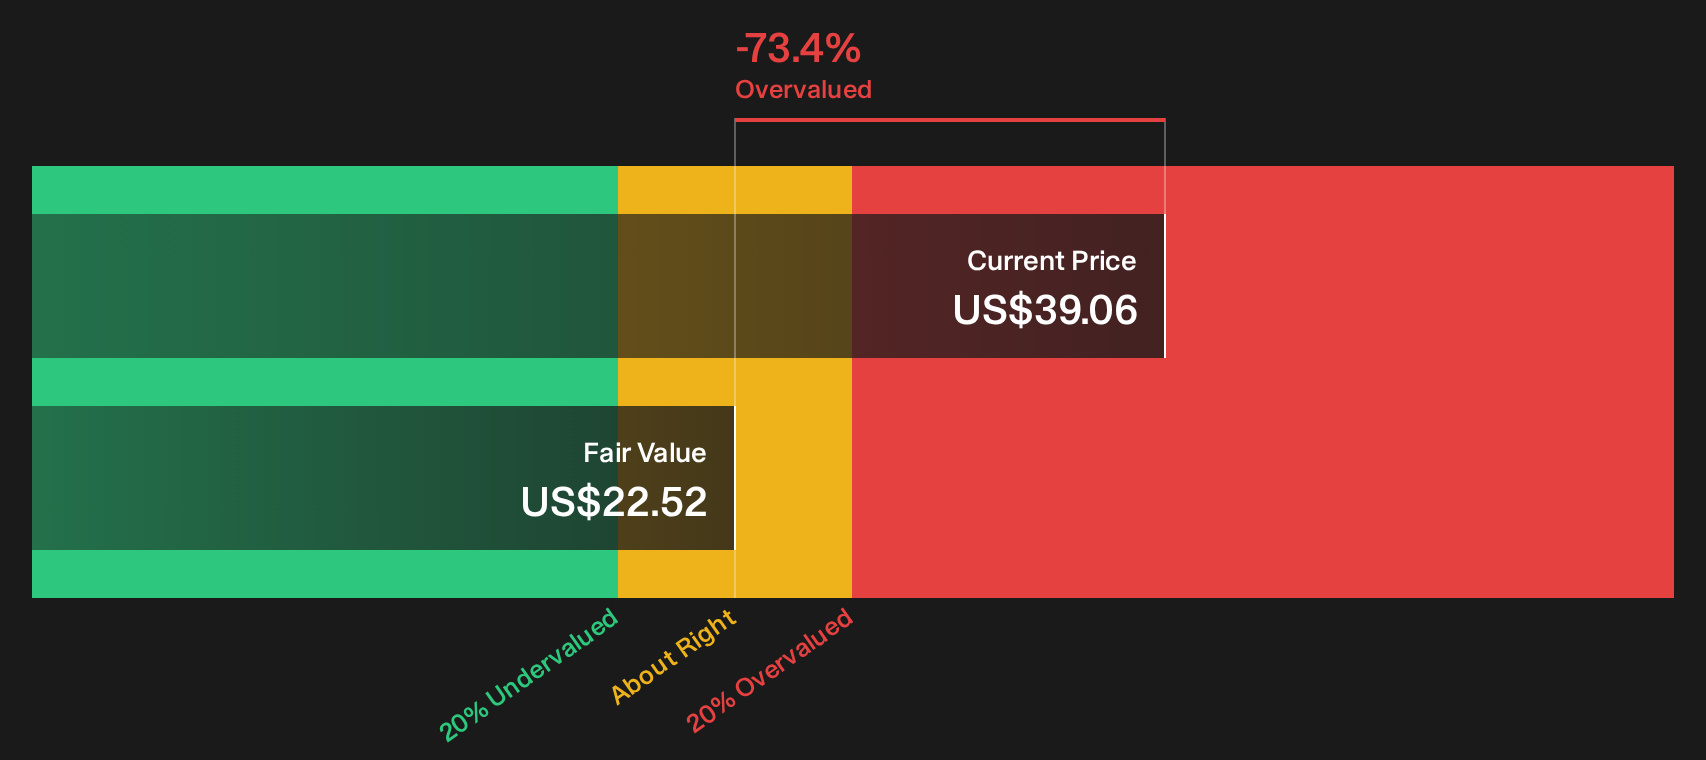
The first take presents Azenta as overvalued at about $39 per share, while the SWS DCF model estimates future cash flow value at $22.52. That is a wide gap. Is the crowd paying up for a story that the cash flows do not fully support?
Support your own conclusion by reviewing how our DCF model handles Azenta’s assumptions and scenario choices, rather than focusing only on the headline output from the SWS DCF model. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment in this Azenta piece has been mixed, so treat it as a starting point and move quickly to pressure test the data for yourself. To see what optimistic investors are focusing on, take a closer look at the 2 key rewards.
Looking for more Azenta sized ideas?
If Azenta has sharpened your focus, treat this as a springboard and cast a wider net using screeners built around quality, value, and resilience.
- Start with resilience and filter for companies that historically handle stress better than most by running the 29 resilient stocks with low risk scores.
- Hunt for potential mispricings and see which businesses combine strong fundamentals with appealing entry points through the 33 high quality undervalued stocks.
- Prioritise staying power and financial strength by scanning a list of solid balance sheet and fundamentals (24 results) before the next round of opportunities moves out of reach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com