


EN
IMAX (IMAX) Could Be 15% Undervalued As Dune Re Release Draws Focus
The re-release of Denis Villeneuve’s two Dune films in IMAX (NYSE:IMAX) theaters next month, paired with an exclusive Dune: Part 3 preview, has refocused attention on the company’s exposure to premium blockbuster screenings.
IMAX shares have cooled off in the short term, with the 7-day share price return down 5.19% and the 30-day share price return down 4.00%. However, the year-to-date share price return of 40.51% and 1-year total shareholder return of 55.77% point to momentum that has been building around the business ahead of high profile releases like the Dune re-release and preview for Dune: Part 3.
Scan beyond IMAX and this Dune catalyst by reviewing hand-picked cinema and media players with stronger fundamentals in our list of solid balance sheet and fundamentals (24 results).
IMAX now trades about 16% below the average analyst target and around 24% under one intrinsic value estimate. Is that gap mispricing, or is it a fair reflection of what the business is worth today?
Most Popular Narrative: 14.5% Undervalued
Against IMAX’s last close of $50.61, the most followed narrative pegs fair value at $59.17. This leaves a valuation gap that depends on how effectively the screen network and content slate convert into future earnings and free cash flow.
Rapid acceleration of new system installations and a replenishing, geographically diverse backlog supported by an estimated addressable market of 4,500 screens versus about 1,800 currently in operation points to further IMAX network expansion that could lift box office driven revenue and recurring cash flows as more locations contribute.
See why 9 investors see IMAX as 14% undervalued.
Result: Fair Value of $59.17 (UNDERVALUED)
Still, IMAX depends heavily on blockbuster-driven box office and cinema attendance, so any weaker release slate or faster shift to at-home viewing could challenge this bullish setup.
Find out about the key risks to this IMAX narrative.
Another View: IMAX On Rich Earnings Multiples
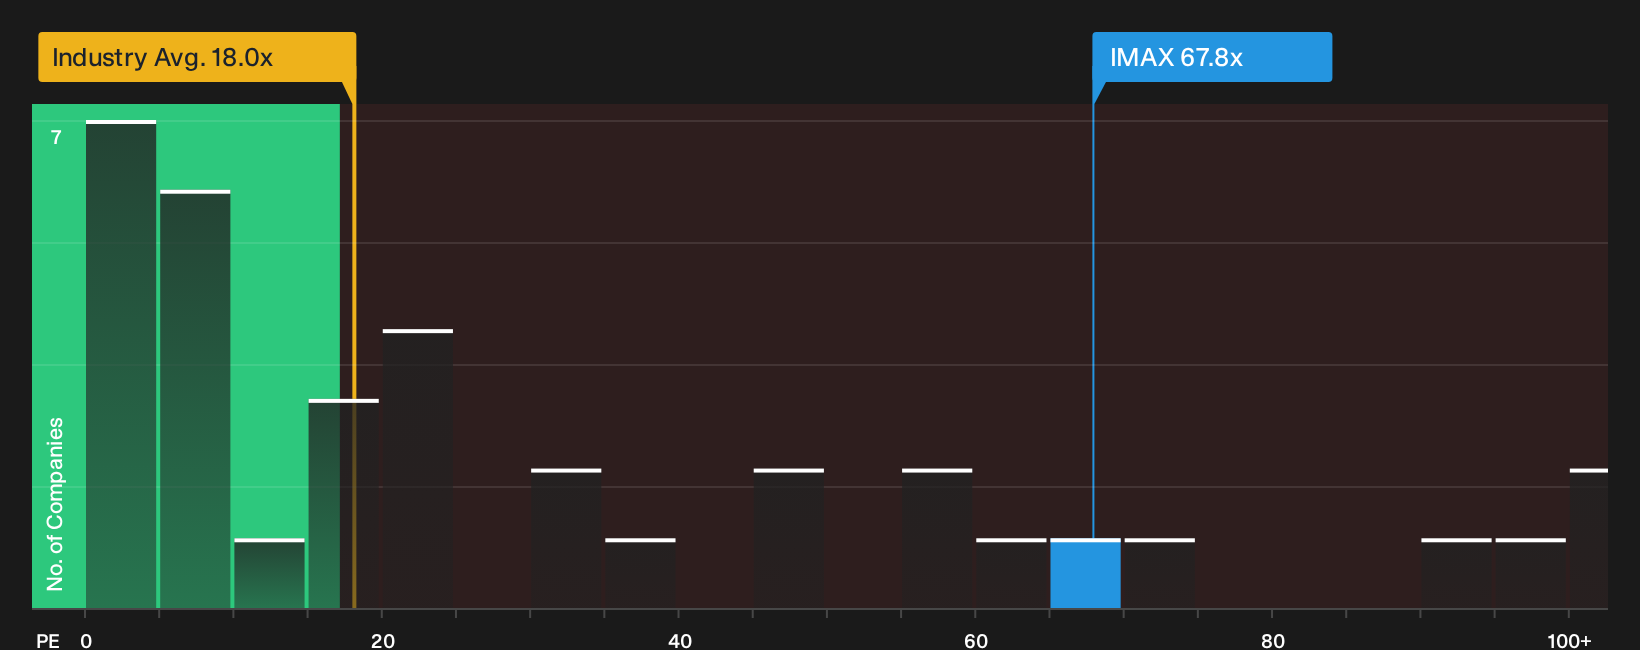
The first narrative leans on intrinsic value and cash flows. A second lens looks at what you are already paying for IMAX’s earnings. On a P/E of 67.8x versus 18x for the US Entertainment industry, 45.7x for peers and a 20.3x fair ratio, the stock carries a high bar that could amplify valuation risk if expectations ease. Does that premium feel justified to you, or does it leave too little room for error?
Before leaning too heavily on any single price target or ratio, it helps to see how these earnings multiples stack up in a fuller context, including cash flows and quality metrics, in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on IMAX’s value can be useful if you use them as a prompt rather than a script, so move fast, review the full picture, and weigh both the potential benefits and the red flags in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IMAX?
You have a clear read on IMAX. Now broaden your opportunity set with targeted stock ideas that match different risk levels, income goals, and value hunts.
- Target resilient performers that aim to protect your capital first by filtering for 29 resilient stocks with low risk scores.
- Hunt for potential mispriced opportunities by scanning our focused set of 33 high quality undervalued stocks.
- Strengthen your core holdings with businesses backed by healthy finances through a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com