


EN
What TowneBank (TOWN) Earnings Growth Means For Shareholders
- TowneBank reported third quarter 2026 results with net interest income of US$196.21 million and net income of US$81.78 million, along with higher earnings per share from continuing operations compared with the same period in 2025.
- Over the first nine months of 2026, TowneBank’s net interest income and earnings from continuing operations were higher than the prior year, although the bank also recorded higher net charge offs of US$2.45 million in the recent quarter.
- The discussion now turns to how TowneBank’s net interest income profile may influence the broader investment narrative around the business.
Compare TowneBank’s earnings profile with a curated group of regional financials by scanning the list of solid balance sheet and fundamentals (24 results), which may pair healthier credit trends with resilient net interest income.
What Is TowneBank's Investment Narrative?
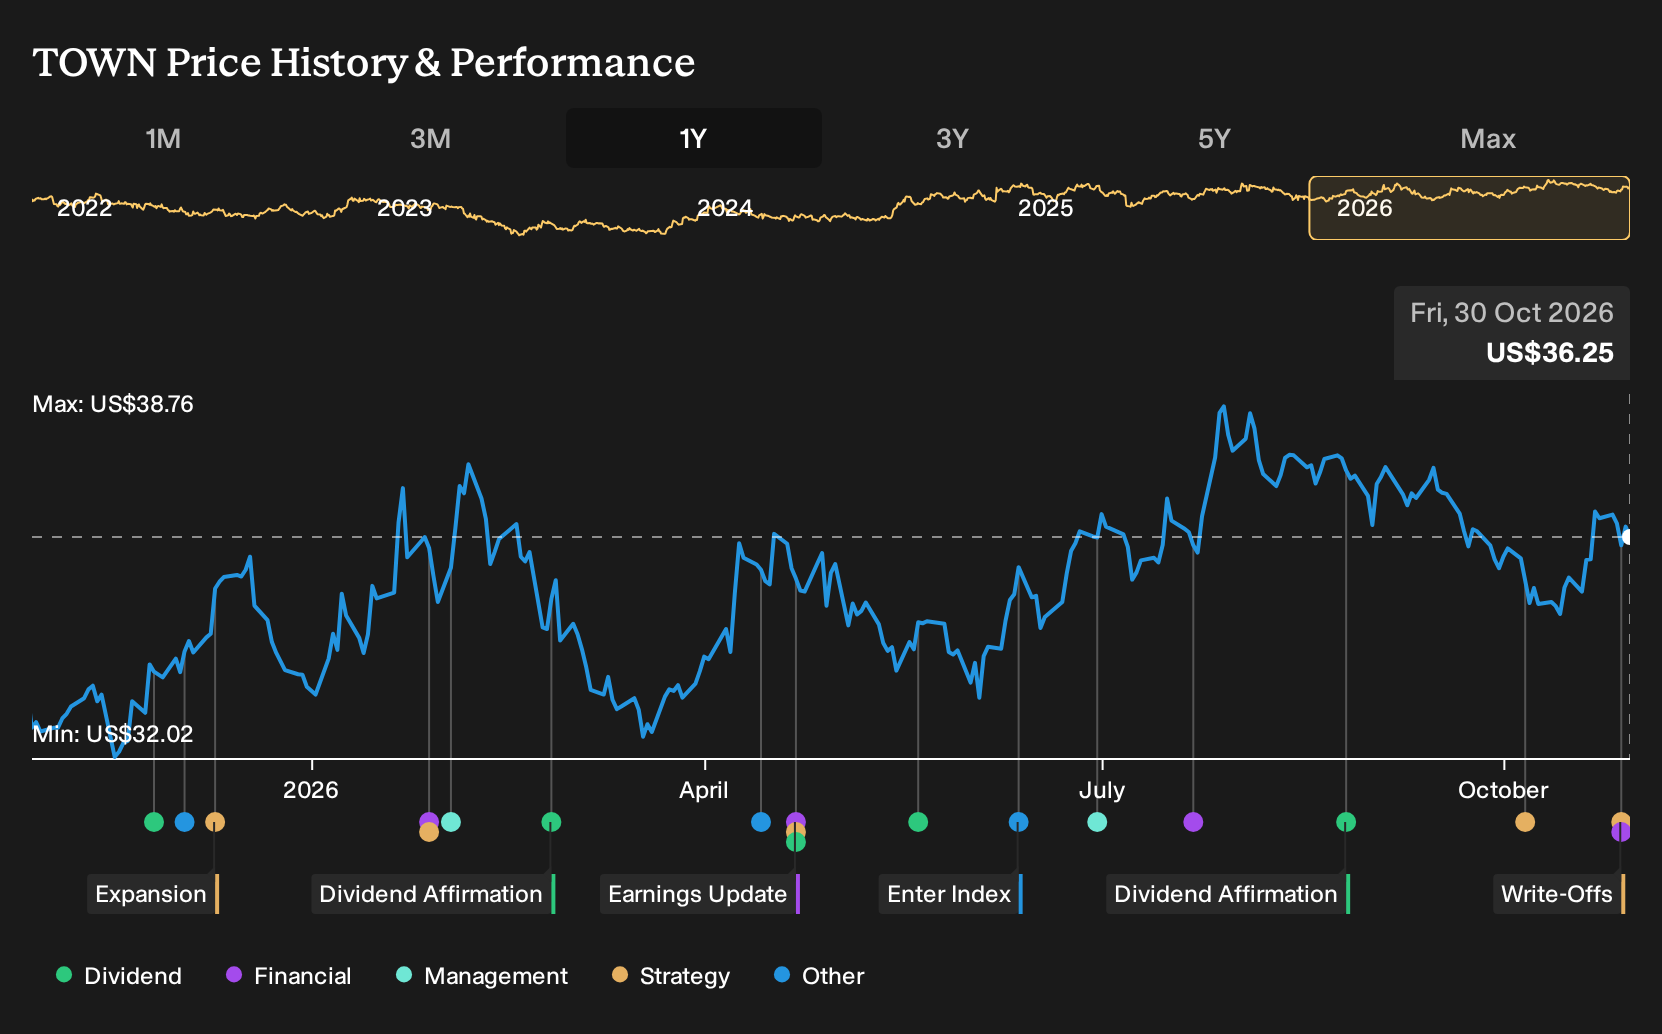
TowneBank’s appeal for a shareholder usually comes down to belief in a conservative regional lender that can turn consistent net interest income into steady earnings and dividends. The latest quarter fits that story, with higher net interest income and profit from continuing operations, plus earnings growth over the past year of 116.8%. Returns over 1 and 3 years have outpaced the broader US market and US banks, while the stock trades on a P/E of 9.3x, below both peers and an estimated fair multiple.
In the short term, the key swing factor is whether this earnings step up proves sustainable as net interest margins evolve and credit costs shift. Net charge offs of US$2.45 million in the quarter show credit quality is not a free lunch, even with net profit margins now at 30.5%. Forecasts that point to slight revenue and earnings declines over the next three years sit awkwardly against the current momentum, so the investment case leans heavily on TowneBank continuing to execute well in its core banking, mortgage, and insurance segments.
That said, the appealing mix of dividend, valuation, and recent profit growth still has one uncomfortable wrinkle once you look closely at ...
There's only one way to know the right time to buy, sell or hold TowneBank. Head to Simply Wall St's company report for the latest analysis of TowneBank's Fair Value.
Exploring Other Perspectives
TowneBank already draws two fair value views from the Simply Wall St Community, clustered tightly between US$38.94 and US$39.75. Those crowd estimates were set before the most recent earnings and the jump in net charge offs. Treat this as a reminder that opinions can differ widely and consider exploring several alternative viewpoints before deciding how these results fit your own expectations.
Explore another TowneBank fair value estimate, including one that suggests up to 10% upside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and using your judgment.
- A great starting point for your TowneBank research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for TowneBank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TowneBank's overall financial health at a glance.
Looking For More Ideas Beyond TowneBank?
If TowneBank's profile has sharpened your interest in regional financials and income opportunities, broaden your watchlist by running a few quick screens on the Simply Wall St platform. You can use these tools to surface other companies that match your preferred mix of valuation, quality, and risk.
- If you are hunting for potentially underpriced quality, start with companies that screen as attractively valued on both earnings and fundamentals through 33 high quality undervalued stocks.
- If income is a priority, focus on businesses with stronger yields and sturdier payouts sourced from the 5 dividend fortresses.
- If balance sheet strength matters most to you, filter for financially resilient banks and non banks using the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com