


EN
Honeywell Aerospace (HONA) Could Be 66% Undervalued As Earnings And Expansion Land
Honeywell Aerospace (HONA) has landed in focus after a busy October 28. The company released third quarter earnings, detailed a US$500 million Tempe expansion, and initiated a quarterly dividend of US$0.40 per share.
Despite the busy news day, momentum in Honeywell Aerospace’s shares has been weak, with the 90 day share price return down 26% and the year to date share price return down 23%. This suggests recent results and expansion plans have not yet shifted sentiment.
Scan beyond Honeywell Aerospace and evaluate other capital goods players that have been hand-picked in our 33 high quality undervalued stocks with solid balance sheets and cash flows.
Honeywell Aerospace has put fresh earnings, a US$500 million buildout, and a new dividend on the table while the share price has retreated. Investors may be assessing whether the potential upside lies ahead or is already behind them.
Preferred P/E of 24.1x: Is it justified?
Valuation on Honeywell Aerospace currently leans on a P/E of 24.1x, which sits against a last close of $154.15 and a mixed set of fundamentals and forecasts. Investors are weighing that earnings multiple against a share price that has fallen over recent months while revenue and profit expectations still point to growth.
The P/E ratio compares the stock price to per share earnings and gives you a shorthand view of how much the market is paying for each dollar of profit. For a business like Honeywell Aerospace that supplies mission critical aerospace and defense systems across engines, avionics, and control equipment, earnings are often a key reference point because cash flows and order cycles can run over long periods.
Analyst expectations and internal forecasts add extra context. Earnings are projected to grow 15.65% per year, while revenue is expected to rise 7.4% per year, which is slower than the broader US market forecasts. That kind of profile can help explain why the SWS DCF model estimates future cash flow value at $255.71 and why analysts see scope for a 26% share price move, even though recent reported earnings growth over the past year was negative and profit margins slipped from 16.1% to 11.3%.
Compared against peers the valuation gap is clear. Honeywell Aerospace trades on a P/E of 24.1x, below both the US Aerospace & Defense industry average of 32.1x and the peer group average of 37.6x. This indicates the market is pricing its earnings more conservatively than many comparable stocks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 24.1x (UNDERVALUED)
Still, the recent 26% share price decline over 90 days, along with softer profit margins, leaves Honeywell Aerospace exposed if earnings or cash conversion underperform expectations.
Find out about the key risks to this Honeywell Aerospace narrative.
Another View: What The DCF Model Says About Honeywell Aerospace
The earlier P/E check paints Honeywell Aerospace as relatively cheap against peers, but the SWS DCF model goes further. It places future cash flow value at $255.71 per share compared with the current $154.15 price, which implies a wide undervaluation based on projected cash generation.
That sort of gap can signal opportunity if those forecasts hold, or a warning if the assumptions on growth and margins prove too optimistic. Which story do you think the next few years of Honeywell Aerospace results will tell?
Look into how the SWS DCF model arrives at its fair value.
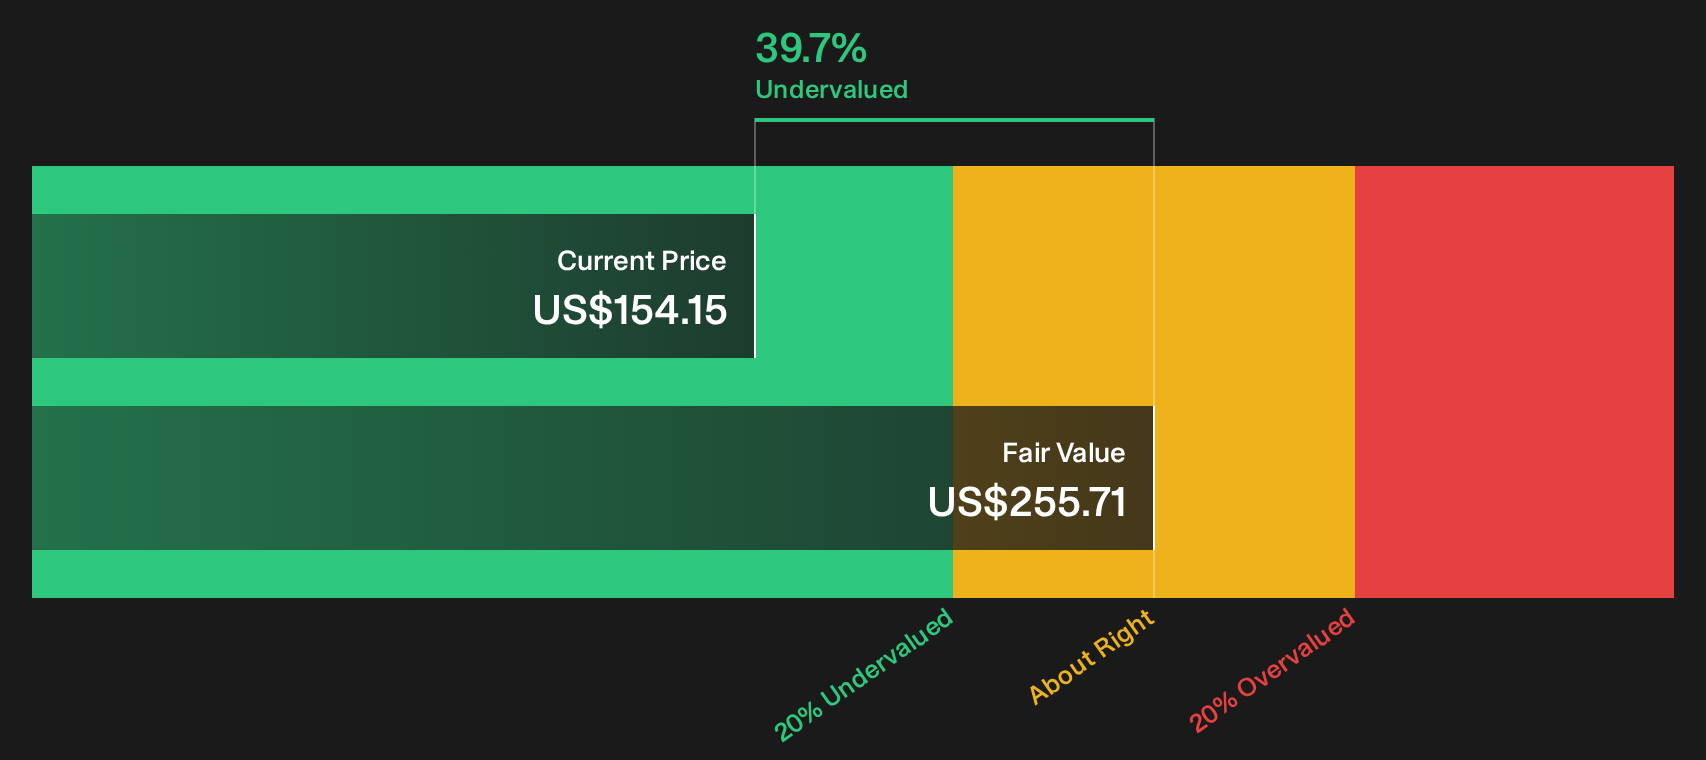
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell Aerospace for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Honeywell Aerospace can make the story feel murky, so move quickly and test the data against your own framework before sentiment shifts. To balance the concerns driving those risks with the brighter spots investors are watching, review the 4 key rewards and 3 important warning signs.
Looking for more Honeywell Aerospace investment ideas?
If you stop with Honeywell Aerospace, you risk missing other opportunities that fit your style, so put the Simply Wall St screener to work across the market.
- Target income first and scan companies that may offer meaningful cash returns through the 5 dividend fortresses.
- Hunt for resilience and check businesses with strong financial footing using the list of solid balance sheet and fundamentals (24 results).
- Spot potential early and review under-the-radar opportunities in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com