


EN
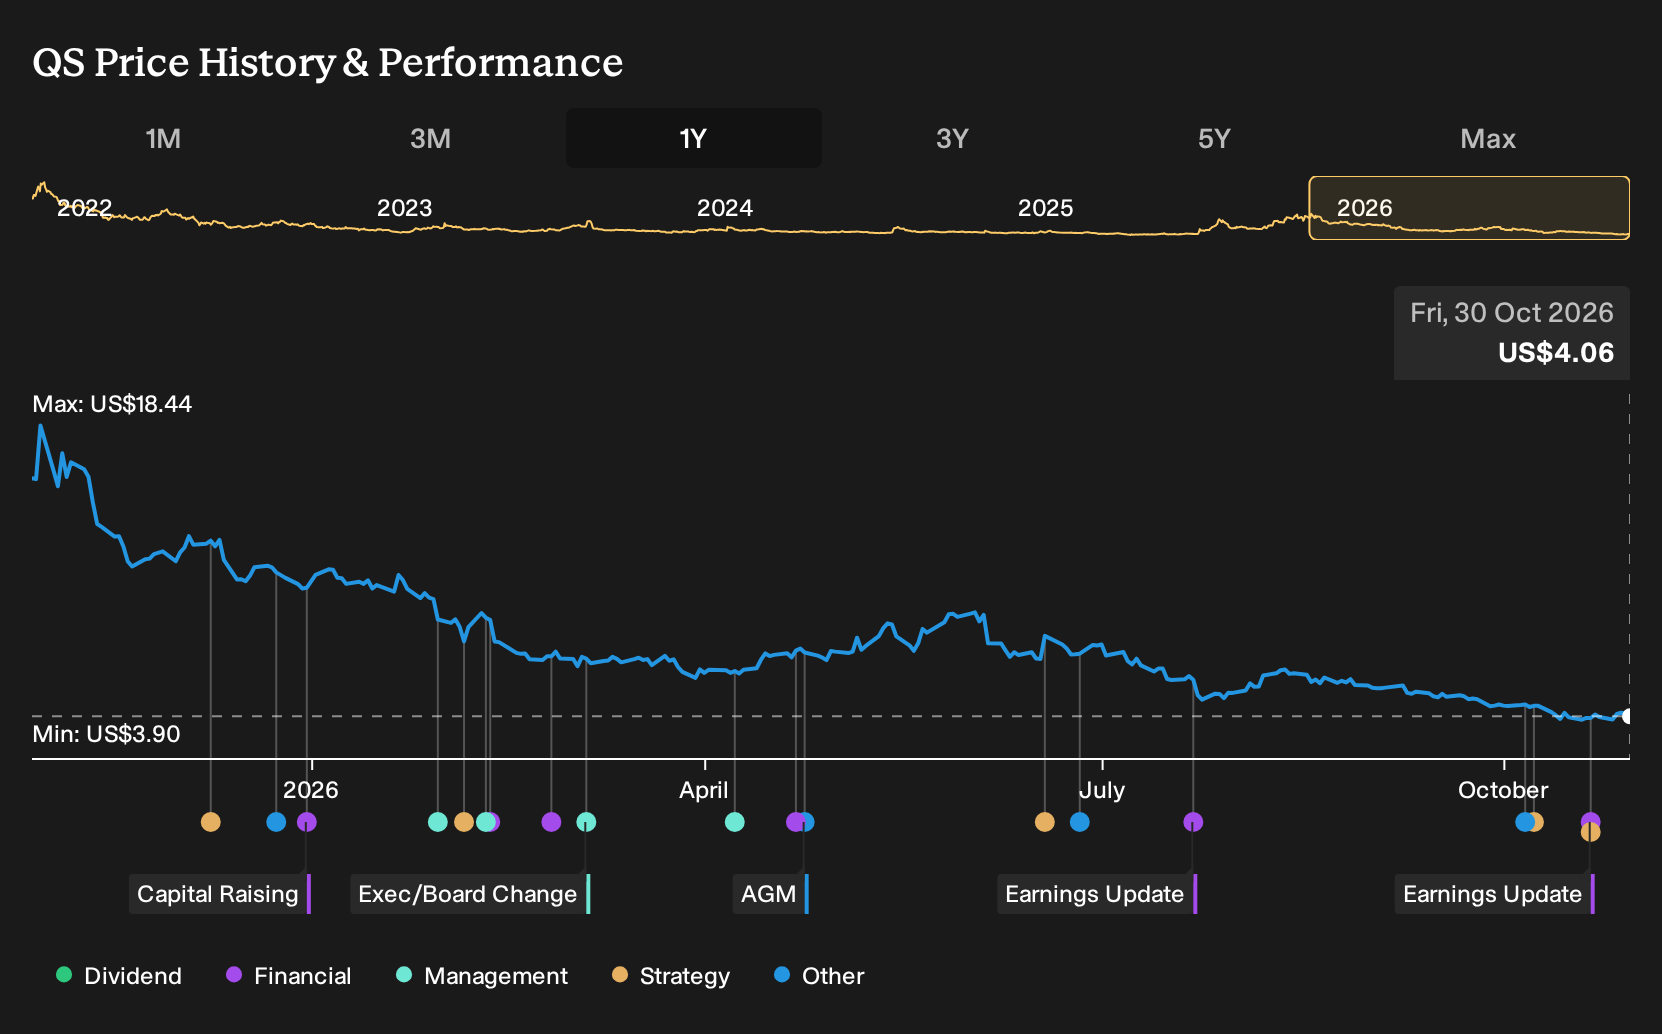
How Investors Are Reacting To QuantumScape (QS) Lower Losses And New Battery Line
- QuantumScape reported third quarter 2026 net loss of US$84.48 million and nine month net loss of US$283.52 million, both lower than the losses reported a year earlier, while also laying out plans for a 100 MWh solid state battery production line with Muehlbauer Group, targeting cell production in 2028.
- The combination of narrowing losses and a defined path toward scaled manufacturing for data center, aerospace and defense customers gives investors more concrete data points on QuantumScape's progress from pure R&D toward potential commercial deployment.
- We will now look at how QuantumScape's reduced net loss shapes the existing investment narrative built around its licensing focused model.
Scan beyond QuantumScape and see how other AI power and infrastructure suppliers line up in our hand picked list of 54 AI infrastructure stocks.
QuantumScape Investment Narrative Recap
To own QuantumScape, you need to believe its solid state technology and licensing model eventually turn years of R&D spending into material revenue, despite the business still reporting losses and no revenue today. The smaller third quarter and nine month net losses show cost discipline, but the key near term catalyst remains clear progress on Eagle Line scale up and new paid customer programs.
The biggest risk is time. Continued losses, forecast unprofitability over the next three years, and limited current billings mean any delay in moving partners toward licensing or royalties could drag out heavy cash use. The latest earnings cut the loss size, but do not fundamentally change that trade off yet.
The planned 100 MWh production line with Muehlbauer is the operational announcement most tied to today’s story. It links QuantumScape’s pilot scale Eagle Line work to a concrete blueprint for larger output serving AI data centers, aerospace and defense. This matters if you care about eventual scale rather than just lab results.
That partnership also puts execution risk into sharper focus. Engineering higher throughput equipment and hitting a 2028 production target will likely influence how soon partners feel comfortable moving from development projects into full licenses. For an investor watching catalysts, real progress against that timeline may matter as much as quarterly loss figures.
QuantumScape's current forecast framework points to revenue of US$333.3 million and earnings of US$18.1 million by 2029, from no revenue and earnings of a US$383.6 million loss today. This implies an earnings swing of about US$401.7 million and a very large yearly revenue ramp from a zero base.
Uncover why QuantumScape's fair value indicates a 33% potential upside to its current price before enthusiasm around QuantumScape's roadmap tightens that gap.
Exploring Other Perspectives
One optimistic twist in the alternate QuantumScape story is how much weight bullish analysts put on customer partnerships. Before this earnings update, they were already modeling revenue of US$171.0 million and earnings of US$9.7 million by 2029, supported by a very high implied P/E of 757.7x. That is a far more aggressive stance than the consensus view, and today’s production line announcement could push some of these narratives closer together or even further apart. You do not need to pick a side right now; however, it helps to see how widely expectations can differ before you commit your own capital.
Explore 6 other QuantumScape fair value estimates, including one that suggests up to 1994% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QuantumScape research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for QuantumScape. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QuantumScape's overall financial health at a glance.
Looking for more investment ideas beyond QuantumScape?
If this QuantumScape update has sharpened your thinking about risk, timelines, and upside, it can help to cross check those instincts against a wider watchlist. Use the Simply Wall St Screener to look for other stocks that better match your preferences on quality, balance sheet strength, and downside protection.
- If capital preservation is your priority, focus on resilience first and speculate later by starting with 29 resilient stocks with low risk scores.
- For investors who care most about durable finances and staying power through long product cycles, consider companies from the list of solid balance sheet and fundamentals (24 results).
- If you like the idea of backing smaller businesses before they are widely followed, build a shortlist using our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com