


EN
3 Asian Stocks Estimated To Be Up To 47.4% Below Their Intrinsic Value
As Asian markets navigate a period of mixed performances, with technology shares facing pressure and geopolitical tensions influencing investor sentiment, the search for undervalued opportunities becomes increasingly relevant. Identifying stocks that are trading below their intrinsic value can offer potential for significant gains, particularly in a market environment where careful analysis and strategic positioning are crucial.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥824.00 | ¥1623.70 | 49.3% |
| TOA Paint (Thailand) (SET:TOA) | THB14.50 | THB28.69 | 49.5% |
| Texhong International Group (SEHK:2678) | HK$5.13 | HK$10.10 | 49.2% |
| Shenzhen KSTAR Science and Technology (SZSE:002518) | CN¥25.56 | CN¥49.78 | 48.7% |
| Nissui (TSE:1332) | ¥1111.00 | ¥2180.59 | 49.1% |
| Morinaga Milk Industry (TSE:2264) | ¥1092.00 | ¥2134.38 | 48.8% |
| Maguro Group (SET:MAGURO) | THB17.00 | THB33.30 | 49% |
| Kumagai GumiLtd (TSE:1861) | ¥1240.00 | ¥2429.19 | 49% |
| KB Financial Group (KOSE:A105560) | ₩155500.00 | ₩308564.52 | 49.6% |
| Hanwha Ocean (KOSE:A042660) | ₩50000.00 | ₩97593.99 | 48.8% |
Let's dive into some prime choices out of the screener.
Yutong BusLtd (SHSE:600066)
Overview: Yutong Bus Co., Ltd., along with its subsidiaries, manufactures and sells buses both in China and internationally, with a market cap of CN¥64.47 billion.
Operations: The company's revenue segments include the manufacture and sale of buses in both domestic and international markets.
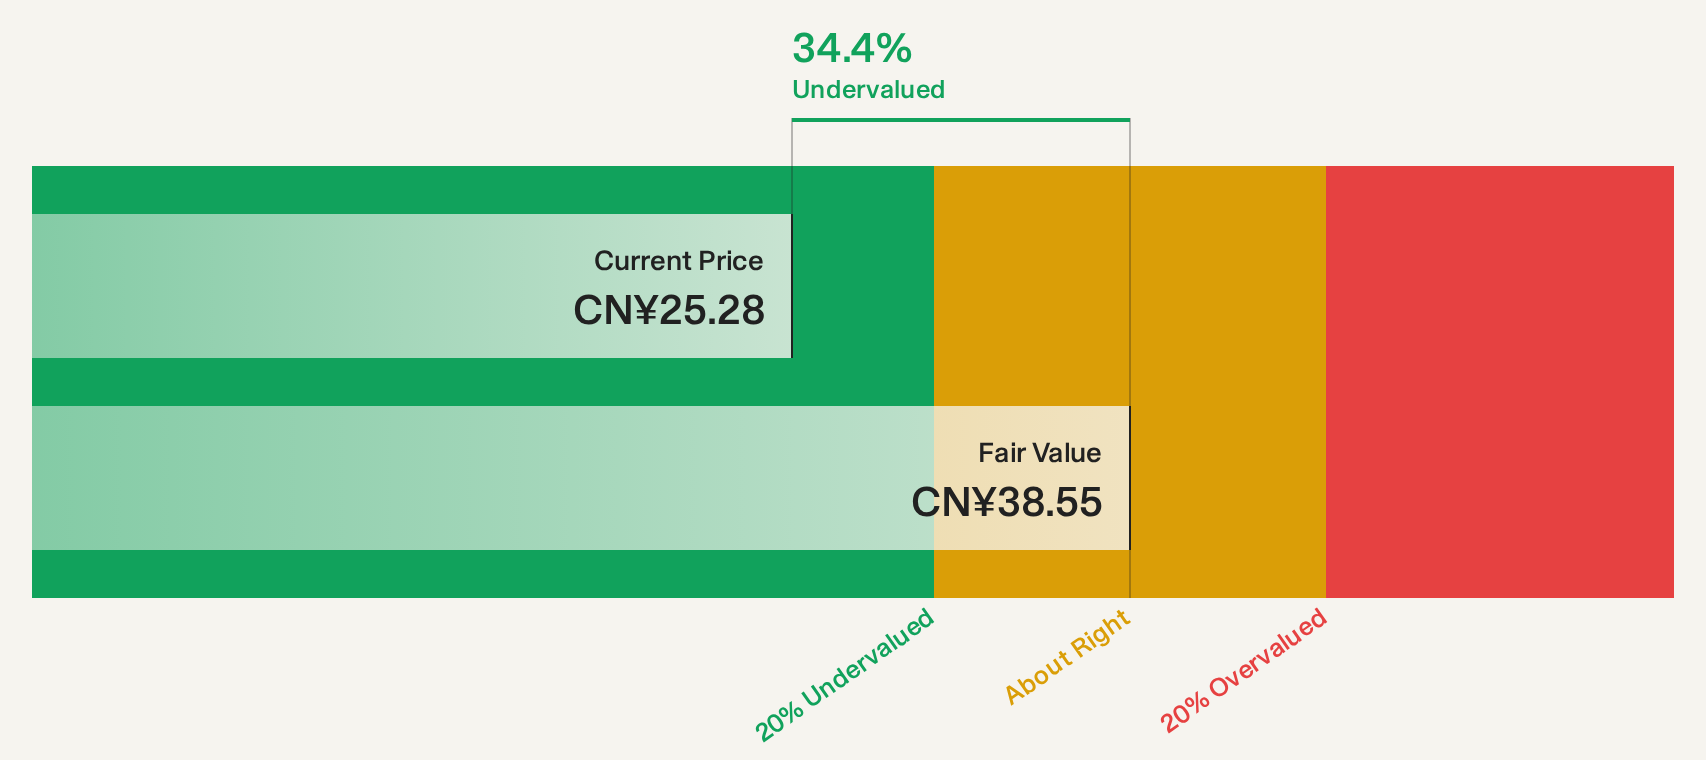
Estimated Discount To Fair Value: 13.6%
Yutong Bus Ltd. is trading at CNY 29.12, below its estimated future cash flow value of CNY 33.7, suggesting it may be undervalued on a cash flow basis. Despite a slight decline in net income for the nine months ending September 2026, the company has shown consistent earnings growth and maintains a high forecasted return on equity of 38.8% over three years. Recent expansion into Europe with new service centers enhances its operational footprint and potential revenue streams.
- In light of our recent growth report, it seems possible that Yutong BusLtd's financial performance will exceed current levels.
- Dive into the specifics of Yutong BusLtd here with our thorough financial health report.
China National Chemical Engineering (SHSE:601117)
Overview: China National Chemical Engineering Co., Ltd. (SHSE:601117) operates in the engineering and construction sector, focusing on chemical and petrochemical projects, with a market cap of approximately CN¥43.41 billion.
Operations: China National Chemical Engineering Co., Ltd. generates revenue primarily through its engineering and construction services, specializing in chemical and petrochemical projects.
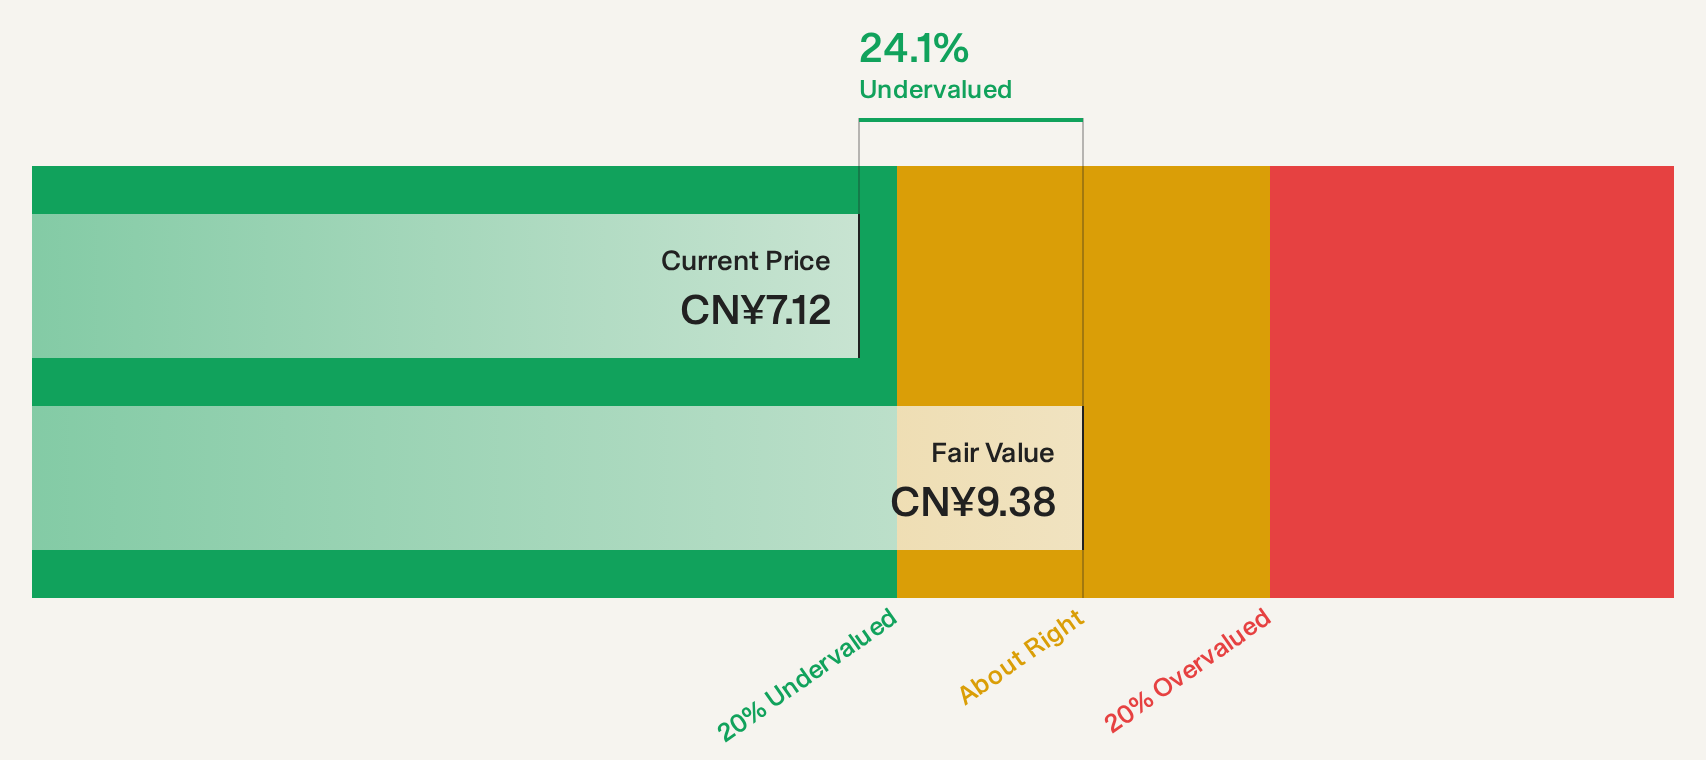
Estimated Discount To Fair Value: 24.2%
China National Chemical Engineering is trading at CN¥7.11, below its estimated future cash flow value of CN¥9.38, indicating undervaluation based on cash flows. Recent earnings for the nine months ending September 2026 show modest growth in net income to CNY 4,324.24 million from the previous year. Despite a slower forecasted earnings growth rate of 7.6% annually compared to the market, it trades at a good relative value within its industry and peers.
- Upon reviewing our latest growth report, China National Chemical Engineering's projected financial performance appears quite optimistic.
- Click here to discover the nuances of China National Chemical Engineering with our detailed financial health report.
Mizuho Financial Group (TSE:8411)
Overview: Mizuho Financial Group, Inc. operates in banking, trust banking, securities, and other financial services across Japan and internationally with a market cap of approximately ¥18.71 trillion.
Operations: Mizuho Financial Group's revenue segments include The Retail & Business Banking Company at ¥1.03 billion, The Global Corporate & Investment Banking Company at ¥860.00 million, The Corporate & Institutional Company at ¥796.38 million, The Global Markets Company at ¥804.74 million, and The Asset Management Company at ¥71.61 million.
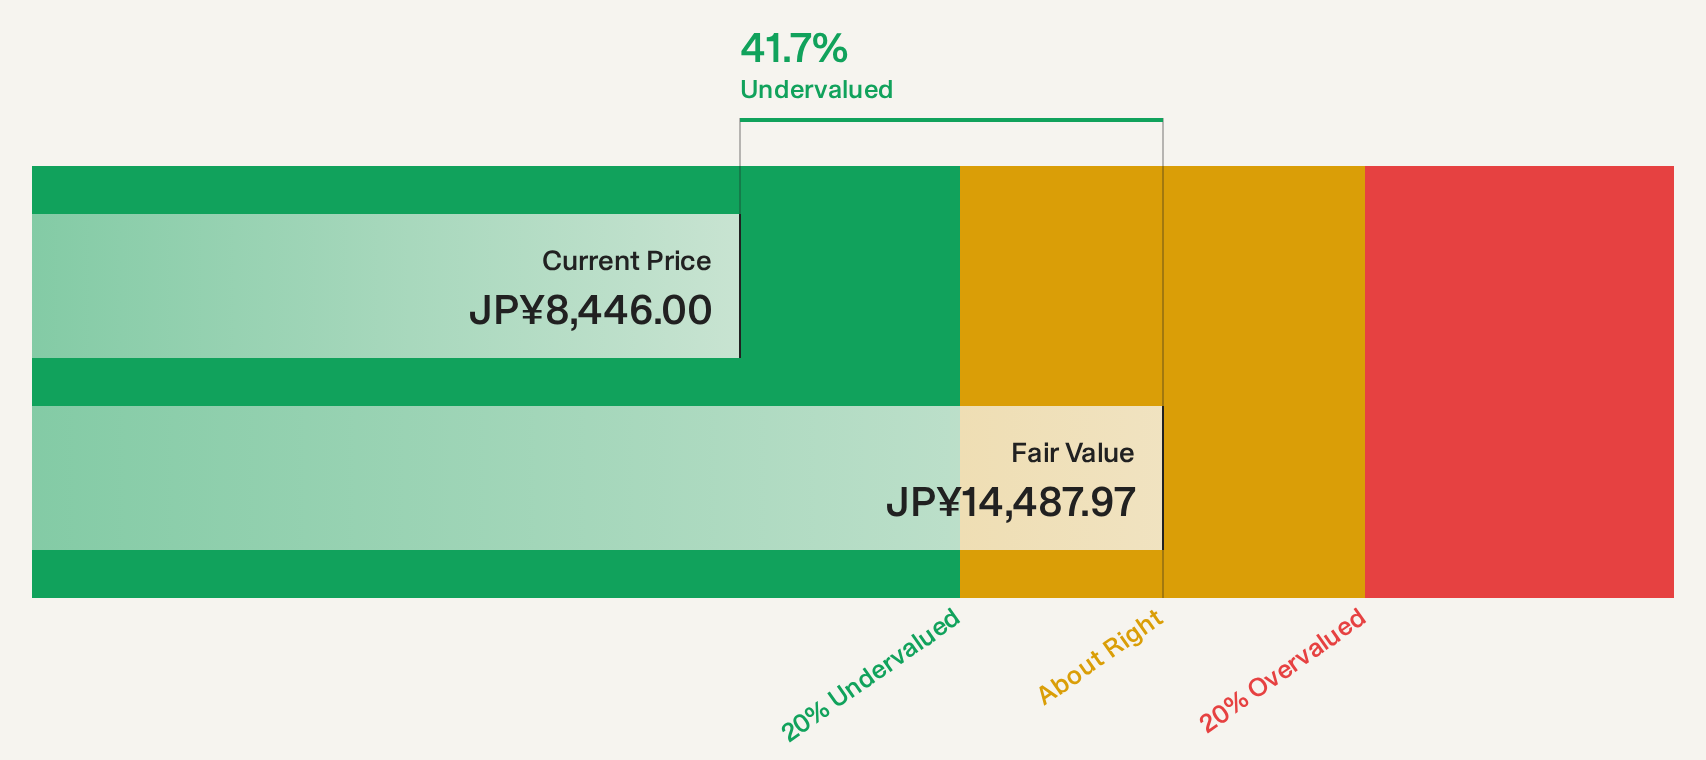
Estimated Discount To Fair Value: 47.4%
Mizuho Financial Group trades at ¥7,749, significantly below its estimated future cash flow value of ¥14,729.3, highlighting potential undervaluation based on cash flows. The company has completed a share buyback of 1% for ¥199.99 billion and issued $1 billion in perpetual subordinated notes to bolster capital. Despite slower forecasted earnings growth of 8.2% annually compared to the Japanese market, it presents good relative value within its industry and peers.
- Our expertly prepared growth report on Mizuho Financial Group implies its future financial outlook may be stronger than recent results.
- Unlock comprehensive insights into our analysis of Mizuho Financial Group stock in this financial health report.
Next Steps
- Discover the full array of 193 Undervalued Asian Stocks Based On Cash Flows right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com