


EN
Is Sankyu (TSE:9065) Undervalued After Its Earnings Guidance Revision?
Sankyu (TSE:9065) has drawn fresh attention after announcing partial corrections to its earnings guidance for the year ending March 31, 2027, along with a board meeting to revise its non-consolidated financial forecast.
Recent trading has been relatively steady, with the share price at ¥1,652 after a 1-month share price return of 3.8% and a 7-day gain of 1.26%. However, the 90-day share price return is down 12.8%, suggesting near term momentum has cooled, while the 1-year total shareholder return of 8.22% and 3-year total shareholder return of 91.21% point to a stronger longer run picture that the latest guidance revisions now feed into.
Scan how investors are repricing guidance risk around Sankyu and similar businesses by reviewing our curated list of list of solid balance sheet and fundamentals (21 results).
Bulls point to Sankyu’s long run returns and updated earnings guide, while bears focus on the softer 90 day share price. Which side does the current valuation really support?
Price-to-Earnings of 12.1x: Is it justified?
On simple valuation metrics, Sankyu looks inexpensive, with a P/E of 12.1x while the shares last closed at ¥1,652 and the stock is described as trading at good value versus both peers and the wider logistics sector.
The P/E ratio compares what investors are currently paying for each unit of current earnings, which matters a lot for a mature logistics and engineering group where profitability and cash generation tend to be more stable than early stage ventures.
For Sankyu, the picture skews toward a modestly priced earner. Earnings are forecast to grow 3.31% per year and earnings have grown 7.7% per year over the past 5 years, yet the P/E sits at 12.1x, which is flagged as good value compared to peers and industry. That combination suggests the market is not assigning a premium to this earnings stream and that valuations could move toward a higher level that more closely reflects the fair P/E estimate of 14.1x if sentiment improves.
Compared with the JP Logistics industry average P/E of 14.1x and a peer average of 24.9x, Sankyu trades at a clear discount. The stock is also assessed as trading at 16.7% below an estimated fair value, which reinforces the picture of investors paying less than both sector norms and a modelled fair multiple for the same earnings power.
Explore the SWS fair ratio for Sankyu.
Result: Price-to-Earnings of 12.1x (UNDERVALUED)
Still, the recent 90 day share price decline and the need to correct earnings guidance underline how quickly sentiment toward Sankyu can reset if expectations shift again.
Find out about the key risks to this Sankyu narrative.
Another view using the SWS DCF model
The P/E ratio presents Sankyu as inexpensive, and the SWS DCF model also indicates undervaluation, with the shares at ¥1,652 versus an estimated future cash flow value of ¥1,984.05. If both earnings multiples and cash flow calculations point in the same direction, the question becomes where the real margin of safety lies.
For a closer look at how this cash flow view is built and what assumptions sit behind it, Look into how the SWS DCF model arrives at its fair value.
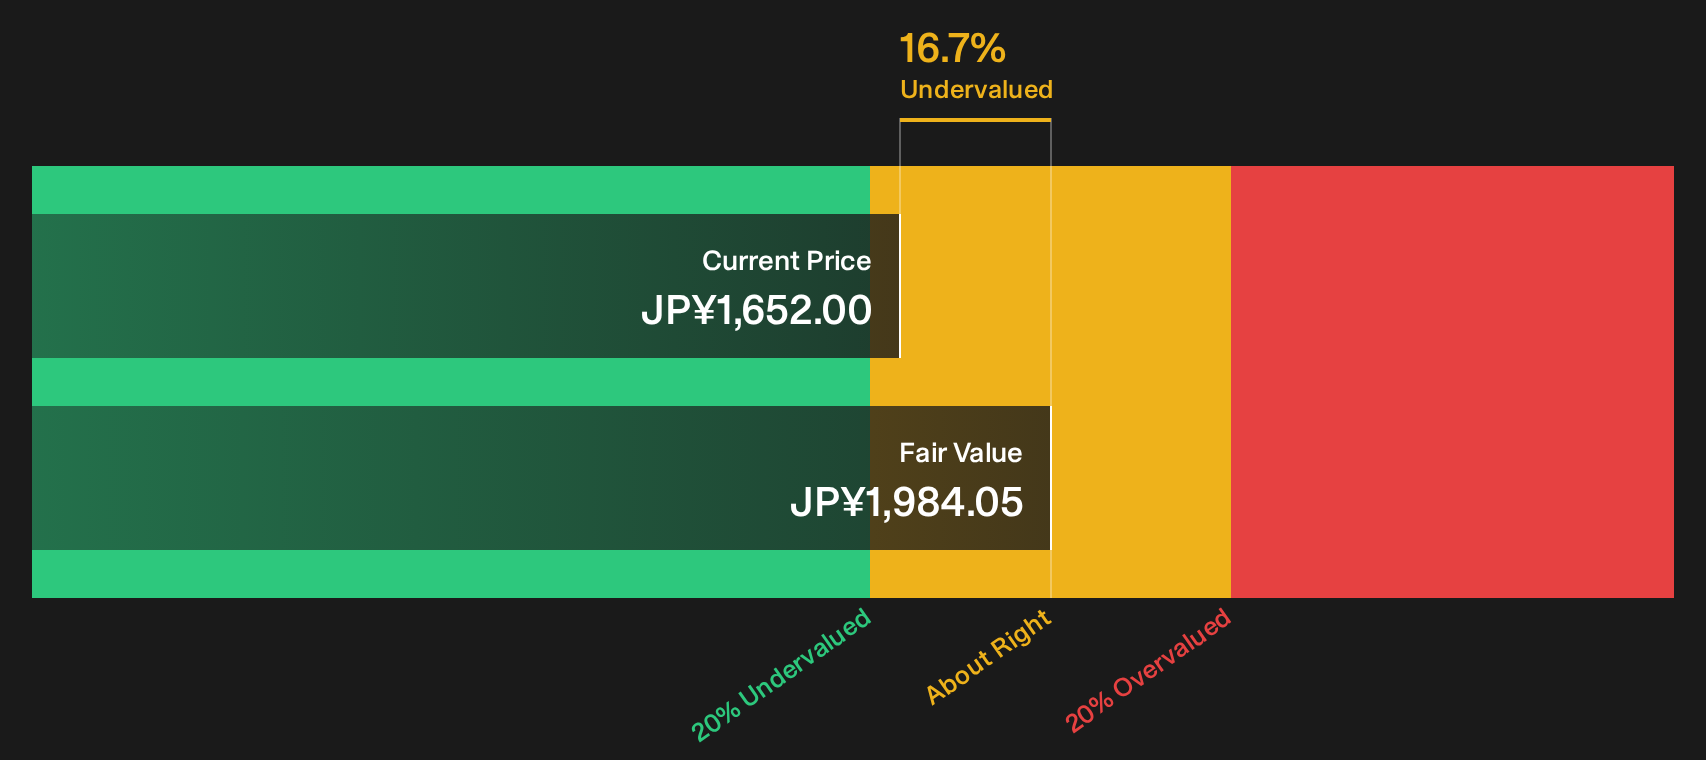
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sankyu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sankyu might look mixed at first glance, yet the underlying data is there for you to scrutinize directly and decide how you feel about the risk reward trade off. To see which potential upsides our work is highlighting, you can take a closer look at the 6 key rewards.
Looking for more Sankyu sized investment ideas?
Do not stop with Sankyu. Broaden your watchlist and pressure test your thinking against other opportunities that match the kind of quality and pricing you care about.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (21 results) that filters for resilient balance sheets and fundamentals.
- Hunt for mispriced opportunities using a 16 high quality undervalued stocks that highlights companies where quality and valuation look out of sync.
- Build a steadier income stream through a 28 dividend fortresses focused on higher yielding businesses that still keep an eye on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com