


EN
Vicor (VICR) Reported Stronger Earnings, Is The Pullback A Bargain?
Vicor earnings jolt investor focus
Vicor (VICR) has drawn fresh attention after reporting third quarter and nine month results on 20 October 2026, with revenue, net income, and earnings per share all higher than a year earlier.
Vicor’s share price has been volatile, with the stock falling 7.52% on the day to US$191.09 and down 38.14% over the past month, yet still posting a 63.52% year to date share price return and a 1 year total shareholder return of 110.61%, which reflects strong longer term price momentum despite recent profit taking around the earnings reaction.
Scan beyond Vicor and see how other power and industrial technology plays are reacting to this kind of earnings momentum with our hand picked 19 high quality undiscovered gems.
Vicor has just reported much stronger earnings, yet the share price has dropped sharply from recent highs. Does that pullback improve the risk reward for new buyers, or does it mostly reflect froth coming out of the story before valuation work even begins?
Most Popular Vicor Narrative: 51.5% Undervalued
Vicor’s most followed valuation narrative pegs fair value at $393.75, which is well above the latest close at $191.09 and sets a high bar for what needs to go right in the story.
The accelerated adoption of high power, high density AI computing in data centers is still a live driver, and Vicor’s second generation vertical power delivery reaching 3 amps per mm² for a lead customer with a target of over 5 amps per mm² by late 2026 or early 2027 supports the view that higher performance products can support future revenue and gross margin.
See why 34 investors see Vicor as 51% undervalued.
Result: Fair Value of $393.75 (UNDERVALUED)
Still, Vicor’s narrative can break if insider selling persists at scale or if legal and licensing related costs keep climbing and squeeze profitability harder than expected.
Find out about the key risks to this Vicor narrative.
Another view on Vicor valuation
The narrative points to Vicor trading well below a US$393.75 fair value, yet the SWS DCF model tells a different story. On that cash flow based view, the shares at US$191.09 sit above an estimated value of US$158.71, which leans toward overvaluation. Which lens do you trust more for a long term call?
For investors who want to see how a cash flow framework can clash with a story driven valuation, Look into how the SWS DCF model arrives at its fair value.
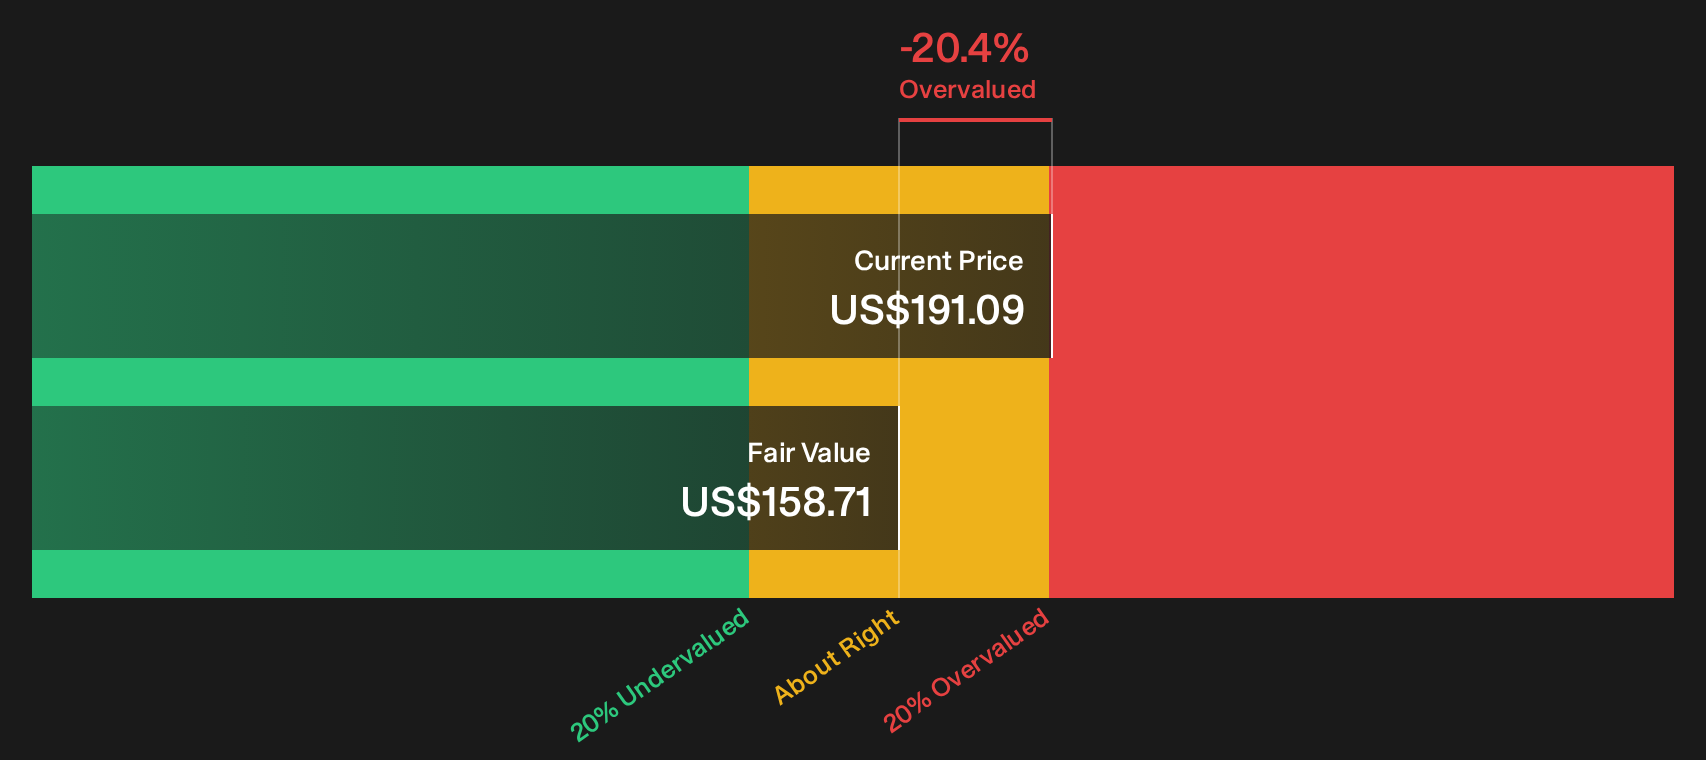
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vicor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of upbeat and cautious signals around Vicor feels split to you, move fast and pressure test the story against the data yourself. Then weigh both sides of the ledger with 3 key rewards and 3 important warning signs.
Looking for more Vicor style investment ideas?
Vicor’s story is just one option. Use this momentum to broaden your watchlist and stack the odds of finding quality setups in your favor.
- Target resilient payers that aim to keep income flowing in your portfolio with the 5 dividend fortresses.
- Hunt for quality businesses trading below their implied worth by scanning the 33 high quality undervalued stocks.
- Zero in on companies with balance sheets that look built to absorb shocks using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com