


EN
How Investors Are Reacting To Origin Energy Stock As LNG Prices Lift Revenue
- Origin Energy reported a sharp rise in its share of APLNG revenue in the latest quarter, driven by higher oil linked LNG prices rather than extra production volumes, while hedge positions on oil and currency moved into loss territory.
- The mix of stronger LNG pricing and negative hedging results highlights how Origin Energy’s cash flows from APLNG can swing with oil indexation timing and risk management choices, even when physical output stays relatively stable.
- We will now look at how Origin Energy's investment narrative could be affected by stronger oil linked LNG pricing at APLNG.
Scan how Origin Energy’s LNG leverage compares with peers by zeroing in on 41 power grid technology and infrastructure stocks, which is positioned to benefit from energy pricing shifts linked to global fuel benchmarks.
Origin Energy Investment Narrative Recap
To own Origin Energy, you need to be comfortable with a story that leans on APLNG cash generation, relatively flat group revenue expectations and heavy spending on renewables, batteries and digital platforms such as Kraken and Octopus. The latest jump in APLNG revenue, driven by higher oil linked LNG pricing, reinforces that LNG still carries a lot of weight in the mix.
The main near term swing factor is how realised LNG pricing and hedging outcomes feed through to distributions from APLNG and fund the capital intensive build out of batteries, the Yanco Delta wind project and platform expansion. The biggest immediate risk is that hedging losses or softer cash conversion make it harder to support both investment plans and a dividend that is not well covered by free cash flow.
There have been no fresh company announcements tied directly to this APLNG pricing update, so the most useful reference point is still Origin Energy’s existing capital program and guidance around electrification and distributed energy. Those plans already assume cash from Energy Markets and APLNG helps fund 1.8 GW of grid scale batteries, the 1.5 GW Yanco Delta wind farm and continued rollout of Kraken and Octopus.
The recent quarter shows how sensitive that funding pool is to oil linked LNG prices and hedging choices. Stronger realised LNG prices can support those long lead projects when hedging works in Origin Energy’s favour. By contrast, weaker trading outcomes or higher capital and compliance costs could pressure returns on that spend and make execution on batteries, renewables and digital platforms even more important to watch.
Origin Energy is described in the context of analyst expectations that revenues will remain relatively flat, while earnings are projected to fall from A$1.6b today to a consensus A$1.2b by 2029. This outlook implies revenues of about A$15.4b and an earnings decline of A$400m by that forecast year.
Uncover why Origin Energy's fair value aligns with its current price.
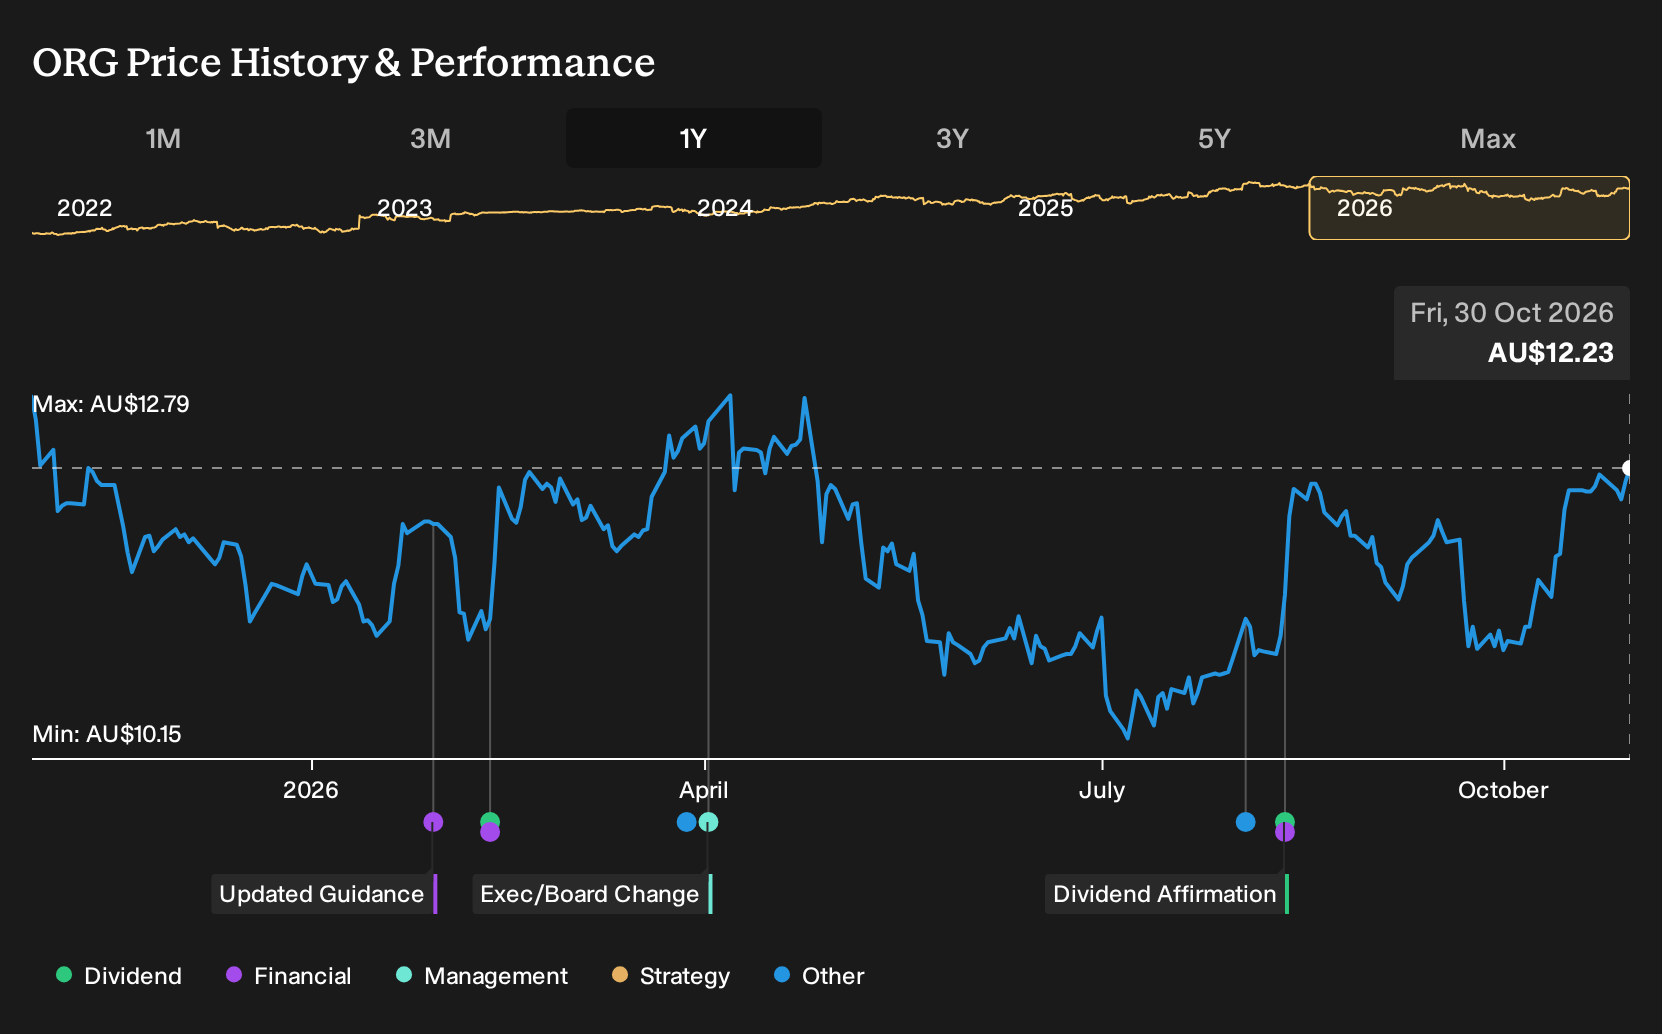
Exploring Other Perspectives
Four private investors in the Simply Wall St Community put Origin Energy’s fair value between A$12.17 and A$24.34, a spread that shows how far opinions can stretch. You are weighing that against LNG price swings, capital heavy batteries and wind projects, and electrification trends that could all shift how the story plays out.
Explore 3 other Origin Energy fair value estimates, including one that suggests it could be worth just A$12.17.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Origin Energy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Origin Energy. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Origin Energy's overall financial health at a glance.
Looking for more Origin Energy style ideas?
If the Origin Energy story has sharpened your thinking about risk, income and balance sheet strength, it can help to line it up against other opportunities before making a call.
- For investors who want income with a cushion, scan for companies that look like genuine payout heavyweights using 4 dividend fortresses.
- If capital preservation sits high on your list, filter for businesses with steadier risk profiles by running a 6 resilient stocks with low risk scores.
- When you want potential upside without stretching on quality, use the 15 high quality undiscovered gems to spot underfollowed stocks with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com