


EN
Benchmark Electronics (BHE) Raised Guidance Puts Its Fair Value Story Back In Focus
What the latest guidance means for Benchmark Electronics investors
Benchmark Electronics (BHE) raised its 2026 earnings outlook after reporting record third quarter revenue and quicker earnings growth than sales, supported by broadening demand and work for an AI infrastructure customer.
The share price reaction has been choppy, with Benchmark Electronics falling 5.46% on the day to US$68.37 and down 21.76% over 30 days. This is despite a year-to-date share price return of 55.74% and a 3-year total shareholder return of about three times.
Compare Benchmark Electronics with other AI infrastructure beneficiaries and see which stocks our screen has surfaced as potential standouts in this theme through 54 AI infrastructure stocks.
The stock has swung sharply even as Benchmark Electronics trades below both analyst targets and some intrinsic value estimates. The central question is whether fair value now tracks the guidance or reflects the recent price reset.
Most Popular Narrative: 20.5% Undervalued
Benchmark Electronics last closed at $68.37 while the most followed narrative pegs fair value at $86. This implies a sizeable valuation gap that relies heavily on its AI infrastructure and medical exposure playing out as expected.
Benchmark Electronics is positioned to benefit from surging demand for advanced computing and AI infrastructure, now supported by 41% and 71% year-over-year AC&C revenue growth in Q1 and Q2 2026 driven by clustered AI and on prem cloud programs, and by recognition as HPE’s 2026 Manufacturing Partner of the Year. Together these factors point to further contribution from upcoming high performance computing ramps into 2027 that can support revenue and gross margin.
See why 7 investors see Benchmark Electronics as 20% undervalued.
Result: Fair Value of $86 (UNDERVALUED)
Still, the Benchmark Electronics narrative could be shaken if AI, Semi Cap and medical orders fall short, or if supply chain tightness again crimps margins.
Find out about the key risks to this Benchmark Electronics narrative.
Another View: Benchmark Electronics Through A Cash Flow Lens
The first fair value narrative for Benchmark Electronics leaned heavily on earnings multiples and analyst targets. A different lens, the SWS DCF model, prices the shares at about $51.85, which sits below the current $68.37 level. That points to a stock the cash flow math currently views as overvalued and raises the question of which story is more persuasive when forecasts shift.
To unpack how those long term cash flow assumptions are built and stress test them against your own expectations, take a closer look at Look into how the SWS DCF model arrives at its fair value..
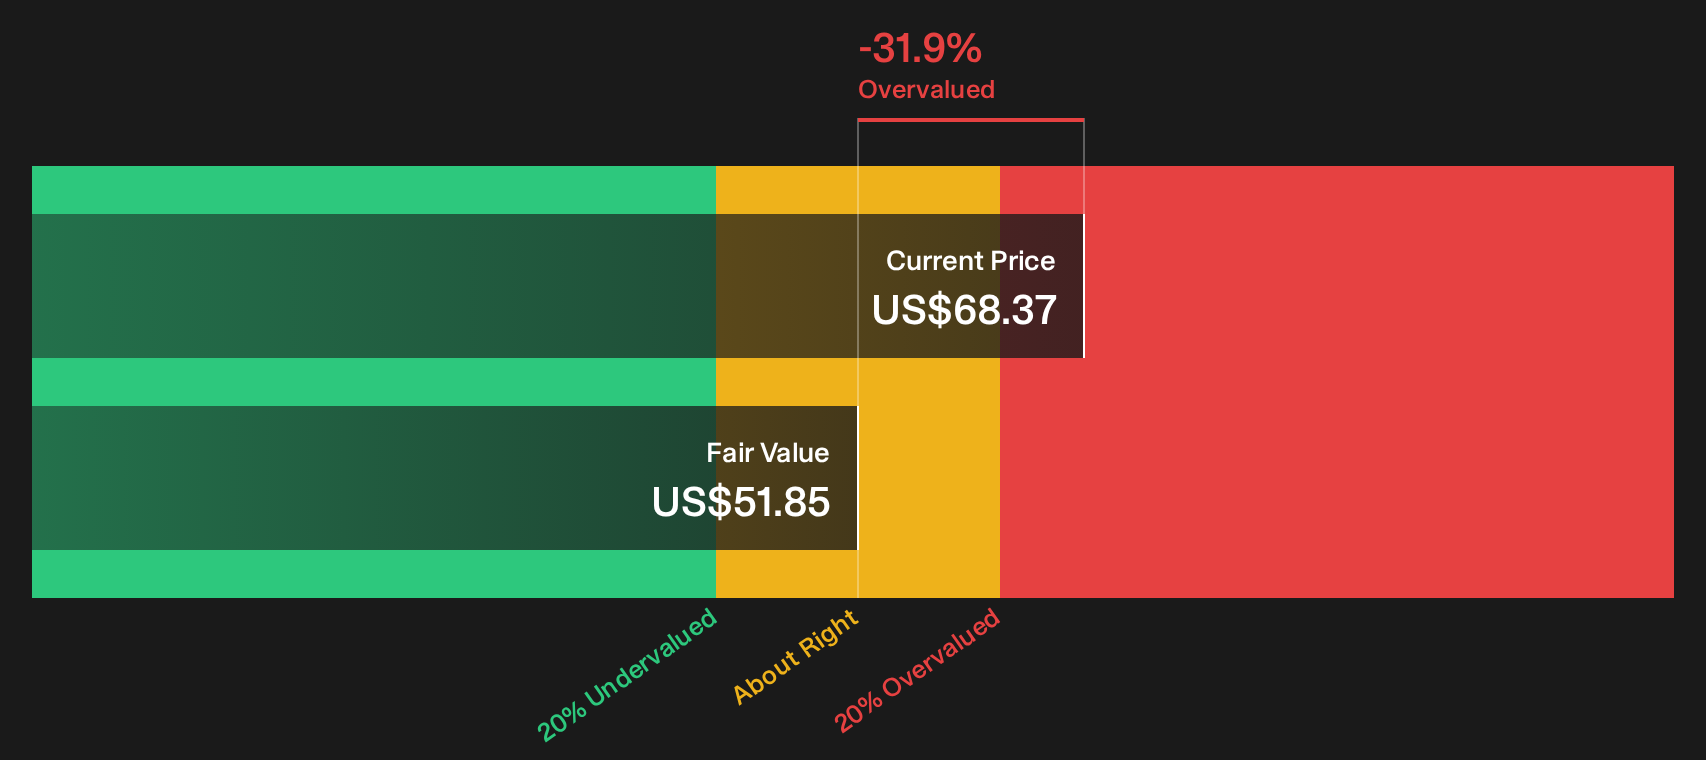
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Benchmark Electronics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Benchmark Electronics story sounds promising, yet some signals are clearly more mixed. Move quickly to inspect the underlying numbers yourself and pressure test the bullish and cautious arguments side by side using 3 key rewards and 1 important warning sign.
Looking for more Benchmark Electronics investment ideas?
If you stop with Benchmark Electronics, you risk missing other opportunities that fit your style. Use the Simply Wall Street screener to quickly surface fresh candidates with clear fundamentals, resilient balance sheets, or income potential in just a few focused filters.
- Chase upside with quality by scanning a curated set of 19 high quality undiscovered gems that pair strong fundamentals with under the radar market attention.
- Prioritise resilience by running through a 29 resilient stocks with low risk scores that filters for businesses with sturdier risk profiles and fewer financial red flags.
- Build a more defensive core by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights companies with healthier leverage and stronger liquidity support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com