


EN
Red Rock Resorts (RRR) Could Be 33% Undervalued On New California Casino Launch
Red Rock Resorts (RRR) is in focus after subsidiary Station Casinos opened the North Fork Mono Casino in California’s Central Valley, a US$725 million resort developed with the North Fork Rancheria of Mono Indians.
For context, Red Rock Resorts’ share price has slipped over the past quarter, with a 90 day share price return down 25.1% and year to date share price return down 22%, while the 3 year total shareholder return of 30.1% still reflects a stronger longer run outcome.
Scan for other regional gaming operators putting fresh capital to work and compare how they stack up to Red Rock Resorts using our hand picked 19 high quality undiscovered gems.
Red Rock Resorts has a new California project on the board, yet the share price has retreated sharply. With analyst targets and intrinsic estimates both higher than the market, the question is where a reasonable fair value range really sits now.
Most Popular Narrative: 33% Undervalued
Red Rock Resorts is priced at $49.15, while the most followed narrative pegs fair value at about $73.39. This leaves a wide valuation gap that hinges on how its development pipeline and cash generation hold up against higher leverage and spending.
The company's ongoing and upcoming large scale capital expenditures at Durango, Green Valley Ranch, Sunset Station and the North Fork tribal casino, together with guided 2026 capex of US$375 million to US$425 million, require substantial funding at a time when net debt is about US$3.5b and net leverage has risen above 4x. Any shortfall in project returns, delay or cost pressure could weigh on free cash flow and keep net margins and earnings under pressure.
See why 2 investors see Red Rock Resorts as 33% undervalued.
Result: Fair Value of $73.39 (UNDERVALUED)
Still, the heavy renovation spend across Green Valley Ranch, Durango and Sunset Station, along with net debt near US$3.5b and leverage above 4x, could pressure Red Rock Resorts if returns disappoint or disruptions linger.
Find out about the key risks to this Red Rock Resorts narrative.
Another View: What Multiples Say About Red Rock Resorts
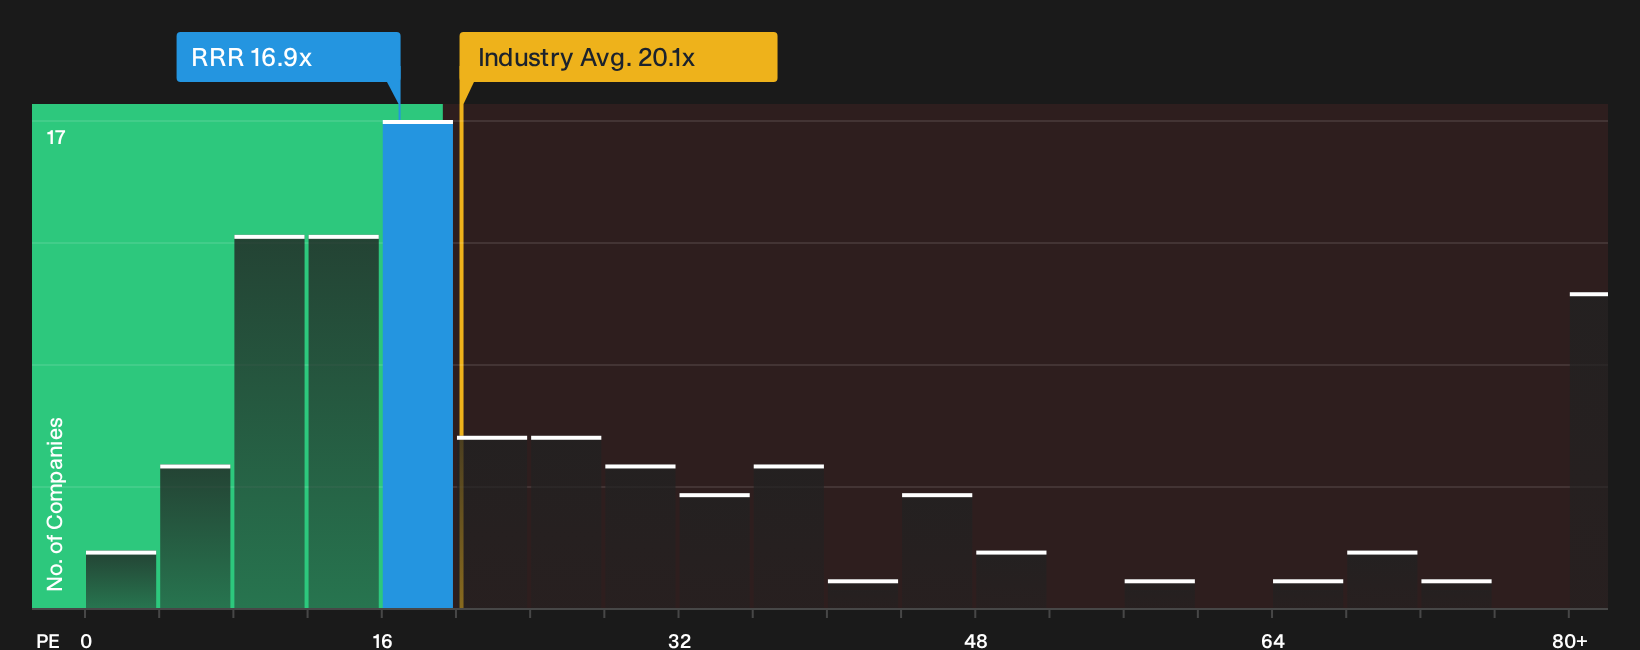
That 33% undervalued narrative leans heavily on future cash flow, yet the market is also pricing Red Rock Resorts on earnings today. At a 16.9x P/E, the stock trades above peer averages at 14.1x, but below both the US Hospitality group on 20.1x and a fair ratio of 21.3x. Investors are left weighing whether that gap signals a valuation cushion or simply reflects real business and balance sheet risks that keep the share price pinned down.
For a closer look at how this earnings based view lines up against price, and where the market could shift if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Red Rock Resorts pulling in both concern and optimism, you have a clear split in sentiment right in front of you. Move fast, stress test the assumptions that matter most to you, and weigh up the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Red Rock Resorts?
If Red Rock Resorts has sharpened your focus on value and risk, do not stop here. Broaden your opportunity set now so you are not reacting after the market has already moved.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that can help you sidestep fragile businesses.
- Hunt for mispriced opportunities with strong quality markers through a focused list of 33 high quality undervalued stocks that might deserve a place on your radar.
- Prioritize steadier profiles by filtering for 29 resilient stocks with low risk scores so you can keep potential drawdowns in check while still putting capital to work.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com