


EN
Ligand Pharmaceuticals (LGND) Raises EPS View As Royalty Growth Keeps Undervalued Narrative Alive
Q3 2026 earnings reset the baseline
Ligand Pharmaceuticals (LGND) gave investors a mixed picture in its latest update. Q3 2026 brought a net loss alongside sharply lower revenue, yet management still raised full year adjusted EPS guidance and leaned into its royalty focused model.
The latest Q3 reset comes after a powerful move in the shares, with the 1-day share price return of 1.71% and 7-day gain of 6.33% feeding into a 69.77% year to date rise, while the 3-year total shareholder return of almost 5x signals momentum that is still firmly in play.
Compare Ligand Pharmaceuticals' royalty focused model with other high quality, cash generative plays by screening for 33 high quality undervalued stocks that share a similarly capital light profile.
Ligand Pharmaceuticals has already delivered a gain of nearly 70% this year, following a backdrop of Q3 losses and rising royalty optimism. Is the bigger opportunity now behind the stock, or still in front of it based on valuation?
Most Popular Narrative: 6% Undervalued
On the most followed view, Ligand Pharmaceuticals screens as modestly undervalued, with a narrative fair value of $344.25 versus a last close of $322.75. That gap is framed around how far the royalty model can scale.
Expansion of Ligand Pharmaceuticals’ high margin royalty portfolio through the completed XOMA Royalty acquisition, which adds more than 120 assets including additional commercial products and late stage programs, is expected to widen the base of recurring royalty revenue and support higher earnings power as the assets mature.
See why 6 investors see Ligand Pharmaceuticals as 6% undervalued.
Result: Fair Value of $344.25 (UNDERVALUED)
Still, this Ligand Pharmaceuticals story can change quickly if major royalty contributors like Filspari underperform, or if drug pricing pressure caps those expected cash flows.
Find out about the key risks to this Ligand Pharmaceuticals narrative.
Another View: Multiples Paint A Tougher Picture For Ligand Pharmaceuticals
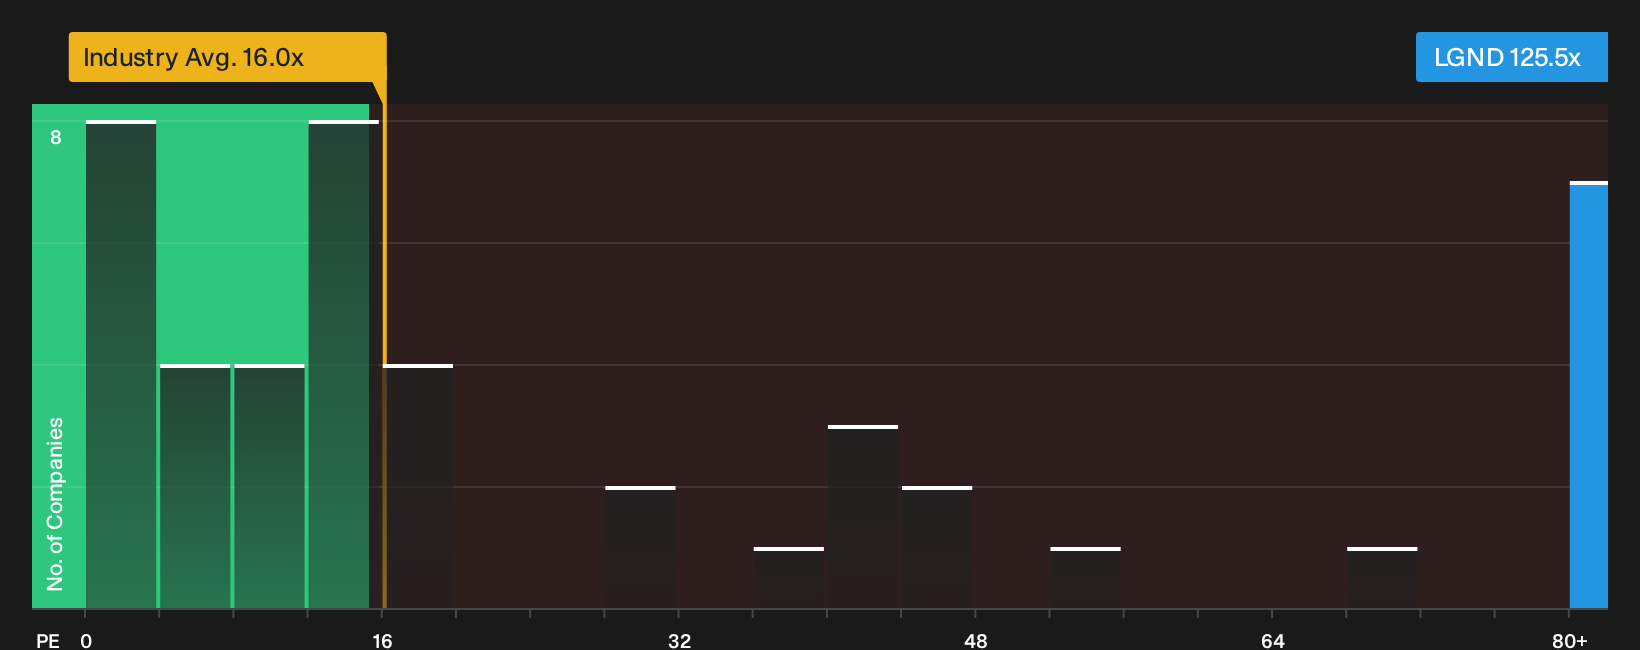
The narrative fair value pegs Ligand Pharmaceuticals as modestly undervalued, yet the market ratio work tells a less forgiving story. The current P/E of 125.5x is well above the estimated fair ratio of 51.6x, the US Pharmaceuticals average of 16x, and the peer group at 58.9x.
That sort of gap suggests investors are paying a steep premium today, which raises the risk that any disappointment in future earnings or royalties could hit the share price harder than the narrative model implies. The key question is whether the business can keep justifying that kind of multiple over the longer term.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ligand Pharmaceuticals will always split opinion, so move quickly, review the key risks and potential upsides, and weigh the 3 key rewards and 3 important warning signs.
Looking for more Ligand Pharmaceuticals style ideas?
Do not stop your research with Ligand Pharmaceuticals. Broaden your watchlist now, or you risk missing listed opportunities that better match your goals and risk limits.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that highlights companies combining financial strength with underlying fundamentals you can actually scrutinize.
- Hunt for mispriced quality through a curated 19 high quality undiscovered gems that surfaces lesser known businesses backed by solid numbers rather than hype.
- Prioritize capital protection first and seek upside second with a 29 resilient stocks with low risk scores focused on companies that carry lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com