


EN
Pop Mart International Group (SEHK:9992) Reports A 45% To 50% Revenue Drop, Is The Valuation Case Still Intact?
Pop Mart International Group (SEHK:9992) has kicked off a sizeable share repurchase program after reporting an unaudited revenue decline of 45% to 50% for the third quarter of 2026 across its key regions.
Investors have reacted sharply to the third quarter revenue shock. The 1 day share price return of 4.82% and 7 day gain of 2.43% come after a 30 day share price decline of 11.60% and a year to date share price fall of 30.14%. The 1 year total shareholder return is down 38.05%, but remains very large over 3 and 5 years, which suggests momentum has faded in the short term even though long term holders in Pop Mart International Group are still sitting on sizeable gains.
Spot opportunities beyond Pop Mart International Group by scanning our hand-picked 204 high quality undervalued stocks, which combine compressed sentiment with stronger fundamentals.Pop Mart International Group now pairs a sharp revenue setback with fresh buybacks in the market. Does that combination justify buying after the drop, or does patience offer a better entry on the same story?
Preferred P/E of 11.3x for Pop Mart International Group: Is it justified?
On simple valuation checks, Pop Mart International Group trades on a P/E of 11.3x, which screens as expensive next to several reference points even after the recent share price slump to HK$134.9.
The P/E ratio compares the current share price with the last reported earnings per share. For a consumer focused retailer like Pop Mart International Group, this metric effectively shows how much investors are willing to pay today for each unit of current profit.
Here that willingness looks elevated. The stock carries a higher P/E than both the Hong Kong Specialty Retail industry average of 8.9x and the peer group average of 10.9x. An estimated fair P/E based on broader market relationships sits lower again at 10.3x. Taken together, this points to the market putting a richer tag on Pop Mart International Group’s earnings than on comparable retailers, even though internal modelling suggests a level the valuation could move towards that is closer to the 10.3x fair ratio.
Explore the SWS fair ratio for Pop Mart International Group.
Result: Price-to-Earnings of 11.3x (OVERVALUED)
Still, the sharp third quarter revenue setback and the scale of the buyback commitment could both turn into pressure points if cash generation or demand softens further.
Find out about the key risks to this Pop Mart International Group narrative.
Another View on Pop Mart International Group’s Value
The P/E screens Pop Mart International Group as expensive, yet the SWS DCF model paints a different picture. On that cash flow view, the estimated value sits at HK$296.18 per share against a market price of HK$134.9, which flags the stock as deeply undervalued on this framework.
This kind of gap can point to either a strong opportunity if the cash flow assumptions hold up, or a warning that the model is too optimistic. The key question for you is which story feels more realistic for Pop Mart International Group over the long haul.
Look into how the SWS DCF model arrives at its fair value.
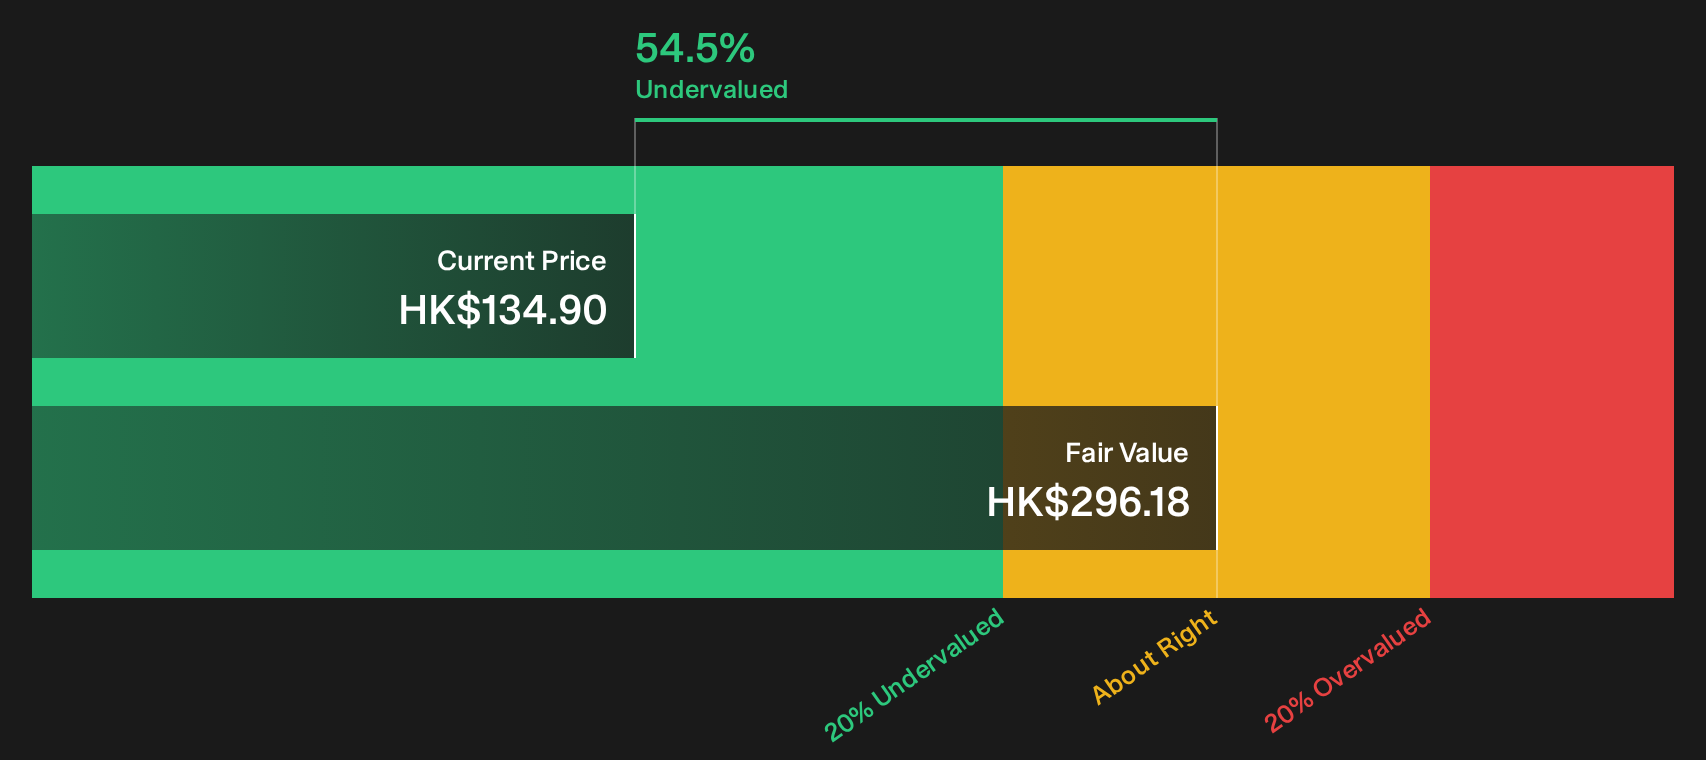
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pop Mart International Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Pop Mart International Group is clearly split. Move quickly, review the numbers for yourself, and weigh both sides of the story through the 2 key rewards and 2 important warning signs
Ready for more ideas beyond Pop Mart International Group?
Do not stop with Pop Mart International Group. Broaden your watchlist now using focused stock lists that surface stronger balance sheets, income potential, and mispriced opportunities.
- Target resilience by reviewing companies with robust finances through the list of solid balance sheet and fundamentals (199 results).
- Boost your income focus by scanning cash generating businesses in the 221 dividend fortresses.
- Spot potential mispricings early by combing through the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com