


EN
What Cognizant Technology Solutions AI Push Means For Shareholders
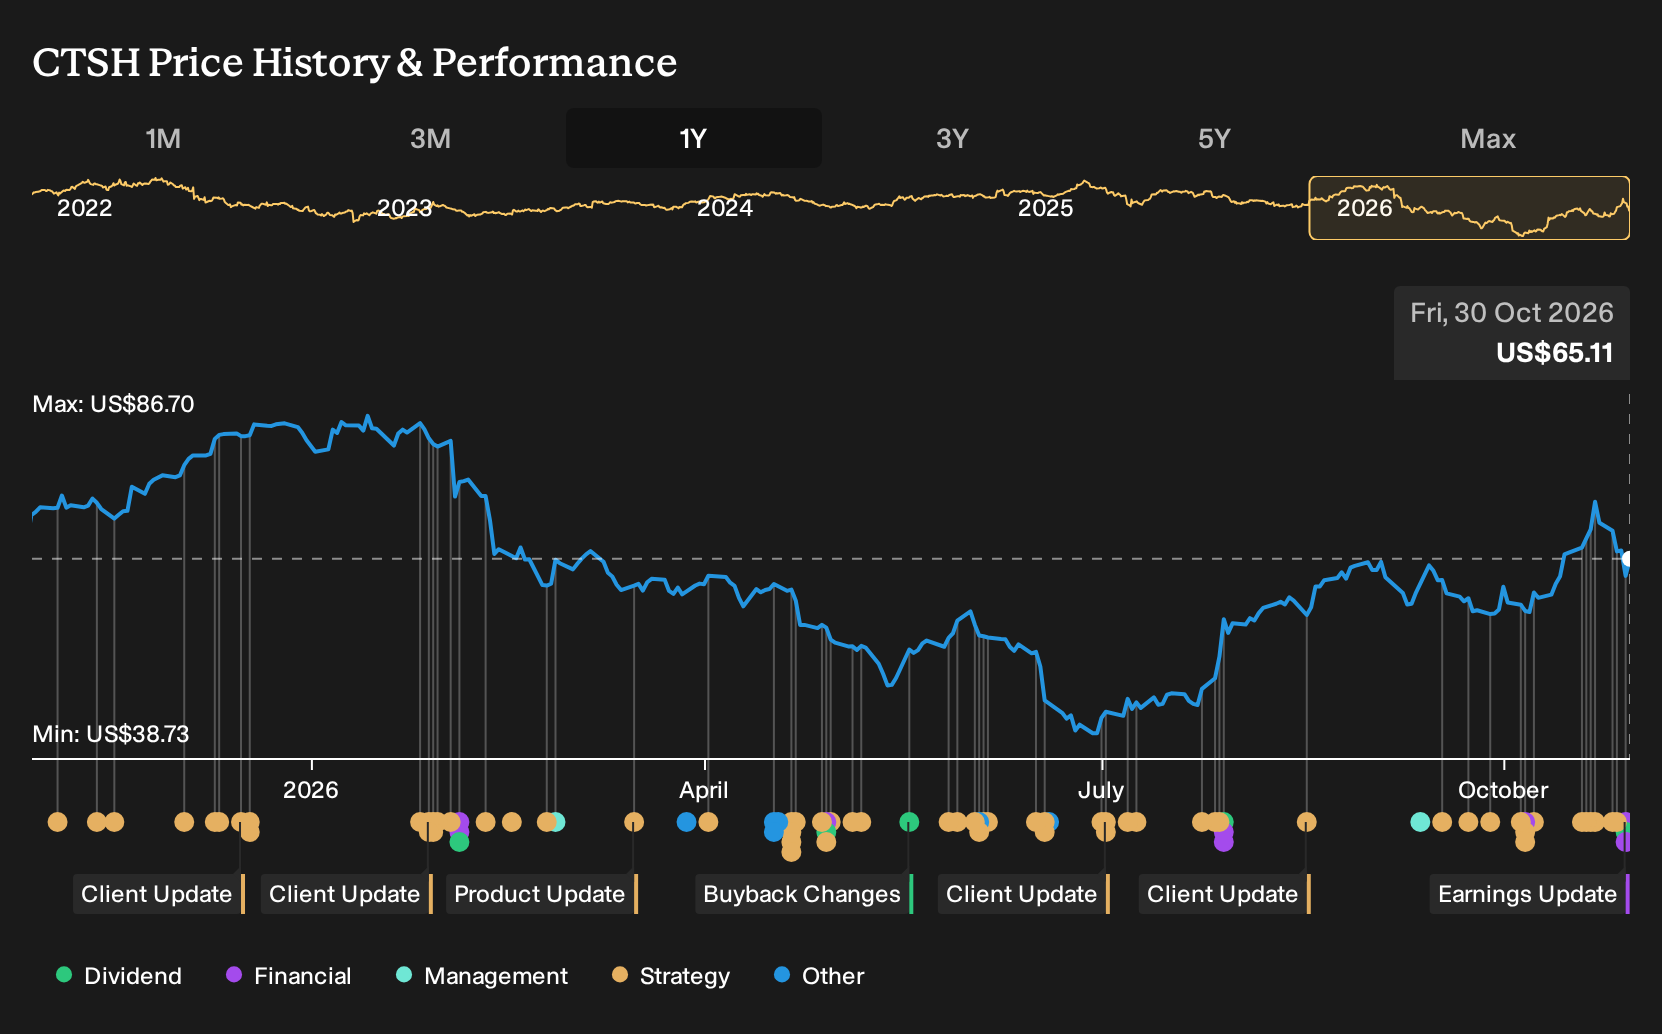
- Cognizant Technology Solutions reported Q3 2026 sales of US$5,664 million, net income of US$627 million and an adjusted operating margin at a four year high. The company also affirmed a US$0.33 quarterly dividend and issued 2026 revenue guidance of US$22.05 billion to US$22.14 billion.
- The business is pushing hard into AI led delivery, forming an OpenAI Frontier Capability Group of more than 25,000 professionals, alongside expanded Gemini and AI Nexus initiatives that are already embedded in large client programs across travel, healthcare, financial services and payments.
- The focus now shifts to how Cognizant Technology Solutions' margin profile and new OpenAI Frontier Capability Group may influence its longer term investment narrative.
Cognizant Technology Solutions Investment Narrative Recap
To own Cognizant Technology Solutions, you need to believe its AI led delivery model, outcome based contracts and higher margin platforms can offset client caution in discretionary IT budgets. The short term swing factor is whether the current wave of AI led deals and 4% to 4.4% 2026 revenue guidance actually translate into steady bookings and margins at or above recent levels.
The biggest risk remains execution on complex, fixed price and transaction based work as clients in healthcare, communications and consumer sectors stay selective on new projects. The new OpenAI Frontier Capability Group helps the delivery story, but it does not remove pricing pressure or the chance that cautious spending weighs on revenue versus guidance.
The formation of Cognizant Technology Solutions’ OpenAI Frontier Capability Group looks most relevant here. It concentrates more than 25,000 professionals on Codex, ChatGPT and related tools, focused on AI native software engineering, application modernization and agentic customer operations. That directly connects to management’s push toward AI assisted delivery and higher revenue and operating income per associate.
For catalysts, this OpenAI focused unit gives the firm a clear operational platform to pursue large enterprise deals, including the 8,500 AI engagements already in motion. It also sharpens the margin risk. Outcome based, AI heavy work can lift efficiency if delivery is tight, or compress profitability if fixed bid contracts underprice complexity or if clients internalize more AI capability over time.
Cognizant Technology Solutions' analyst narrative points to revenues of US$24.9b and earnings of US$3.2b by 2029, which implies 4.7% yearly top line growth and an earnings increase of about US$1.0b from current earnings of US$2.2b.
Uncover why Cognizant Technology Solutions' fair value is effectively consistent with its current price.
Exploring Other Perspectives
The alternate view on Cognizant Technology Solutions zeroes in on contract risk. You might see the new OpenAI Frontier Capability Group as a clear win, yet the most cautious analysts worry that fixed bid and transaction work, already above 50% of revenue, could squeeze profitability. Their March 2026 forecasts only penciled in roughly US$24.5b of 2029 revenue and US$3.1b of earnings, using a steeply discounted 7.4x P/E. Those numbers sit below the consensus path, which shows how far opinions can spread. With this fresh Q3 2026 update and the OpenAI push now public, both the bullish and bearish stories may shift. It is therefore worth comparing these older assumptions with your own expectations.
Explore 5 other Cognizant Technology Solutions fair value estimates, including one that suggests as much as 26% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Cognizant Technology Solutions research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cognizant Technology Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognizant Technology Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cognizant Technology Solutions?
If you want to benchmark Cognizant Technology Solutions against other possibilities, it helps to scan a few focused sets of stocks rather than scrolling through tickers at random. The Simply Wall St Screener lets you do exactly that by zeroing in on the kind of financial traits you care about most.
- If capital preservation sits high on your list, start with companies that score well on resilience and risk controls through the 29 resilient stocks with low risk scores.
- Income focused investors can tune their watchlist toward steady cash returns by reviewing a curated group of potential high yield payers via the 5 dividend fortresses.
- For those hunting for quality that is not widely watched, it can be useful to scan a focused pool of under the radar opportunities using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com