


EN
Nordson (NDSN) Eyes AI Demand, Is The Upside Already Priced In?
Nordson (NDSN) is back in focus after fresh commentary highlighted how expanding semiconductor and electronics manufacturing for artificial intelligence infrastructure could support demand for its precision dispensing and coating equipment, while diversified end markets temper single sector reliance.
The recent pullback, with a 1-day share price return down 1.95% to US$322.67 and a 30-day share price return down 3.26%, comes after strong year-to-date share price gains of 33.87% and a 1-year total shareholder return of 40.84%. These returns reflect growing optimism around Nordson’s role in AI-linked semiconductor spending, as well as its diversified industrial and medical exposure. That enthusiasm now appears to be cooling at the margin as investors reassess how much future growth is already reflected in the price.
Scan how Nordson’s AI-linked equipment story compares with other potential beneficiaries of this spending wave by reviewing the 54 AI infrastructure stocks in one place.
Nordson’s AI story, diversified end markets and a near US$18.0b market value are already on the table. The real test now is whether the current valuation still leaves meaningful upside ahead or has already front loaded most of it.
Most Popular Narrative: 8% Undervalued
Nordson’s most followed narrative pegs fair value at $349.71, compared with the last close of $322.67. This frames the current price as modestly below that estimate and puts the focus on how durable its earnings mix really is.
Continued application of the Ascend Strategy and NBS Next framework, which has helped sustain EBITDA margins around 32% of sales and free cash flow consistently above 100% of net income while reducing lead times and improving on time delivery, gives Nordson room to support future margin resilience and cash funded earnings growth.
See why 14 investors see Nordson as 8% undervalued.
Result: Fair Value of $349.71 (UNDERVALUED)
Still, if Nordson’s heavy tilt toward semiconductor and medical demand or its high cash conversion lead investors to pay a richer P/E, this “modest undervaluation” story could change quickly.
Find out about the key risks to this Nordson narrative.
Another View: What Nordson’s P/E Is Telling You
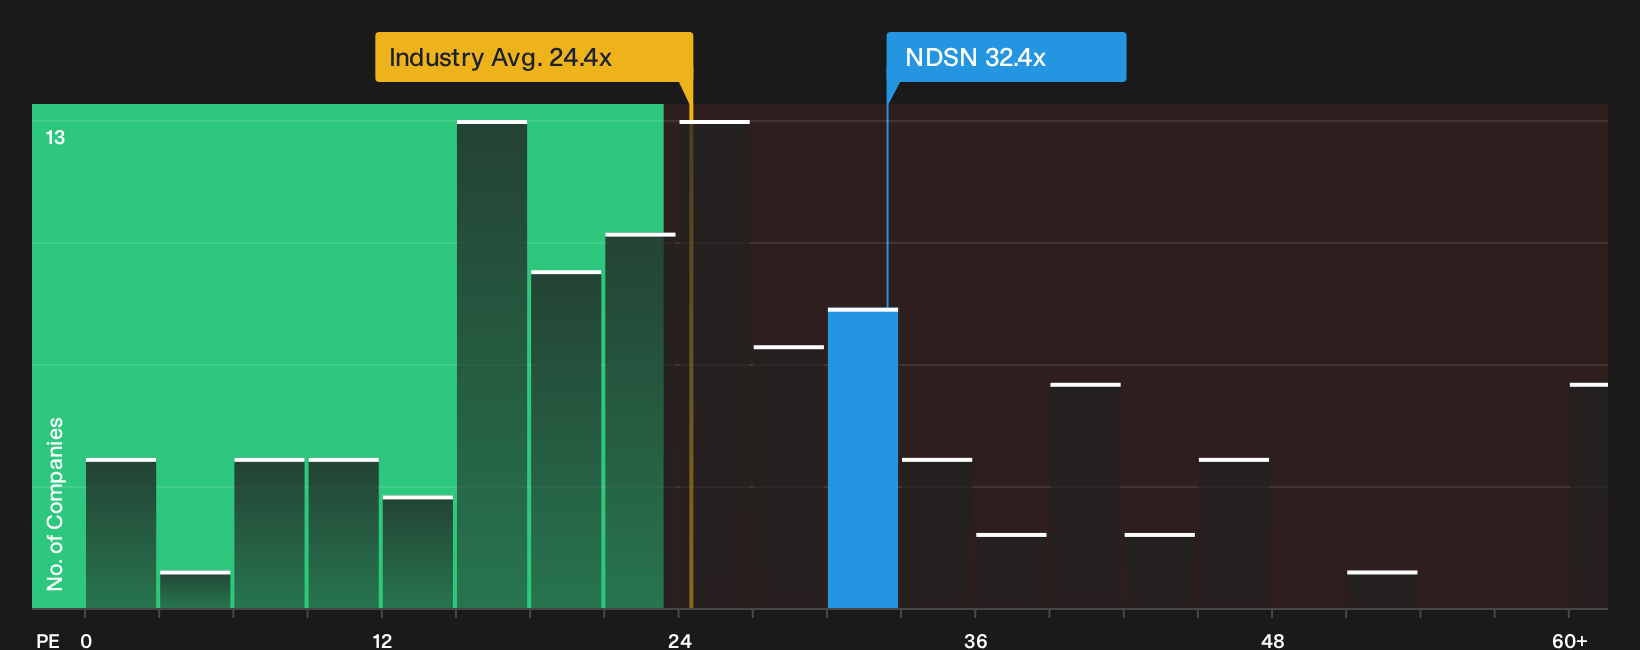
Multiples tell a different story. Nordson trades on a P/E of 32.4x, above both the US Machinery industry at 24.4x and its peer average of 29.6x, and above a fair ratio of 23.2x. That gap points to valuation risk if sentiment cools or execution wobbles.
The key question is whether Nordson’s mix of higher growth end markets and strong cash generation is enough to keep investors comfortable paying that premium multiple. Alternatively, the market could drift closer to the fair ratio over time, compressing returns even if earnings keep moving up.
Before leaning on any single metric, it helps to see how this richer P/E fits into a fuller breakdown of the numbers and where pressure points might sit in different scenarios. For that, it is worth checking the See what the numbers say about this price — find out in our valuation breakdown..
To put Nordson’s current valuation premium in visual context against its sector and that fair ratio anchor, review the
Next Steps
Sentiment around Nordson is mixed, with legitimate concerns on one side and genuine bright spots on the other. Move quickly through the data, pressure test both angles, and then ground your own view with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nordson?
If Nordson has sharpened your thinking, do not stop there. Broader context across other high quality businesses can help you judge whether its current pricing really stacks up.
- Target reliable compounding potential by scanning a 33 high quality undervalued stocks that couples stronger balance sheets with pricing that still sits below many fair value estimates.
- Prioritise resilience and sleep better at night by reviewing a 29 resilient stocks with low risk scores focused on businesses with sturdier financial profiles and fewer red flags.
- Spot opportunities before the crowd by checking a 19 high quality undiscovered gems that highlights strong fundamentals hiding behind quieter tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com