


EN
How Investors Are Reacting To Getty Realty Stock As Quarterly Results Improve
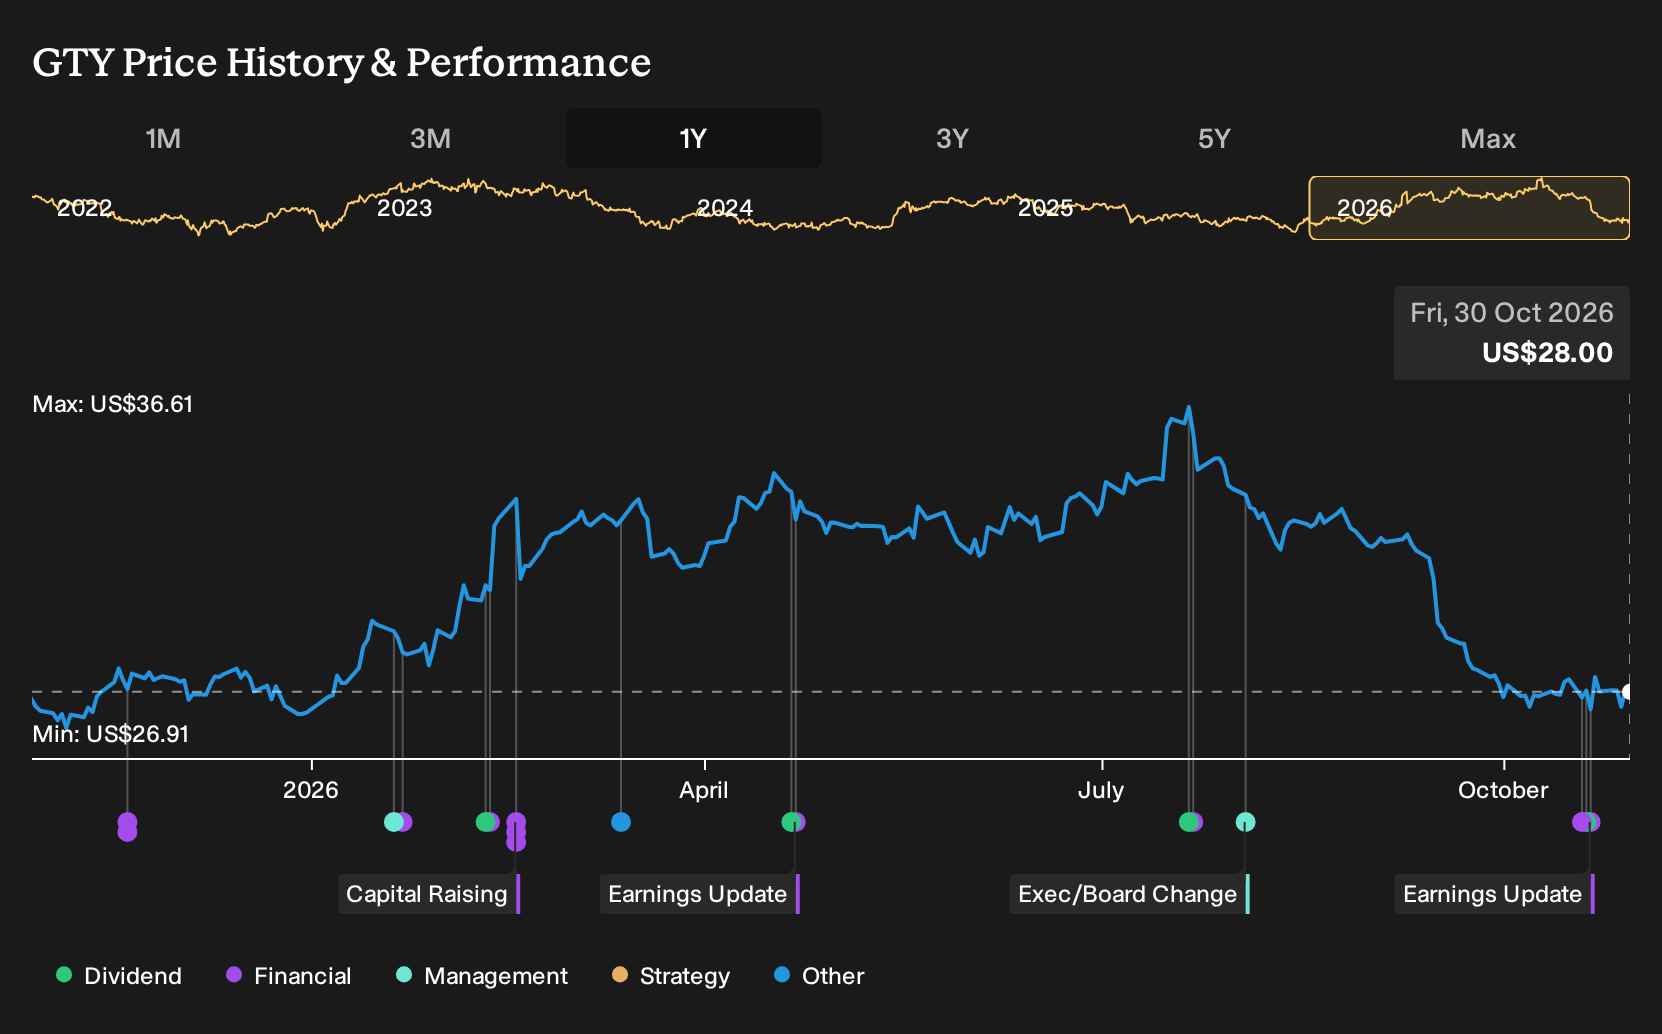
- Getty Realty reported third quarter 2026 revenue of US$62.99 million and net income of US$25.61 million, with nine month revenue at US$179.89 million and net income at US$74.82 million, alongside a quarterly dividend declaration of US$0.50 per share and a new US$200 million unsecured term loan facility.
- The combination of higher year to date earnings per share from continuing operations and additional credit capacity gives Getty Realty more room to fund its net lease portfolio while maintaining regular cash returns to shareholders.
- Attention now turns to how Getty Realty's investment narrative evolves in light of higher year to date earnings per share and expanded term loan capacity.
Scan how Getty Realty fits into the wider income and real estate picture by comparing it with 5 dividend fortresses holding up under different payout and balance sheet profiles.
Getty Realty Investment Narrative Recap
To own Getty Realty, you need to be comfortable with a net lease model tied heavily to convenience and automotive tenants, and with fuel centric traffic still supporting many locations. The short term upside story rests on keeping occupancy high and rent coverage solid while deploying fresh capital into accretive sale leasebacks and development projects.
The latest quarter shows higher year to date earnings and net income, which supports that thesis but does not radically change it. The key near term risk is still funding new deals at attractive spreads versus borrowing costs, especially with interest expense already flagged as a pressure point in prior analysis.
The new US$200 million unsecured term loan is the announcement that matters most here. This extra capacity gives Getty Realty more flexibility to pursue its acquisition pipeline and development fundings, provided the firm stays within the financial covenants around leverage, coverage ratios and minimum tangible net worth.
For you as an investor, the term loan ties directly into both catalysts and risks. More dry powder can help grow rental income if deals are underwritten carefully. At the same time, higher debt and interest obligations could tighten headroom on those covenants, particularly if any tenants struggle or if car wash and convenience assets take longer to reach targeted rent coverage.
Getty Realty's narrative projects US$306.9 million revenue and US$108.1 million earnings by 2029. This setup assumes 9.6% yearly revenue growth and an earnings increase of about US$11.8 million from US$96.3 million today.
Uncover why Getty Realty's fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community span roughly US$33.86 to US$73.48 per share, so retail opinions on Getty Realty are wide apart. That spread now meets fresh data on the US$200 million term loan, tighter covenants and the new dividend level, giving you plenty of alternative viewpoints to consider.
Explore 2 other Getty Realty fair value estimates, including one that suggests potential upside of up to 162% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Getty Realty research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Getty Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getty Realty's overall financial health at a glance.
Looking for more Getty Realty investment ideas?
Once you have a view on Getty Realty, it can help to put it in context by lining it up against other companies with different yields, balance sheet strength, and risk profiles using the Simply Wall St Screener.
- If you want candidates that combine resilience with measured risk, start with a 29 resilient stocks with low risk scores that may appeal if you prefer fewer surprises when markets get volatile.
- For investors who care about dependable income but still want quality fundamentals, scan a curated 5 dividend fortresses that can sit alongside Getty Realty in an income focused portfolio.
- When you are hunting for strong businesses that are not yet widely followed, broaden your watchlist with a 19 high quality undiscovered gems that could complement a more established holding like Getty Realty.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com