


EN
How Investors Are Reacting To Albany International (AIN) Return To Profit
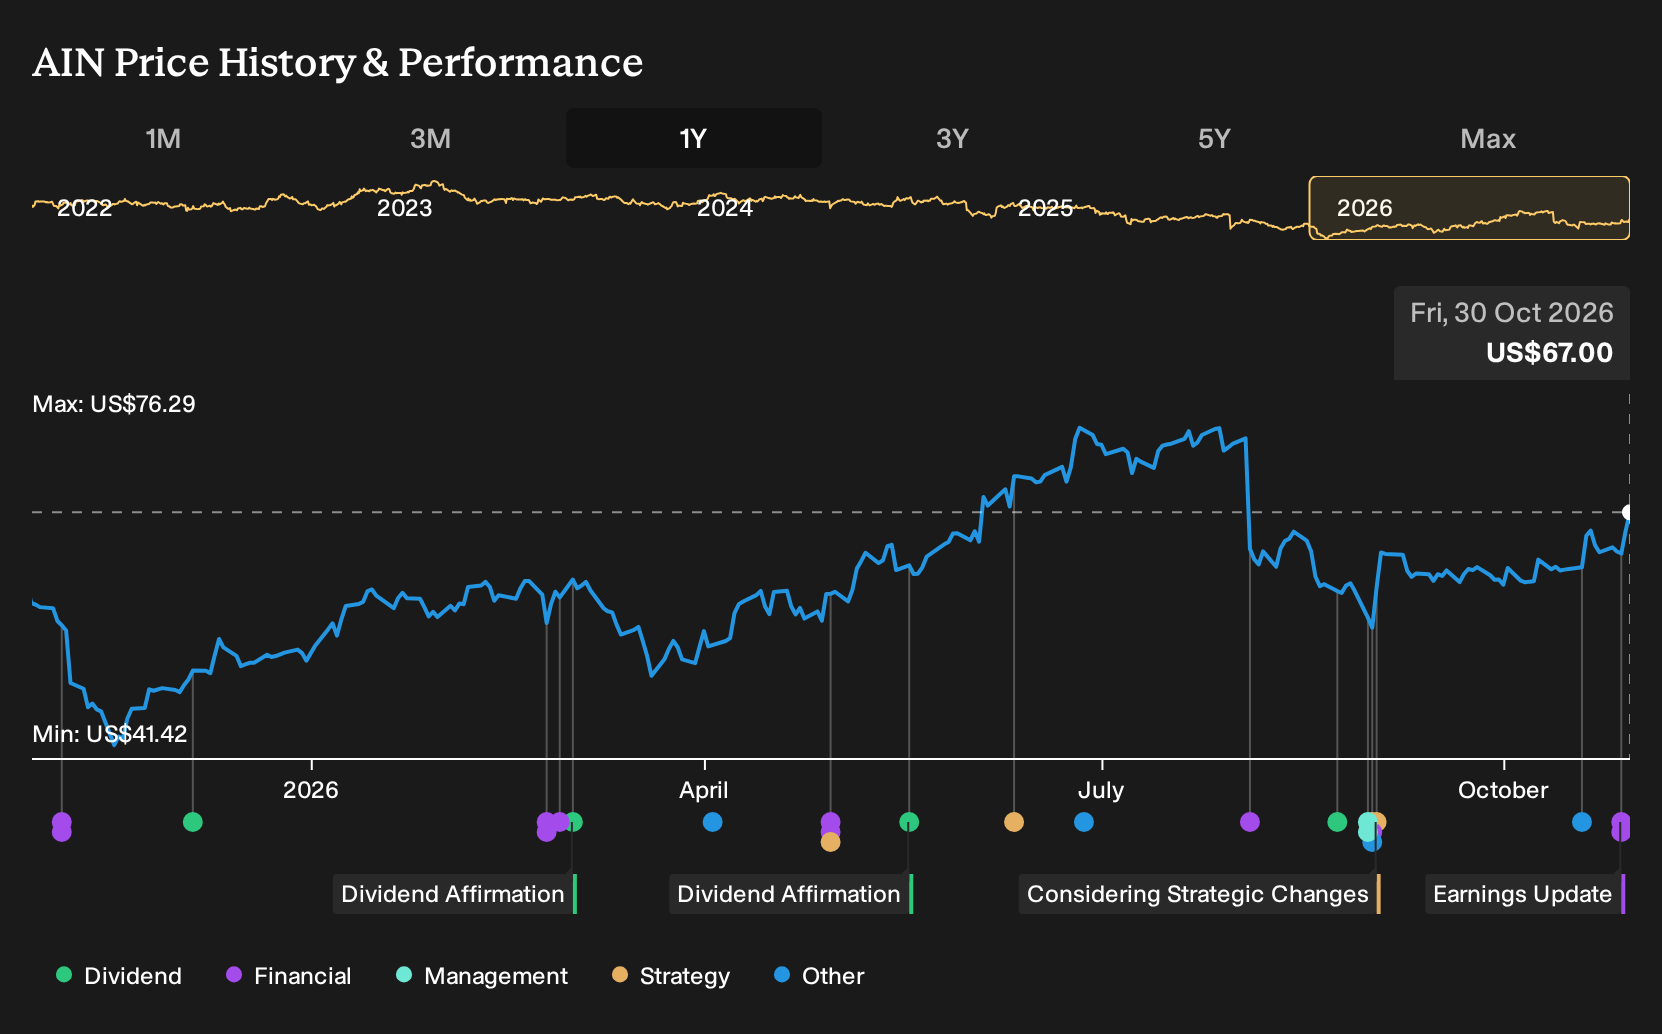
- Albany International reported third quarter 2026 sales of US$349.54 million and net income of US$41.7 million, a shift from a loss a year earlier, with basic earnings per share from continuing operations at US$1.47.
- The return to profit was closely linked to stronger Engineered Composites performance and the cleanup of the CH 53K helicopter contract, which together reduced legacy program risk and clarified the earnings power of the composites portfolio.
- The next area of focus will be how this profitability return in Engineered Composites could reshape Albany International's broader investment narrative.
Albany International Investment Narrative Recap
To own Albany International, you need to believe the Machine Clothing segment can keep throwing off cash while Engineered Composites grows into a steadier profit engine. The third quarter swing back to a US$41.7 million profit, with US$1.47 in basic EPS from continuing operations, supports that thesis but does not remove execution risk.
The key short term catalyst is whether Engineered Composites can sustain cleaner margins now that the CH 53K contract has been reset and legacy drag reduced. The biggest risk still sits in weaker Machine Clothing demand and pricing if paper and packaging customers stay under pressure, especially given the company’s higher debt load.
The most relevant new detail is Albany International’s fourth quarter 2026 revenue guidance of US$325 million to US$335 million. That range frames what management thinks is realistic after the record third quarter, so it is a useful yardstick for how durable the recent composite driven strength might be into year end.
For you as an investor, that guidance helps anchor expectations on near term execution while the longer term catalysts remain tied to aerospace and defense composites ramping and Machine Clothing holding margins. Any shortfall versus this guidance would quickly refocus attention on capital intensity, cash conversion, and how much room there is to support dividends.
Albany International analysts are assuming yearly revenue growth of 7.0% and see earnings moving from a current loss of US$51.2 million to US$379.1 million by 2029. This implies an earnings increase of about US$430 million, on projected 2029 revenue of US$1.5b.
Uncover why Albany International's fair value indicates that Albany International is in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts were already leaning hard into the Engineered Composites catalyst at Albany International, expecting revenue to reach about US$1.6b and earnings of US$153.2 million by 2029 before this quarter’s profit swing. You can treat this earnings beat as a fresh test of that upbeat view, and then compare it with more cautious scenarios.
Explore another Albany International fair value estimate, including one that suggests potential upside of up to 38% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Albany International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Albany International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albany International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Albany International?
Once you have a view on Albany International, it often helps to benchmark that thinking against other listed businesses with different risk and income profiles.
- If you want steadier balance sheets and fewer financial surprises, start with a list of solid balance sheet and fundamentals (24 results) that pass strict leverage and liquidity filters.
- Income focused investors may prefer reliable cash returns, so line up potential yield plays with a curated set of 5 dividend fortresses that meet your payout criteria.
- For those hunting for mispriced opportunities with strong fundamentals, broaden your watchlist by scanning a 19 high quality undiscovered gems that often sit outside the usual broker coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com